

Uncategorized @vi
Find the Best Pool Financing Rates for Your Backyard Oasis Today
Find the Best Pool Financing Rates for Your Backyard Oasis Today
Last updated: 2026-10-17
Transforming your outdoor space into a personal sanctuary is a monumental project. Most families find that their liquid savings fall short of the total bill. Whether your heart is set on an inground pool, an upscale saltwater system, or a premier swim spa, finding the necessary capital is your first hurdle.
Don’t let the sticker price fool you. The real cost of an aquatic retreat often climbs higher than expected. You must budget for heavy excavation, complex plumbing, electrical upgrades, and the masonry needed to finish the landscape. It is a mountain of expenses that can quickly snowball if you aren’t careful.
Finding a lender is a deeply personal journey. A solution that fits a homeowner with stellar credit might be a total dead end for someone navigating a recent fiscal stumble. For instance, a person boasting a 780 FICO score might find it easiest to walk through a standard bank’s doors.
On the other hand, an individual with a 620 score might find better luck with niche lenders. These companies often value steady income more than a flawless credit report. Our goal is to highlight the most dependable ways to fund your backyard dreams. We want to prevent you from falling into high-interest traps that could haunt your budget for years.
- Avant
- FastLendGo
- HFS Financial
- Acorn Finance
- LightStream by Truist
Our Criteria for Selecting the Best Pool Financing Options
When we sat down to vet these lenders, we kept the unique hurdles of backyard renovations at the forefront of our minds. A company that primarily handles basic debt restructuring might find themselves out of their depth when faced with a complex construction timeline. Building a swimming pool isn’t as simple as buying a new car.
Think about how the money actually moves once the shovels hit the dirt. You’ll likely drop a down payment upfront, follow that with a second installment once the digging is done, and settle the remainder once the water is sparkling. While a single large payout works in a pinch, it’s much smoother when a lender understands this rhythmic payment cycle.
Our team scrutinized how flexible the credit requirements were and how much red tape a homeowner would face during the application. We looked for those “lightning-fast” approval times that act like a lifesaver. If your contractor is ready to start digging tomorrow, you certainly don’t want a sluggish banking institution stalling your progress.
Losing your place on a busy builder’s summer schedule is a nightmare no one wants to experience. We prioritized companies that get out of your way quickly so the project can move forward without any unnecessary friction or delay.
We also placed a heavy emphasis on the availability of “soft pull” credit checks. This allows you to shop around for the best interest rates without taking a hit to your credit score. It’s a vital feature for anyone trying to budget carefully without causing a dip in their financial standing.
Every single provider was measured against how they actually perform in the real world. We looked at the entire journey, from that first curious inquiry all the way to the moment the funds are released for your contractor.
Evaluating Top Options for Pool Loans
Selecting the right lender can feel like navigating a labyrinth without a map. You want a partner that doesn’t leave you high and dry when the construction crew arrives. Every financing company brings a different flavor to the table, offering various terms and speed levels.
Some providers focus on quick cash for minor repairs, while others are built for massive backyard transformations. It is vital to weigh your personal credit history against the specific needs of your renovation project. Don’t let the temptation of a low rate blind you to the fine print.
I remember a neighbor who jumped at a low percentage rate, only to realize his loan amount was capped too low. He ended up paying more in the long run. It pays to look at the big picture before signing on the dotted line today.
| Institution | Borrowing Limits | Annual Percentage Rate | Credit Score Criteria | Processing Time |
|---|---|---|---|---|
| Avant | Refer to website | Refer to website | Refer to website | Refer to website |
| FastLendGo | $500 – $5,000+ | Refer to website | Poor to Excellent Credit | Refer to website |
| HFS Financial | $1,000 – $450,000 | Starting at 7.80% | Low Credit Solutions | Refer to website |
| Acorn Finance | A maximum of $100,000 | Starting at 6.99% | Fair and Poor Credit | Refer to website |
| LightStream by Truist | Refer to website | Refer to website | Refer to website | Refer to website |
Comparing the Top 5 Pool Financing Providers
1. Avant
Avant acts as a highly adaptable contender within the personal loan arena. They strive to empower clients through a variety of flexible loan paths tailored to different life circumstances. Their digital platform is built specifically for those who crave a smooth, uncomplicated experience.
Imagine standing in your freshly landscaped backyard, checking your loan status on a smartphone. This tech-forward interface makes managing your debt feel effortless. It is a modern financial solution designed to match your contemporary lifestyle.
If you find yourself caught between a high-interest credit card and a cumbersome mortgage, Avant might be your lifeline. Small upgrades like a luxury hot tub or a fancy new filtration system are easy to fund without the mountain of paperwork typical of a HELOC.
Whether you are installing a stone walkway or a small fire pit, they provide the liquidity needed for backyard transformations. They bridge the gap between minor repairs and major renovations with ease.
Pros:- Adaptable loan structures for various life stages.
- Streamlined digital application for ease of use.
- Options to manage debt while upgrading your home.
- Lacks the specific construction-focused terms offered by niche lenders.
2. FastLendGo
For those who feel ignored by traditional brick-and-mortar banks, FastLendGo serves as a vital bridge. They specialize in catering to a massive spectrum of credit backgrounds, from those rebuilding their scores to those with pristine credit. It is a lifeline if you need to snag a seasonal discount from a pool contractor via fastlendgo.com.
The scope of their assistance is broad. You might need a quick $500 to fix a busted pump, or perhaps a much larger sum for a vehicle repair to avoid high-interest debt. They understand that life is unpredictable and often expensive.
They act as a rapid comparison tool, scanning the horizon to find local lenders on your behalf. This efficiency is a godsend for homeowners eager to break ground. They often locate matches for people who have been turned away by local credit unions.
Pros:- A massive variety in possible loan amounts.
- Specializes in helping those with fair or poor credit.
- Efficiently compares many local financing sources.
- Borrowers with poor credit may face significantly higher interest rates.
3. HFS Financial
When it comes to heavy-duty home improvements, HFS Financial is a heavyweight champion. Their expertise is laser-focused on the physical assets you are installing, like inground pools, spas, or even solar energy systems. They realize a $50,000 pool is a significant real estate investment, not just a purchase.
Their financing limits are quite staggering, reaching as high as $450,000. This amount can cover a full pool installation, a detached pool house, and even professional landscaping. It is a heavyweight solution for massive backyard overhauls.
This lender is the gold standard for homeowners planning a total outdoor metamorphosis. They specialize in the intricate details of luxury swim spas and inground pools, offering competitive starting rates around 7.80%.
They utilize a “contractor-direct” methodology. This means the lender often coordinates with your installer, releasing funds in stages as specific project milestones are reached. It keeps everyone on the same page.
Pros:- Huge loan ceilings for massive construction projects.
- Deep expertise in pool and hardscape financing.
- Checking your rates won’t ding your credit score.
- Securing such large amounts often requires extensive documentation.
4. Acorn Finance
Acorn Finance utilizes a clever marketplace model that pairs borrowers directly with skilled contractors. This service is entirely free for both sides, which is a breath of fresh air in a crowded market. They prioritize transparency, ensuring no hidden dealer fees get tacked onto your final quote.
Using this platform is about more than just finding cash; it is about finding the perfect financial partner for your specific project. It is like finding the exact tool required for a delicate job.
Convenience is their calling card. You can investigate personalized rates without any impact on your credit score. This is perfect if you are still in the “blue sky” dreaming phase and want to see what your budget can actually do.
Try comparing the monthly cost of a $20,000 concrete shell against a $60,000 fiberglass version. You can test the waters and see the financial differences without any risk to your credit standing.
Pros:- Absolutely no hidden dealer fees for the borrower.
- View custom rates without affecting your credit score.
- Extremely high levels of user satisfaction.
- The marketplace structure involves interacting with various lenders.
5. LightStream by Truist
LightStream by Truist is a top-tier choice for homeowners who want to fund a pool without risking their house. Their digital-first approach is sleek and efficient, focusing on the renovation itself rather than complex debt structures. It is a very clean way to handle your math.
Because these loans are unsecured, your home isn’t used as collateral. If a project goes over budget or life throws a curveball, your roof is safe. You can build your backyard oasis without putting your primary residence on the line.
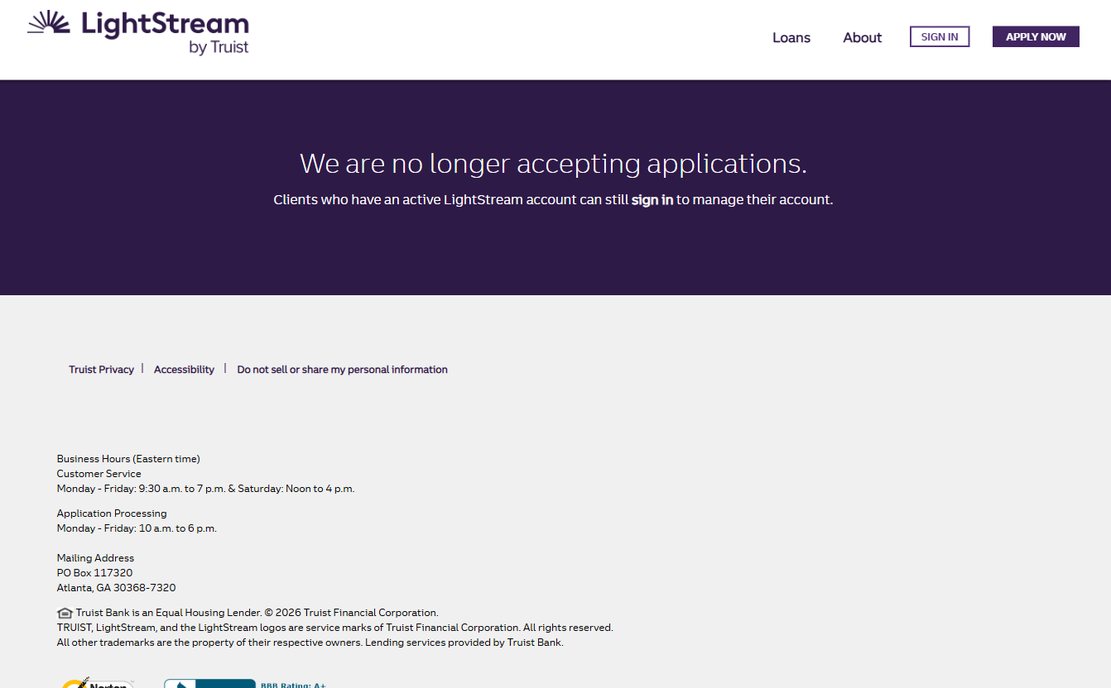
While their availability for new applications can shift periodically, they set the benchmark for high-quality, rapid lending. For those with stable income and high credit scores, it is a seamless path to home improvement.
The approval speed is legendary, often occurring within a matter of hours. This can move you from the drawing board to the construction site incredibly fast. You could be splashing in the water by next month.
Pros:- Removes the risks associated with home equity loans.
- Fast, streamlined, and simple online application.
- The peace of mind that comes with Truist’s backing.
- Application windows and availability can change.
Navigating the Real Expenses of Backyard Loans
A common blunder for many property owners involves fixating exclusively on what leaves their bank account each month. A $150 installment might seem like a breeze compared to a $600 burden, but you really need to tally up every cent of interest paid throughout the loan’s lifespan. It is a classic pitfall that catches people off guard.
Take a $40,000 debt at an 8% interest rate as an example. When stretched over 10 years, the total amount paid is much higher than if you settled it in 5 years. If your budget allows for larger monthly contributions, you’ll end up saving thousands in interest and securing your backyard oasis much sooner.
Think of it as a marathon rather than a sprint. If you run too slow, the total cost of the race becomes astronomical. Choosing a shorter term might feel a bit tight on your wallet today, but it prevents a massive financial leak in the long run.
Keep a sharp eye out for these three frequent financial snags:
- The “Scope Creep” Snag: A project originally quoted at $30,000 frequently balloons to $40,000 when you hit unexpected bedrock, tricky soil, or decide on fancy new filtration hardware. It is wise to secure a bit more than the initial estimate. This prevents the headache of taking out a second, much costlier loan midway through construction.
- The Interest Rate Snag: Don’t let a shiny teaser rate blind you. You must scrutinize the APR (Annual Percentage Rate), which factors in interest alongside any origination fees. An “affordable” rate paired with a 5% origination fee can actually cost you more than a slightly higher rate that carries zero fees.
- The Fixed vs. Variable Snag: Double-check whether your rate stays steady for the entire term. While variable rates might look tempting at first, they can climb if market trends shift. Suddenly, your dream pool becomes a heavy weight on your finances during a shaky economy.
Organizing Your Paperwork for Rapid Funding
Don’t let your backyard oasis turn into a waiting game due to missing paperwork. If you want to transition from sketches to actual digging without a hitch, you must assemble your financial files before hitting that “apply” button. Lenders aren’t mind readers; they need a crystal-clear view of your cash flow to feel confident in your loan.
Getting your ducks in a row early can cut weeks off the waiting period. Think of it like a pit stop in a race; the faster you prepare, the quicker you cross the finish line. Having these items scanned and ready to go is the secret sauce to a smooth approval.
Create a dedicated digital directory containing these specific items:
- Evidence of Earnings: Grab your two latest pay stubs alongside your W-2 forms from the previous two years. If you’re your own boss, pull your tax returns for the last two years. Keep in mind that lenders care more about your net take-home pay than your total top-line revenue.
- Contractor Estimates: Secure at least two comprehensive, written bids from well-known pool builders. Companies like Acorn Finance or HFS Financial often demand these to confirm the loan is actually for a legitimate project and to validate the total cost.
- Bank Records: Gather recent statements from both your savings and checking accounts. It’s vital to show you have a financial safety net for those initial down payments and the long-term upkeep of your new aquatic feature.
- Personal Identification: You will need a current driver’s license and a few recent utility statements to prove where you live.
Treating this loan with the same meticulous care as a home mortgage is a smart move. This level of precision signals to the bank that you are a safe bet, which can be a real game-changer.
When you present yourself as a low-risk candidate, you aren’t just speeding up the timeline. Often, this high level of organization leads to much better interest rates. In the long run, that efficiency translates directly into extra cash staying in your pocket for your backyard transformation.
Mapping Out Your Backyard Investment
Don’t let a flashy interest rate blindside you during the decision-making process. It is absolutely essential to evaluate the full financial commitment of your debt. While a small monthly bill might feel like a breeze initially, stretching the loan duration can result in paying thousands of dollars extra in interest over time.
This math becomes particularly heavy when you are financing a massive inground pool. When the principal amount is high, every percentage point matters. You should aim to look at the total cost of credit rather than just the monthly snapshot.
Many homeowners make the blunder of forgetting the “invisible” expenses that come with a pool. Installation is merely the first step in a much longer journey. You must account for ongoing costs like electricity for your pumps, various chemicals, and regular maintenance services.
You might even need to secure a specialized insurance rider to protect your new asset. Make sure your total loan covers every single detail, from the initial landscaping and the pool deck to the liner and even the very first startup chemical kit.
If you skimp on these budget lines, you might end up with a stunning, empty basin. There is nothing quite as heartbreaking as a backyard oasis that sits idle because the pump costs are too high to bear.
Before committing, scrutinize the fine print specifically regarding prepayment penalties. Suppose you receive a sudden windfall, such as a bonus at work or the proceeds from a recent sale. You might want to wipe out that debt early.
You really don’t want to be slapped with a penalty just for being financially savvy and paying your debt off ahead of schedule. It is worth weighing the specific terms offered by Avant, HFS Financial, and other lenders to avoid future headaches.
A wise borrower hunts for maximum flexibility. You want the freedom to throw extra cash at your principal whenever your budget allows, ensuring you aren’t punished for being proactive about your finances.