

Uncategorized @vi
Top-Rated Online Personal Loans in Laredo TX: Secure Your Best Rates Today
Top-Rated Online Personal Loans in Laredo TX: Secure Your Best Rates Today
Last updated: 2026-10-16
Imagine being stuck in a parking lot while your car’s transmission gives up the ghost, or facing a sudden hospital bill that arrives without warning. For many folks living in Laredo, these sudden expenses feel like being tossed into a confusing labyrinth without a flashlight. It is never just about the cash itself.
The real weight comes from the mental exhaustion of navigating financial chaos. When a dental crisis strikes out of the blue, the anxiety regarding your bank balance often feels more painful than the actual medical procedure. You deserve a clear path forward when life throws these curveballs.
The way we handle money has undergone a total metamorphosis thanks to the digital age. However, you cannot simply swallow every shiny advertisement that pops up on your smartphone screen. You must dig deeper to ensure the borrowing limits and processing speeds actually align with your specific household needs.
It is easy to get swept up in the hype of “instant approval” promises. Unfortunately, many users find themselves waiting days for funds to land, or they realize the interest rates are predatory compared to standard banking options. Distinguishing a local credit union from a lightning-fast web marketplace is your best defense.
- Parra Loan Company
- JetzLoan
- Bridge Credit Union
- GoCredit
Evaluating Your Financing Choices in Laredo
Speed is the name of the game in our evaluation methodology. Most folks hunting for Laredo loans are essentially racing against a ticking clock. Life in a bustling border hub moves fast, and delays in getting capital can trigger a domino effect of financial headaches.
If your car breaks down and you can’t get to work, that’s not just a repair bill; it is lost wages. We prioritize how quickly money hits your bank account because we know that timing is often everything when emergencies strike.
We also scrutinized the ceiling on borrowing limits and the impact on your credit profile. A “soft pull” is a total lifesaver for anyone feeling a bit shaky about their credit score. It acts as a harmless peek at your numbers without alerting the big bureaus.
You can essentially window-shop across five different providers without seeing your FICO score take a hit. This approach is your golden ticket to hunting down the most competitive APRs available on the market today.
Review the following comparison to grasp how various lending models operate in the current landscape:
| Lending Category | Main Advantage | Ideal For… | Time to Receive Funds |
|---|---|---|---|
| Digital Marketplace | Extensive options and high caps | Major costs (Real Estate/Significant Car Repairs) | 24–48 Hours |
| Signature/Quick Lender | Instant liquidity | Minor emergencies (Electric bills/Fixes) | Minutes to Hours |
| Credit Union | Community-focused and lower interest | Ongoing financial health and minimal APR | 3–7 Business Days |
| Credit Builder | Boosting your rating | Fixing a damaged credit past | Depends on your savings strategy |
Top-Rated Personal Loan Providers in Laredo
1. Parra Loan Company
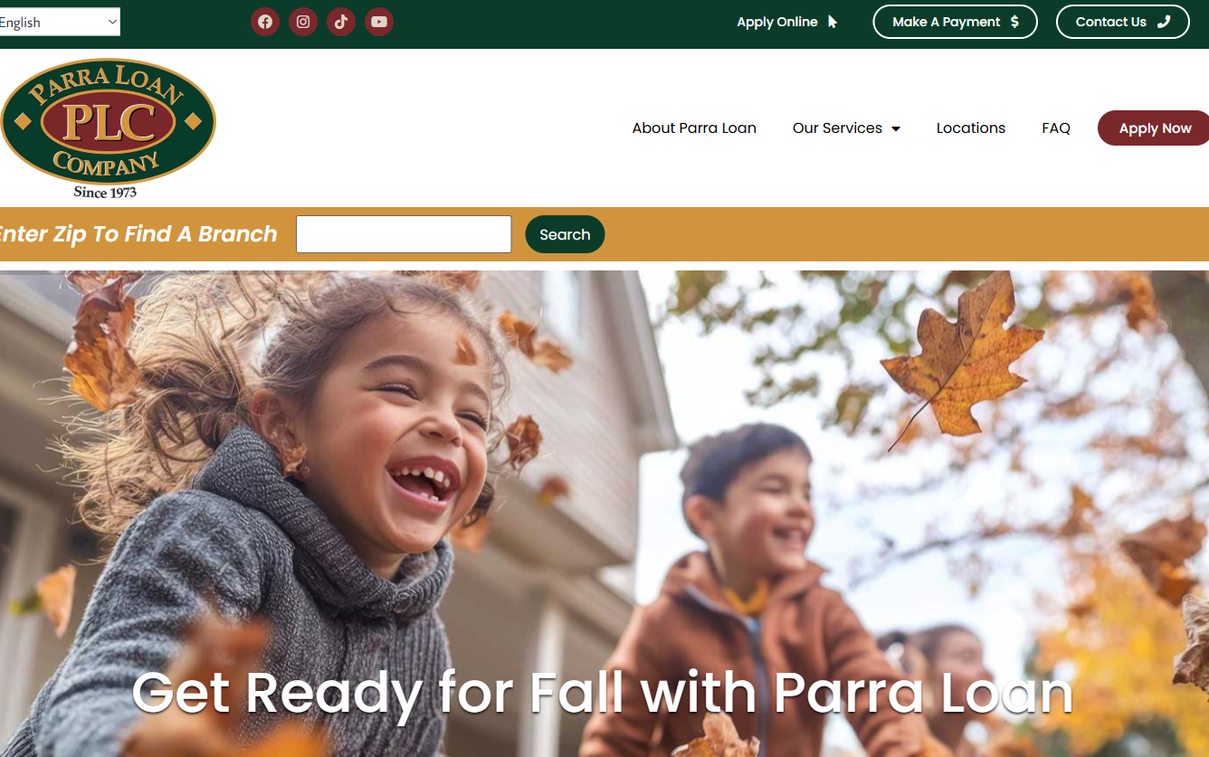
When life throws a curveball and you need cash immediately, Parra Loan Company is ready to step up. They don’t believe in wasting time with complicated red tape or long-term debt restructuring plans. They are designed for those urgent, sudden expenses that require a quick fix rather than a years-long commitment.
Imagine you are staring at a $400 car repair bill that threatens your ability to get to work. In that scenario, a five-year repayment plan feels like a heavy anchor. Parra specializes in these high-velocity moments, providing a streamlined path to getting the funds you need right when it matters most.
This lender acts as a perfect bridge to help you navigate the gaps between paychecks. You enjoy total flexibility by choosing to apply via a smartphone, over the phone, or by walking into a physical branch. You might start your application while waiting for a mechanic to finish up, then call to chat with a real human to finalize things.
Pros:
- Funding ranges from $100 to $1,840.
- Signature loans require no collateral.
- Fast approval, frequently within minutes.
Cons:
- The upper limit for loan amounts is relatively small.
2. JetzLoan
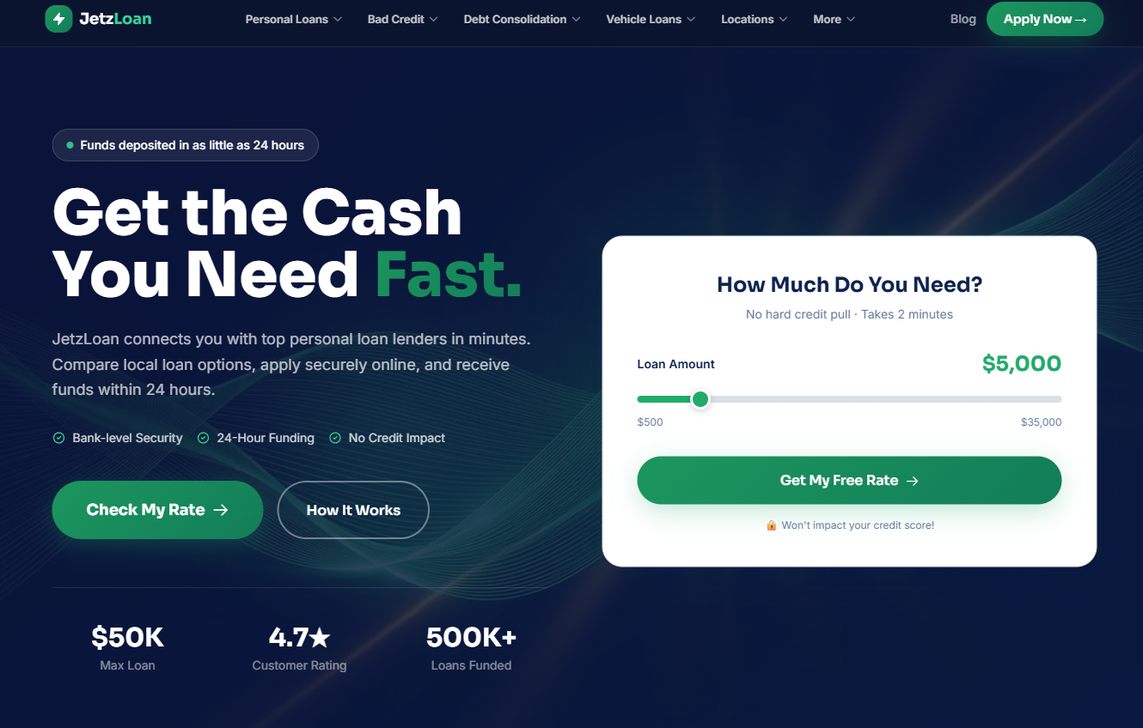
Think of JetzLoan as a massive financial connector rather than a single bank. They act as a bridge, linking you to an expansive network of lenders to find the best match for your specific credit profile. This allows them to offer much larger sums than your local neighborhood bank could typically provide from its own vault.
If you need a substantial $15,000 for a home renovation or a sudden medical procedure, this is a fantastic avenue. Because they scan a vast web of providers, you can explore different options without feeling stuck with just one source of capital.
This is a goldmine for anyone worried that their credit score isn’t perfect. Their “no hard credit pull” method allows you to shop around for the best rates without any damage to your score. You can see your potential terms clearly on your screen before you ever commit to anything at all.
Pros:
- Maximum borrowing capacity reaches $50,000.
- Money can be deposited in as little as 24 hours.
- Checking rates will not impact your credit score.
Cons:
- Because of the connection model, you are working with various lenders.
3. Bridge Credit Union
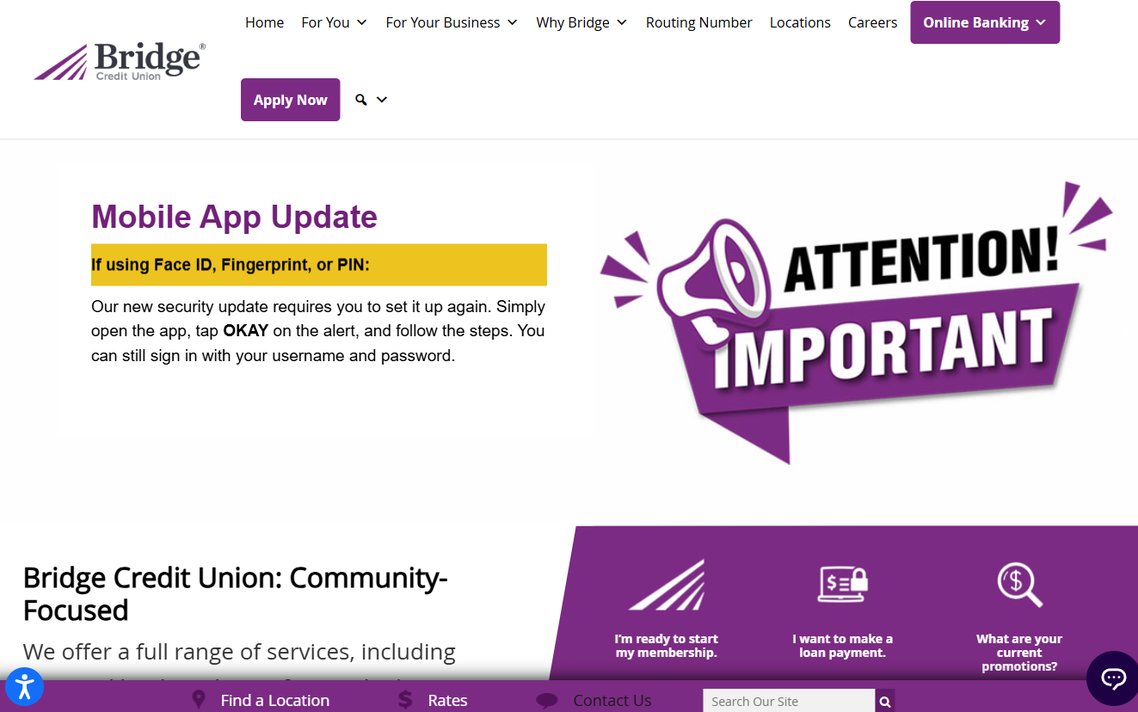
If you prefer a traditional banking experience rooted in the community, Bridge Credit Union is a stellar choice. They offer unique products, such as “skip-a-pay” options and specialized holiday loans, which can act as a lifesaver during a particularly tight month. It is about helping people through life’s ebbs and flows.
Because credit unions are member-owned, their primary goal is to serve the people rather than lining the pockets of distant shareholders. This community-centric focus often translates into much more flexible rules for members who maintain a good standing with the institution.
Stability is the name of the game here. Since they provide both business and personal services, it is a great way to manage your household and your company under one roof. For a Laredo small business owner, having a single institution that understands both your personal bills and your commercial cash flow can truly simplify your life.
Pros:
- Offers skip-a-pay options and holiday promotions.
- Provides both business and personal services.
- Maintains a strong, member-based banking focus.
Cons:
- Traditional documentation may be required more often than instant lenders.
4. GoCredit
GoCredit takes a refreshing approach by focusing heavily on the concept of credit building. Their goal isn’t just to hand you cash today; they want to ensure you can borrow with even more ease in the future. It is a forward-thinking strategy for long-term financial health.
They utilize a unique “loan-to-savings” model, where a portion of every payment you make goes directly into a savings account for you to access later. It essentially functions as a two-in-one financial tool, turning a standard loan into a stepping stone toward real stability.
This is particularly useful for younger borrowers or anyone working hard to repair their credit history. Instead of just paying a bill and ending up back at zero, you finish the cycle with a brand-new savings cushion. This extra layer of protection helps prevent you from falling into the cycle of debt again.
Pros:
- Available loans go up to $4,000.
- Helps establish savings while building credit history.
- The application process is secure and quick.
Cons:
- The focus on building credit might not suit those seeking massive lump sums.
Navigating the Real Price Tag of Your Debt
Before you put pen to paper, scrutinize the Annual Percentage Rate (APR). Many borrowers fall into the trap of staring only at monthly installments, but that’s a dangerous way to view your debt. The APR offers the unfiltered truth by combining interest rates with administrative expenses and origination charges.
Think of it as the complete picture rather than a mere snapshot. Imagine you are staring at two different offers. One carries a 10% interest rate but demands a $500 upfront fee, while another sits at 12% with no extra costs. In many cases, that “cheaper” interest rate is actually more expensive in the long run.
You must also weigh the length of your repayment schedule quite carefully. Choosing a condensed timeline reduces the total interest you hand over to the lender, though it will definitely tighten your monthly cash flow. It is a delicate dance between immediate affordability and the ultimate cost of the money.
Let’s look at a quick mathematical example to make this clear. Borrowing $2,000 at a 15% rate over a single year is far more economical than stretching that same $2,000 debt across 24 months. You’ll need to balance your current wallet capacity against the desire to shake off debt quickly.
Consider these three distinct situations when deciding on your loan structure:
-
The Quick Patch: You find yourself needing $300 to $1,000 right this second to fix a sudden leak or a broken appliance. In these moments, lightning speed is your primary concern. If a high-cost, short-duration loan prevents a catastrophe like a broken car, it might be a lifeline worth taking.
-
The Debt Shuffle: This is for when you need between $2,000 and $7,000 to clean up your finances. The strategy here is to migrate expensive credit card balances into a single, more manageable loan with a lower interest rate to ease your monthly strain.
-
The Big Milestone: When a home renovation or a medical bill requires $10,000 or a larger sum, you must play the long game. At this level, your eyes should be glued to finding the most competitive APR and the most reliable, consistent repayment terms.
Navigating Potential Debt Traps
When life throws a curveball and you’re scrambling for cash, the temptation to snatch the first digital offer is massive. It’s like buying a car without checking the engine just because the paint looks shiny. Slow down for a second and verify the lender’s inquiry method before committing.
Specifically, you need to know if they conduct a hard credit pull. This type of inquiry signals to the rest of the financial world that you are actively hunting for debt. Such a move can paint you as a risky bet, potentially driving up interest rates on any future applications you make.
It’s a slippery slope that can leave your credit score looking bruised. If you aren’t careful, you might find yourself paying a premium just for the privilege of borrowing. Always ask for a “Truth in Lending” disclosure to keep the math honest and transparent.
This specific document is your best friend because it mandates that lenders reveal the exact total cost of your debt. It spells out precisely how much cash will have left your pocket by the time the loan term finally wraps up. Never settle for vague estimates when your wallet is on the line.
Take a long, hard look at the fine print regarding your repayment schedule. You might find some lenders offer a “skip-a-pay” cushion for those unexpected life emergencies, but others are as rigid as a stone wall. Knowing whether you can pause a payment can be a lifesaver in a tight month.
Check the fine print for sneaky late fees or heavy penalties for early repayment. Some companies actually punish you for being responsible and paying the debt off ahead of time. Understanding these nuances acts as a sturdy shield, preventing a quick fix from turning into a lifelong financial anchor.