

Uncategorized @vi
Quickly Secure Bad Credit Loans Maryland Online Today
Quickly Secure Bad Credit Loans Maryland Online Today
Last updated: 2026-10-17
Trying to manage money in Maryland often feels like trekking through a dense mist without a lantern. Life has a funny way of throwing curveballs when you least expect them. An urgent auto fix, an unplanned hospital invoice, or a plumbing disaster can leave you feeling quite underwater.
The weight of these sudden expenses hits hard and fast. Many Marylanders find themselves hunting for a financial lifeline when their credit score fails to tell their whole story. Perhaps a stint without work or a sudden health scare skewed those numbers.
Sometimes, it is just the sheer cost of staying afloat in the Baltimore-Washington area that does the damage. Your credit rating might not reflect your actual integrity or your commitment to paying people back. It is a common struggle in the Old Line State.
Hunting for the perfect lender is hardly a simple task you can finish with a quick thumb-scroll. You have to balance how fast the cash arrives against what it will eventually cost you. It is a delicate dance of math and timing.
You must grasp the fundamental gap between secured loans and unsecured debt. You need to find a company that looks at your real-world circumstances rather than just staring at a three-digit digit on a screen. They should see the person, not just the history.
Whether you live in the busy streets of Baltimore or the quiet parts of Montgomery County, you need to know the local market. Understanding these lending subtleties is your best defense for staying financially upright. Knowledge is your strongest shield here.
We have put together a selection of providers tailored specifically for those facing bumps in the road throughout Maryland. This collection serves as a helpful jumping-off point for anyone looking to patch up a temporary hole in their monthly budget.
- FastLendGo
- MaxCash
- LendingPoint
- OppLoans
- SECU
Our Selection Process for Maryland Financing
When we set out to vet these companies, we didn’t just skim the surface of their websites. Instead, we performed a rigorous investigation into how these services cater specifically to folks living in the Old Line State. Our primary mission was to identify options for people navigating the choppy waters of low or subprime credit scores.
We realized that for a person facing a sudden financial storm, a loan is only helpful if it is actually obtainable. It isn’t simply about getting a quick infusion of cash to keep the lights on. It’s about avoiding those predatory traps where hidden costs or astronomical interest rates turn a small problem into a permanent mountain of debt.
Every single candidate on our list underwent a trial by fire based on four essential pillars. We looked at the math, the clock, the fine print, and the long-term consequences for your financial health.
-
Borrowing Limits: We searched for a versatile spectrum of funds. This meant finding lenders that could cover a tiny $300 emergency or a significant $15,000 sum intended for consolidating various debts.
-
Timeline for Payouts: When an emergency strikes, every second feels like an hour. We measured how quickly lenders move, noting those that offer immediate approvals versus those requiring several days of waiting.
-
Clarity and Terms: Honesty is paramount in this industry. We vetted firms to ensure their digital interfaces are honest, meaning the terms presented online match the actual contract you eventually sign.
-
Influence on Your Score: We favored companies that utilize “soft pull” checks for your initial quote. This allows you to compare various prices without the fear of bruising your FICO score during the shopping process.
| Provider | Funding Range | Payout Velocity | Eligibility Criteria |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Fast access | Bad/Fair/Good Credit |
| MaxCash | $250 – $10,000+ | Minutes | Bad Credit Loans |
| LendingPoint | $1,000 – $36,500 | Fast decision | See site |
| OppLoans | See site | Same-day funding available | Does not affect FICO score |
| SECU | $300 – $30,000 | See site | Unsecured Signature Loans |
Comparing Collateralized and Non-Collateralized Borrowing Options
Before you start scrolling through our curated selection of lenders, you must grasp how your chosen financing actually functions. Within the state of Maryland, most credit providers operate using two main frameworks: secured or unsecured models. Choosing incorrectly could turn a helpful lifeline into a sudden financial nightmare involving your hard-earned property.
Loans Without Collateral
When you opt for an unsecured loan, you aren’t putting up any physical property as a guarantee. Whether you are looking at products from SECU or LendingPoint, the institution is essentially betting on your word and your ability to settle the debt. They aren’t holding your car or your home hostage; they are trusting your fiscal reliability.
Because there is no safety net for the bank, these lenders tend to perform a deep dive into your cash flow and historical banking activity. They want to ensure that your paycheck is consistent enough to cover the installments. It is a bit of a balancing act between their risk and your stability.
If your credit score is currently sitting in the basement but your income is rock solid, an unsecured route is often your best friend. It allows you to bridge a gap without the looming shadow of losing your car or house. It’s a way to borrow money while keeping your assets tucked safely away from creditors.
Loans With Collateral
Secured loans operate on a different philosophy, relying on something you own to act as a shield for the lender. This “something” is known as collateral, and it serves as a fallback plan for the bank. If you decide to use a title loan, like those discussed in the MaxCash segment, your car becomes the hostage in this deal.
Should you hit a rough patch and find yourself unable to make the payments, the lender has the legal green light to take that asset. They will seize your vehicle to make themselves whole and recover their money. It’s a high-stakes game where the prize is your mobility and your property.
For folks with bruised credit scores, these loans are often much easier to snag because the bank’s risk is significantly lower. They have that asset as a backup plan if things go sideways. However, you must be incredibly careful; if your financial situation doesn’t turn around quickly, you might end up losing something vital.
Top-Rated Maryland Financing for Varying Credit Scores
1. FastLendGo
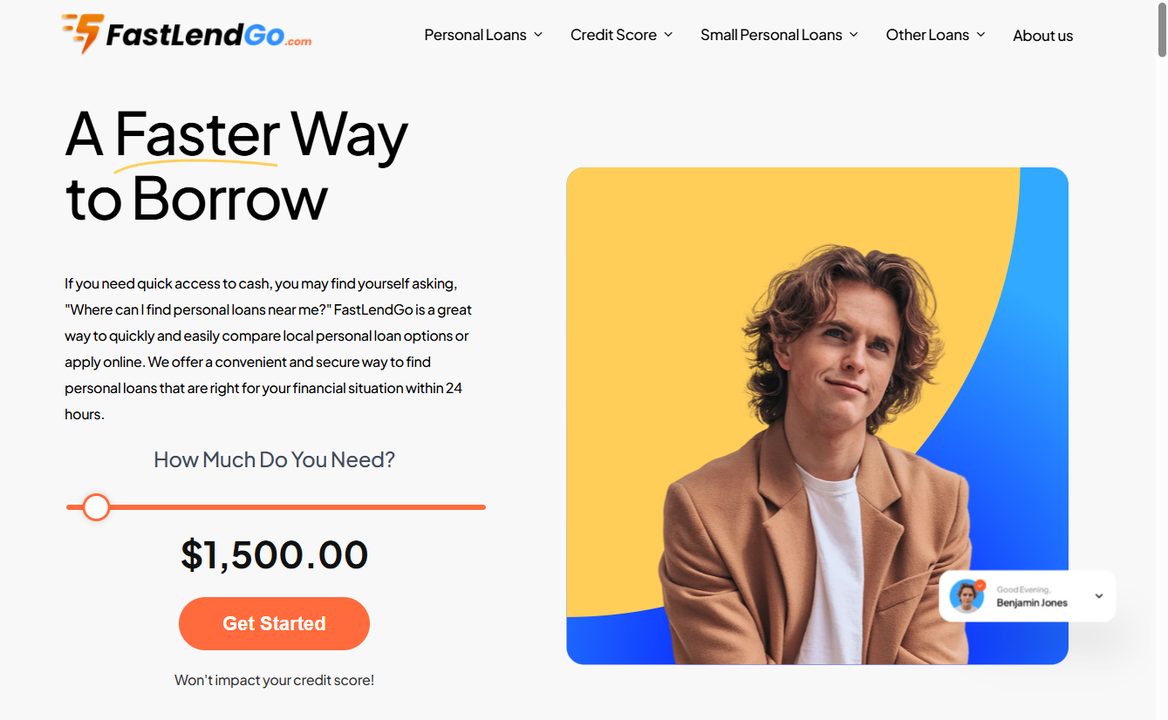
Think of FastLendGo as a digital navigator for those searching for local borrowing alternatives. It functions as a bridge, helping you survey various personal loan possibilities quickly. Life happens fast, and sometimes you need cash immediately.
Whether you are staring at an unexpected car repair bill or a sudden trip to the dentist, this platform is built for speed. It bypasses the endless red tape that usually plagues massive national banks. You can find what you need at fastlendgo.com.
The service accommodates many different financial needs, from a small $500 boost to larger sums of $5,000. Because they scan a wide array of options, they can often uncover a match that a standard bank might miss. This makes them a versatile ally for Marylanders.
Pros:
- Provides funds for dental or auto needs.
- Serves a diverse range of credit profiles.
- Makes comparing local rates effortless.
Cons:
- Specific interest percentages are not listed upfront.
2. MaxCash
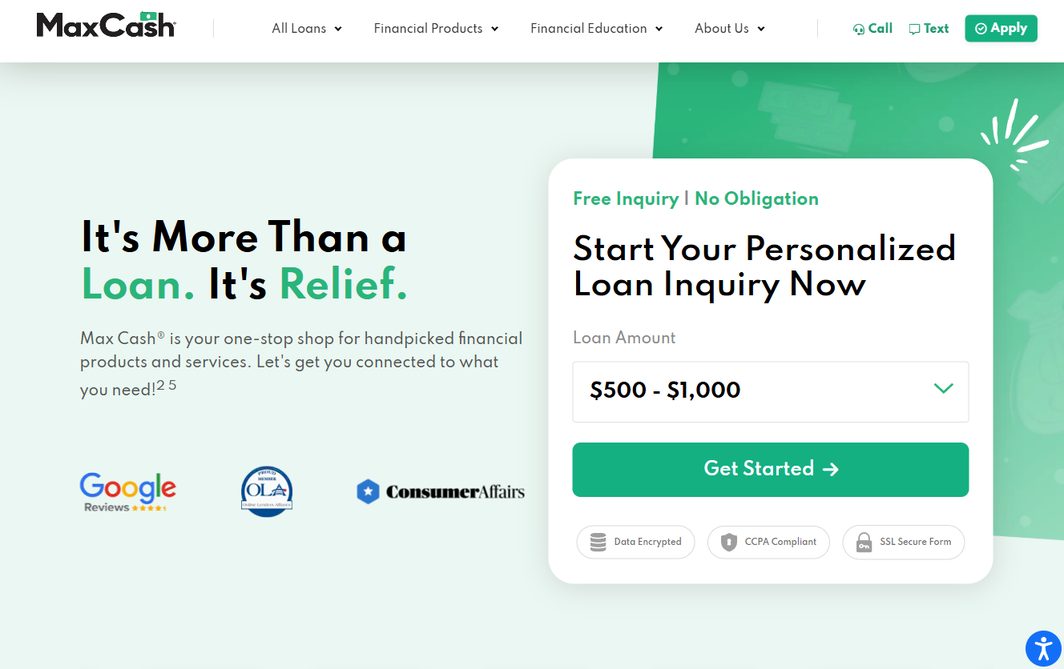
MaxCash aims to be much more than a simple money source; it wants to be your financial lifeline. For Maryland residents facing a crisis, such as a looming utility shut-off or an urgent home fix, this service is a lifesaver. It offers installment or title loans in just a few minutes.
The platform is optimized for velocity, making it a top choice when you need to plug a sudden hole in your cash flow. It is designed to provide immediate relief rather than making you wait days for a bank transfer.
You can borrow as little as $250 or as much as over $10,000. This wide range makes it a veritable “one-stop shop” for almost any financial situation. If you need a quick cash advance to reach your next payday, this is a major contender.
Pros:
- Processing is lightning fast, often within minutes.
- Title loans offer very high maximum limits.
- A broad selection of loan products exists.
Cons:
- Title loans require your car as collateral.
3. LendingPoint
LendingPoint is geared toward those looking to unlock substantial capital for bigger life moves. With borrowing limits reaching up to $36,500, this is a powerhouse for anyone considering major home upgrades. It is a robust option for serious financial goals.
If you are currently juggling several high-interest credit card debts, this provider can help you consolidate. Using a larger loan to restructure your debt can be a smart move to protect your monthly budget and long-term stability.
The digital experience is smooth, allowing you to check your potential rates without any damage to your credit score. This “soft pull” method is a blessing for shoppers. It is perfect for those who need professional, streamlined service for significant expenses.
Pros:
- Large loan ceilings for major costs.
- Checking rates won’t hurt your credit score.
- Covers a vast array of loan uses.
Cons:
- Likely requires better credit than specialty lenders.
4. OppLoans
OppLoans operates on the philosophy that a single number doesn’t define your entire financial history. By collaborating with various bank partners, they offer personal loans that look at the bigger picture. This is vital if a recent score dip has caused you to be rejected elsewhere.
They act as a supportive safety net for people who feel ignored by rigid, automated bank models. If a furnace breaks during a freezing Maryland winter, the ability to receive same-day funding is a total game-changer for your household.
The application is designed to be a breeze, requiring very little paperwork to get started. It is a streamlined way to find help when you are facing a sudden, urgent crisis.
Pros:
- Approved users can access same-day funding.
- Applying does not impact your FICO score.
- Advertised processes contain no hidden fees.
Cons:
- Approval results are unpredictable beyond credit scores.
5. SECU
As the biggest state-chartered credit union in Maryland, SECU offers a traditional, community-centric banking approach. Their unsecured signature loans are excellent for those wanting to build lasting ties with a local institution. They focus heavily on member success.
Because they are member-owned, SECU provides a level of personalized service that big national banks often lack. It is a refreshing alternative for those tired of the predatory tactics often seen in the high-interest lending market.
You can borrow between $300 and $30,000 without worrying about prepayment penalties or application fees. If you get a surprise bonus or a tax refund, you can pay them back early without being charged extra interest. That kind of flexibility is hard to find.
Pros:
- No penalties for paying off loans early.
- High limits for unsecured loan products.
- Deeply rooted within the Maryland community.
Cons:
- Membership requirements may need to be met.
Evaluating Your Financing Options
Picking a provider shouldn’t be a shot in the dark. Before you put pen to paper, scrutinize the nitty-gritty details of the contract. While the rush of a fast approval feels great, you might find yourself paying a heavy price for that speed if you skip your homework.
Don’t let a tiny monthly installment fool you into a false sense of security. A smaller check every month typically indicates a much longer repayment window, which ultimately drives your total interest costs through the roof. It is a classic trap that can drain your wallet over time.
Consider this mathematical reality. A $2,000 loan featuring a $100 monthly payment over 36 months ends up costing much more than a $2,000 loan with a $200 monthly payment over 12 months. Always tally the entire sum of your installments to find the actual price tag before you sign away your money.
Matching a lender’s services to your immediate crisis is also vital. If you are facing an eviction and need cash immediately, a traditional credit union might be too sluggish for your emergency, despite their superior interest rates. Speed is often the name of the game in a crisis.
On the flip side, if your objective is debt consolidation, a quick cash advance provider is the wrong tool for the job. Seeking $20,000 to manage your existing debt from a high-interest lender could end up digging a much deeper hole for your finances. You need a strategy, not just a quick fix.
Finally, treat any promise of “guaranteed approval” with extreme skepticism. In the real world, legitimate companies are legally required to verify that you can actually pay them back to follow consumer protection regulations. If someone claims they never turn a borrower down, walk away immediately.
Such claims are often a massive red flag for predatory actors or outright scams. It is better to stick with established companies that are transparent about their requirements. Choose a partner that prioritizes your long-term stability while you weather these financial storms.