

Uncategorized @vi
Top-Rated Bad Credit Loans New Jersey: Secure Fast Funding Online Today
Top-Rated Bad Credit Loans New Jersey: Secure Fast Funding Online Today
Last updated: 2026-10-16
Life has a way of throwing curveballs when you least expect them. An unexpected trip to the mechanic or a sudden hospital invoice can feel like a heavy weight on your shoulders. For many people living across the Garden State, these financial hiccups arrive without warning, leaving them staring down a mountain of unpaid bills.
It is vital to find a creditor who prioritizes your actual ability to repay over just looking at a numeric rating. If you find yourself in a pinch, you need a partner who understands your real-world situation rather than one that shuts the door based on a single number.
Perhaps your vehicle is acting up in Newark, or maybe a dental emergency has left you reeling in Jersey City. In these high-pressure moments, it is easy to lose your focus. You might feel like you must grab any offer in sight just to put out the fire, but acting on impulse often results in a much bigger wildfire later.
Navigating the crowded marketplace of lenders is like sailing through a storm; you need a clear map and a steady hand. Some firms are lightning-fast with cash but demand a hefty price for that speed. Conversely, local banks might provide more security, though they tend to move at a snail’s pace when you are in a hurry.
Our curated selection aims to bridge that gap. We have searched for reliable options specifically for borrowers with imperfect credit histories who want to maintain their financial dignity. It is about finding that sweet spot where accessibility meets sensible terms.
Please remember that a high-interest installment loan is not the same thing as a medical payment arrangement. Picking the wrong path can transform a minor stumble into a permanent spiral of debt. Take a breath and review these alternatives thoroughly before you put pen to paper.
- Max Cash
- FastLendGo
- XCEL Federal Credit Union
- Fulton Bank
- Loanz
- Cherry
- CareCredit
Comparing Borrowing Alternatives Across the Garden State
Finding the right lending partner for your unique circumstances involves weighing several vital factors. Most people facing an urgent crisis prioritize how quickly they can access funds. If you rely on a car for your daily commute in New Jersey, waiting several days for a bank approval could be a total dealbreaker.
However, the long-term price tag on your borrowed capital is what truly determines your financial health. It is essential to scrutinize interest percentages and those sneaky, hidden service charges. A rapid cash injection is of little help if high rates end up eating up your entire monthly salary.
We also investigated the level of flexibility available to those with less-than-perfect credit histories. Some companies offer title loans if you lack traditional collateral, while others focus specifically on medical-related financing. You might find solutions ranging from a tiny $250 cash advance to a substantial $60,000 signature loan.
Our analysis looked at whether a lender prioritizes your monthly earnings or your specific credit rating. Generally, your actual ability to repay—determined by your current employment and steady income—is a much more reliable indicator of future stability than any single number on a credit report.
| Company Name | Funding Ranges | Processing Speed | Credit Standards |
|---|---|---|---|
| Max Cash | $250 – $10,000+ | Minutes | Bad Credit Options |
| FastLendGo | Small Loans Available | Quick Access | Bad Credit/No Credit |
| XCEL Federal Credit Union | $500 – $60,000 | See Site | Secured/Unsecured |
| Fulton Bank | See Site | See Site | See Site |
| Loanz | $100 – $10,000 | Quick/Convenient | See Site |
| Cherry | See Site | Instant Approval | High Approval Rate |
| CareCredit | See Site | Instant Decisions | Subject to Credit |
1. Max Cash
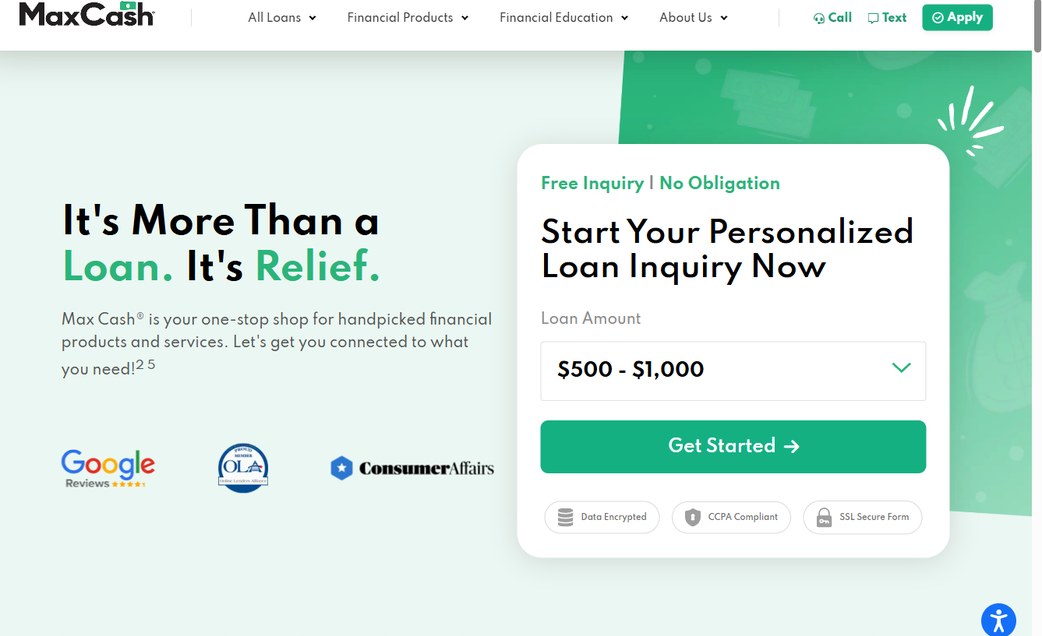
Max Cash serves as a versatile destination for many different financial requirements. Their product line spans from minor $250 advances up to larger loans exceeding $10,000. This makes them a dependable option if you need immediate relief from a surprise expense. A $500 loan might mend a broken household appliance, whereas larger amounts assist with vehicle or residential repairs.
This platform is engineered for extreme velocity. They cater to individuals seeking installment or title loans in a matter of minutes. Since they work with people who have bad credit, they provide a vital lifeline that major banks typically refuse to offer. Just remember that rapid funding often comes with the trade-off of higher interest rates.
Pros:
- Incredibly rapid processing for time-sensitive emergencies.
- A diverse array of loan varieties, including title options.
- Accessible for individuals with bad credit.
Cons:
- Title loans involve using collateral, which puts your vehicle at risk.
2. FastLendGo
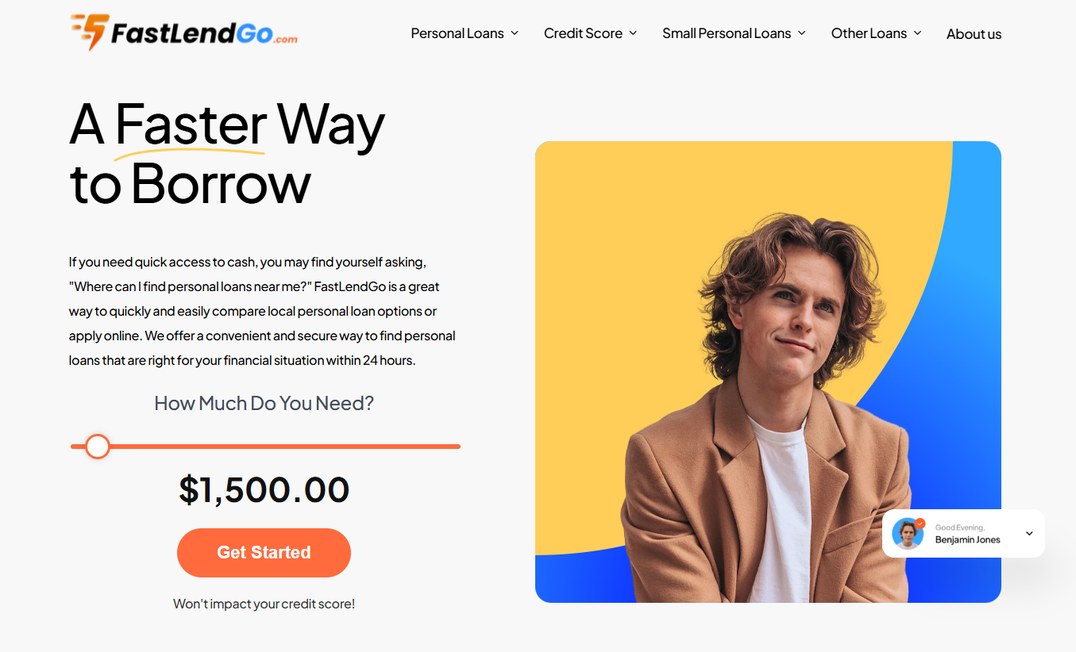
FastLendGo provides a flexible path for personal financing needs. They cater to all credit tiers, whether your history is excellent, fair, or poor. It is an efficient way to shop for local alternatives without having to physically visit various bank branches. (fastlendgo.com)
This lender is an ideal fit for specific life events, such as dental procedures or fixing a car. If you are hunting for personal loans nearby, their digital framework simplifies that entire search. They aggregate various profiles to help align your specific credit score with a provider that is actually willing to review your application.
Pros:
- Assists with many life costs, such as roofing or dental work.
- Available options for those lacking credit history.
- User-friendly online comparison mechanism.
Cons:
- Primarily acts as an online comparison service rather than a direct lender.
3. XCEL Federal Credit Union
If you desire more traditional financial stability, XCEL Federal Credit Union provides both secured and signature loans. Their funding amounts can climb as high as $60,000, offering a substantial safety net for significant life shifts. You could apply these funds toward home improvements, debt consolidation, or unexpected medical bills.
As a credit union, their approach feels much more community-centric than predatory lenders. Because credit unions are owned by their members instead of shareholders, they often deliver a more personalized level of service. You can choose between unsecured or secured loans to match your specific situation. Using a savings account as collateral can frequently unlock much lower interest rates.
Pros:
- Substantial maximum loan limits reaching $60,000.
- Offers secured loan paths to secure better rates.
- Service model focused on the member.
Cons:
- Likely necessitates membership or specific eligibility criteria.
4. Fulton Bank
Fulton Bank represents a major establishment for residents of New Jersey. They possess the power of a large institution while still maintaining a local presence. This makes them a reliable partner for long-term banking and managing intricate financial requirements over the course of several years.
Their services range from commercial banking to personal accounts. They might not be your first choice for a quick $200 emergency, but they are phenomenal for managing significant investments or large wealth portfolios. Their long-standing stability is a major benefit if you want a lender that will still be operating decades from now.
Pros:
- Extremely secure and backed by FDIC insurance.
- Extensive banking services, from personal to commercial levels.
- A robust presence within the New Jersey market.
Cons:
- May enforce stricter requirements than specialized bad credit lenders.
5. Loanz
Loanz concentrates on helping you organize your financial future through tailored loan solutions. With amounts spanning from $100 to $10,000, they are a great option for smaller tasks like weddings, moving, or debt consolidation. This helps you tackle minor financial hurdles before they snowball into massive, unmanageable debts.
The primary objective here is helping you reclaim control of your finances. Their specific debt consolidation products help you manage multiple outstanding bills at once. Instead of juggling five different monthly due dates, you can merge them into one single payment to streamline your budget and reduce interest-related stress.
Pros:
- Low entry point for small loans starting at just $100.
- Dedicated products designed for debt consolidation.
- Seamless digital transaction capabilities.
Cons:
- Loan caps are limited to a relatively modest $10,000.
6. Cherry
Cherry is a specialist working within the retail and healthcare finance space. They boast an impressive 90% approval rate and are utilized by thousands of different providers. Their core mission is to allow you to receive necessary medical or retail services immediately and pay for them over time, removing the barrier of high upfront costs.
The process for applying is incredibly swift, frequently taking merely 35 seconds. This makes them a top choice for individuals requiring immediate dental work or home repairs who prefer to spread out their expenses. Cherry integrates directly through your chosen service provider to make the entire experience easy.
Pros:
- Incredibly rapid application procedure.
- High consumer approval rates.
- Seamless integration with many healthcare providers.
Cons:
- Restricted to specific providers and merchants.
7. CareCredit
CareCredit is a specialized credit card designed for the health and wellness sector. It is widely accepted at over 285,000 different locations, making it a highly versatile tool for medical costs. You can use it for dental visits, vision care, or even veterinary expenses for your pets.
You can perform a prequalification check without causing any damage to your credit score. This is a vital feature if you are concerned about your rating while shopping for medical options. While many plans offer deals like “no interest if paid in full,” be cautious—missing a payment deadline can trigger retroactive interest charges.
Pros:
- Pre-qualifying does not impact your credit score.
- Extremely large network of participating locations.
- Flexible financing options for wellness and health.
Cons:
- Subject to specific terms and credit approval.
Distinguishing Between Collateralized and Non-Collateralized Borrowing
Before jumping into a loan application, it is vital to grasp whether you are looking at a secured or unsecured arrangement. This single distinction shifts your entire risk profile. When a loan is secured, it is tethered to a valuable asset, such as your residence, vehicle, or even a personal savings account.
Because the lender holds a legal claim to that property if you fall behind on payments, they tend to be much more flexible. This makes secured options quite attractive for those navigating life with a lower credit score. It is essentially a way to build trust through tangible proof of value.
While these protected loans frequently offer more favorable interest rates, the stakes for your personal belongings are considerably higher. For instance, if you neglect the terms of a title loan, your car could be repossessed. You are essentially making a calculated gamble, weighing cheaper monthly costs against the potential loss of your property.
On the other hand, unsecured loans do not rely on any physical collateral to guarantee the debt. Most standard credit cards and personal loans operate under this specific framework. Since a bank cannot simply seize your car if you default, they typically demand much higher interest rates to offset their danger.
Furthermore, these lenders usually expect to see a much stronger credit history before they even consider an application. If you run into financial trouble and stop paying, they cannot instantly take your home. However, they still have teeth; they can pursue legal action or even garnish your wages to recover what is owed.
Getting Ready to Apply for Financing
Walking into a lending office without a strategy is like sailing into a storm without a compass. You might find yourself adrift if you aren’t prepared. By following a structured roadmap, you can boost your approval odds and secure more favorable terms.
It is vital to protect your credit standing throughout this process. Many applicants inadvertently damage their scores by making too many inquiries or failing to clean up their records. A little bit of homework now saves a massive headache later.
Think of this period as the “pre-flight check” for your financial future. If you miss a single step, the whole engine might sputter. Let’s dive into the specific tasks you need to tackle before you hit the submit button on that application.
- Double-Check Your Paperwork: Before you dive in, make sure your latest pay slips, banking history, and identification are all gathered in one place. If you plan to use any property as collateral for the loan, ensure you have the legal ownership papers ready to go.
- Evaluate Your Debt-to-Income (DTI) Ratio: Financial institutions scrutinize how much of your monthly paycheck is already spoken for by existing liabilities. If your debt load is too heavy, they might walk away. Consider wiping out some small credit card balances to lower that number first.
- Scrutinize Your Credit File: Even a single misplaced “late” mark can act like an anchor on your credit score. Don’t let a clerical error sabotage your dreams. Utilize a complimentary service to hunt down inaccuracies and file disputes before seeking any new funding.
- Compare APRs, Not Just Interest Rates: Don’t let a low interest rate fool you; it’s often a siren song. The Annual Percentage Rate (APR) incorporates both interest and compulsory costs, representing the true price of your loan. A 10% interest rate paired with a $500 fee can actually be pricier than a 12% rate with zero extra charges.
- Leverage Prequalification Features: Seek out lenders that perform “soft pulls” on your file. This clever method allows you to shop around and view estimated rates without leaving a permanent scar on your credit history. It is a much safer way to gauge your options.
Steering Clear of Costly Money Traps
Finding a creditor shouldn’t be a race to see who hands over the most digits the fastest. You absolutely must scrutinize the tiny text before signing anything. Many folks find themselves caught in a whirlpool of debt because they rushed into a high-interest agreement just to solve an immediate problem.
Suddenly, you realize the cumulative interest ends up being a mountain of cash, far exceeding your initial borrowing amount. It is like trying to put out a fire with gasoline if you aren’t careful. Always keep your eyes peeled for the total debt burden rather than focusing on a single monthly installment.
A tiny monthly bill can be a wolf in sheep’s clothing, masking a repayment period that stretches on for ages. Imagine a $5,000 loan where you only pay $100 each month. It sounds like a breeze, but you might be stuck in that cycle for seven long years.
Smart Application Strategies
Another blunder to dodge is hammering out too many loan requests in a single window of time. Every time a lender checks your credit, they initiate a “hard inquiry,” which can ding your score. If you bombard five different banks within seven days, you look like you’re drowning in red ink.
Lenders view that kind of frantic activity as a sign of financial instability or desperation. Instead of flying blind, utilize prequalification instruments to filter your options. This allows you to scout the field without leaving a trail of bruised credit scores in your wake.
By narrowing down your list through these preliminary checks, you protect your standing. It is much better to be selective than to let your credit profile take a hit from multiple failed or unnecessary attempts. Patience truly is a virtue when navigating the complexities of modern lending.