

Uncategorized @vi
Top Rated Personal Loans in Lubbock TX: Compare Local Rates Now
Top Rated Personal Loans in Lubbock TX: Compare Local Rates Now
Last updated: 2026-10-16
Navigating your bank account in Lubbock can feel like steering through a thick West Texas dust storm. You are eager to make progress, yet the fine print regarding interest and repayment terms often stays hidden in the haze. Securing a loan shouldn’t just be about a quick injection of funds.
Instead, it is about selecting a route that keeps you on solid ground for the long haul. Whether you are facing a surprise hospital invoice or finally mending a damaged roof, your chosen lender will dictate your peace of mind for the coming months.
Our curated list emphasizes diversity in lending options. We want to make sure that everyone finds a suitable match, regardless of their situation. Whether your credit history is flawless or has a few unexpected bumps along the way, there is a viable solution here for you.
We vetted these specific companies by studying their actual performance for residents throughout the South Plains. Our team scrutinized both their online portals and their physical storefronts. We wanted to see how they address the varied requirements of our local neighbors.
Some folks prefer a local branch where they can speak to someone face-to-face. Others would much rather manage their entire application via a smartphone while relaxing at a Broadway coffee shop. Our evaluation ensures you have options that fit your lifestyle.
- FastLendGo
- Midwest Finance
- Discover
- Max Cash
- United Credit
- XCEL Federal Credit Union
- Farm Credit
Comparing Local Financing Choices in the South Plains
Our methodology for this comparison involved scrutinizing how these organizations actually treat people living in Lubbock. We looked far beyond who offers the largest checks. We prioritized stability above all else.
Every factor, from total loan amounts to the complexity of applying, was put under the microscope. We wanted to identify the specific niches each entity fills to ensure our readers find a perfect match for their unique lifestyle.
We dug deep into the annoying hurdles that often plague loan seekers. We tracked how many papers you’ll need to shuffle, the waiting period for verification, and whether you’ll be stuck sitting in a physical branch. Some lenders cater to high earners, while others are lifelines for those facing a sudden crisis.
Our goal is to provide a roadmap for everyone, whether you are a student at Tech or a business titan in the Panhandle. A college kid needing a quick loan for textbooks has needs that look nothing like a rancher in Brownfield trying to upgrade irrigation gear. You need the right tool for the job.
| Provider | Borrowing Limits | Credit Standards | Speed of Funds |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Bad to Great Credit | See site |
| Midwest Finance | See site | See site | See site |
| Discover | See site | See site | See site |
| Max Cash | $250 – $10,000+ | Bad Credit Available | In minutes |
| United Credit | See site | See site | 24-hour online app |
| XCEL Federal Credit Union | See site | See site | See site |
| Farm Credit | See site | See site | See site |
1. FastLendGo
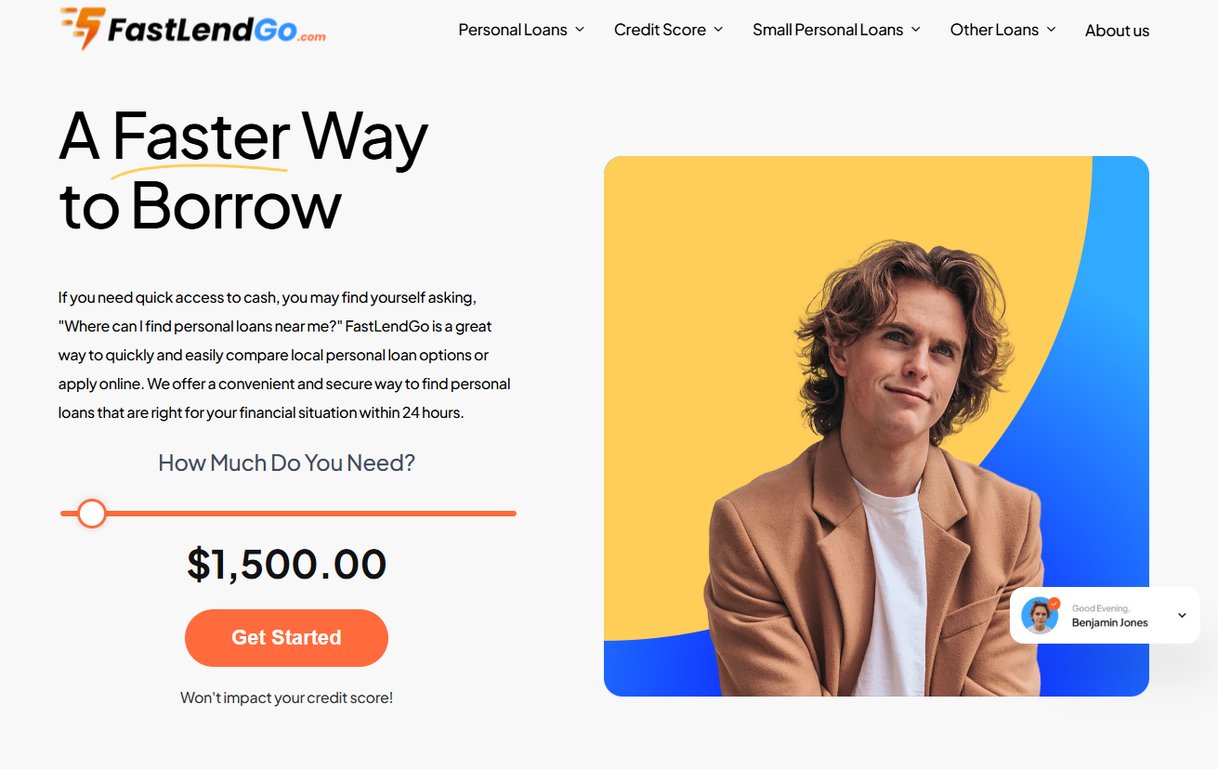
If you are hunting for different financial paths without wasting time, FastLendGo is a highly flexible player. They specialize in serving a massive spectrum of credit profiles. They don’t just ignore those with less-than-perfect scores.
You might secure a modest $500 for an emergency or much larger sums for life’s big milestones. This makes them a great middle-ground option for many people in the Lubbock area. They exist right in the sweet spot between rigid banks and predatory lenders. (fastlendgo.com)
They shine when you have a specific headache like car repairs or unexpected dental bills. Instead of wandering from one bank to another, use their system to find a match. If your car breaks down on Loop 289, their quick matching can stop you from falling into a debt hole by finding a targeted auto repair solution.
Pros:
- Accommodates everything from poor to excellent credit scores.
- Dedicated loan categories for dental and automotive needs.
- Suited for both high earners and those borrowing for the first time.
Cons:
- The fast-paced decision model might feel a bit rushed.
2. Midwest Finance
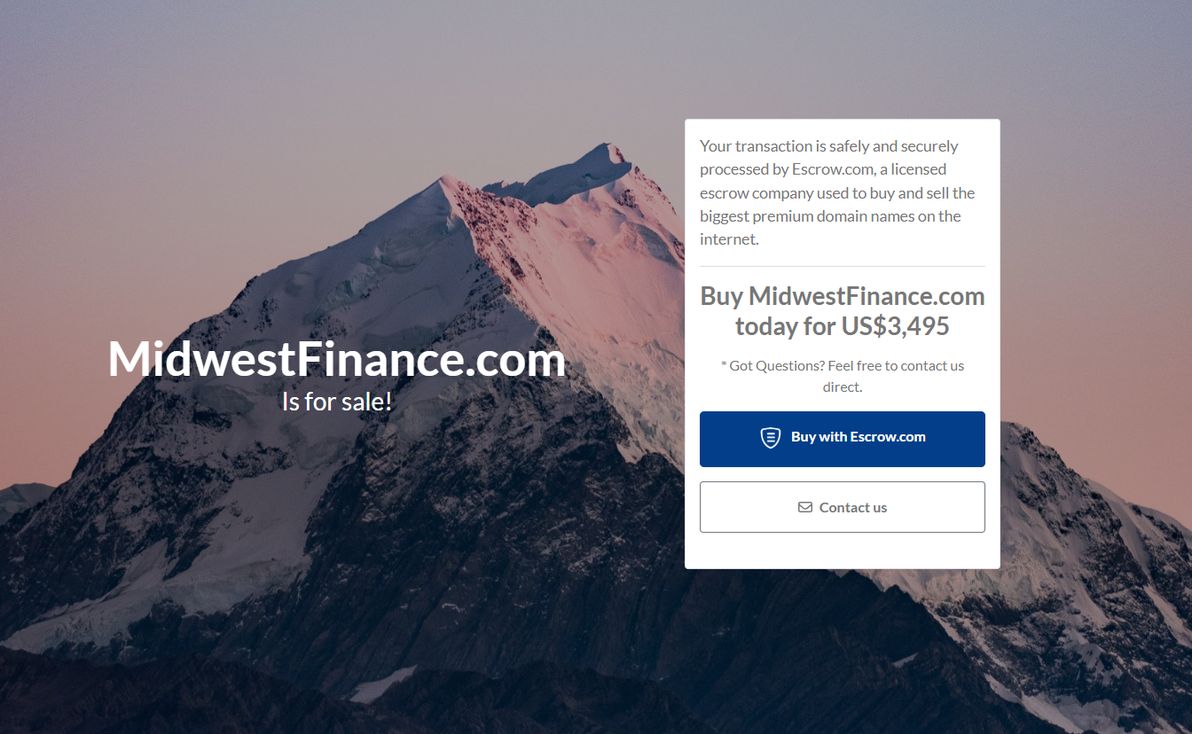
Midwest Finance is less of a traditional lender and more of a specialized digital entity in this comparison. They represent a unique asset for people interested in the business of digital real estate. This is a far cry from a standard loan for groceries.
In a world where domain names carry massive weight, this company operates in a very narrow niche. It does not function like a typical personal loan service. If you’re looking to borrow cash for a new truck, you won’t find what you need here.
They focus on the inherent value of the brand itself within the financial world. It is vital to know the difference between a “lender” and a “financial asset entity” when browsing the web. Don’t mistake a brand name for a retail storefront.
Pros:
- Possesses a high-value, recognizable brand.
- Transactions are secured through Escrow.com.
Cons:
- Not designed to provide personal loans to consumers.
3. Discover
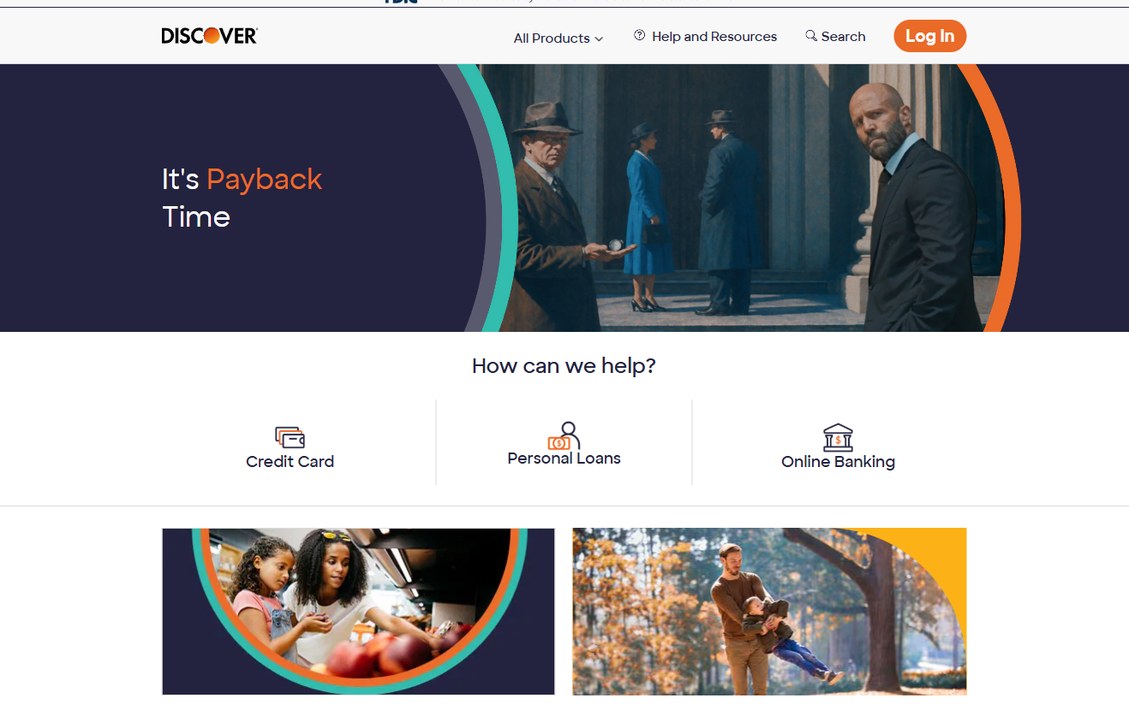
Discover is a giant in the national landscape. They are famous for delivering top-tier security and a sense of reliability. Since they are FDIC-insured, they offer a level of certainty that small, boutique lenders simply cannot touch.
As a massive organization, their assessment algorithms are incredibly advanced. They look well beyond a simple FICO number. They might peek at your transaction history and how you handle payments to truly understand your reliability as a borrower.
Their edge comes from massive acceptance and perks like cash back. If you want a lifelong banking partner, their ecosystem is built to expand as your credit improves. A person might start with a simple card and eventually graduate to much larger lines of credit.
Pros:
- Extremely reputable and widely accepted everywhere.
- Provides rewards like cash back on specific spending.
- Pre-approval checks won’t hurt your credit score.
Cons:
- Eligibility may be tougher than specialized subprime lenders.
4. Max Cash
When an urgent expense hits and the clock is ticking, Max Cash enters the arena. They focus heavily on accessibility and speed, providing products like title loans and installment loans. They are a one-stop shop for instant liquidity during a crisis.
Their entire business model is built for the “right now.” Think about a burst water heater or a medical bill that won’t wait two weeks for a bank’s approval. You can find amounts ranging from a $250 starter to over $10,000.
They are the go-to for people who need more than a small advance but can’t wait for a traditional bank’s slow process. Just keep in mind that speed has a cost. That “in minutes” funding is the trade-off for interest rates that are higher than secured bank options.
Pros:
- The inquiry process is lightning fast.
- Provides a wide range of funds from $250 to $10,000+.
- Covers many needs, including car title financing.
Cons:
- Rapid funding often carries higher interest rates.
5. United Credit
United Credit serves as a bridge, linking customers to various retailers and payment methods. They prioritize the idea of “personal well-being,” trying to tie lending directly to what consumers actually need. Their 24-hour digital application is a lifesaver for busy locals.
If your work schedule is irregular, you might never make it to a physical bank during their hours. They focus on longevity by maintaining ties with many different lenders. They aren’t just one isolated company.
Think of them as a centralized hub that simplifies your search. Instead of you doing the heavy lifting of calling five different places, they help you access various financing tools tailored to specific retail needs. They handle the hard work of comparison.
Pros:
- Online applications are available 24/7.
- Provides diverse options through a network of lenders.
- Focuses heavily on the merchant-consumer connection.
Cons:
- Using multiple lenders can make final terms harder to predict.
6. XCEL Federal Credit Union
For those craving a community-centric feel, XCEL Federal Credit Union offers a different vibe. Being a credit union means they are member-focused. This usually results in a much more personal touch than those giant national banks.
Since they are cooperatives owned by members, the goal is to serve the community rather than just maximize profit. They offer standard savings, checking, and loan products that are often more competitive than the big-box alternatives.
They place a massive emphasis on fraud prevention and security, which is vital today. For someone in Lubbock, this means having a partner that truly understands the local economy. They offer community stability, not just a digital banking app.
Pros:
- Member-owned with a focus on the community.
- Strong commitment to security and fraud education.
- Provides a complete suite of banking products.
Cons:
- You may need to meet specific membership criteria.
7. Farm Credit
Farm Credit is a specialized powerhouse built for the true engine of Texas: agriculture. They are a massive network of cooperatives that grasp the seasonal cash flow struggles unique to farmers and ranchers. They know money doesn’t always arrive in a straight line in the rural world.
Unlike standard personal loans, agricultural lending requires understanding livestock valuation, land appraisal, and crop cycles. These are nuances that a typical city lender often misses. They serve everyone from small families to huge agribusinesses.
If your finances are tied to the land, they provide an expertise a standard bank can’t touch. This might involve financing for heavy machinery, seed costs, or even mortgages for those living on the outskirts of Lubbock. They understand the rural way of life.
Pros:
- Unmatched expertise in the rural and agricultural sectors.
- Access to a massive network of cooperatives.
- Specifically tailored for rural producers and their families.
Cons:
- Highly specialized and might not fit non-rural needs.
Unmasking the Actual Price Tag of Your Debt
Before ink meets paper on a contract, you have to distinguish between your monthly installment and the APR (Annual Percentage Rate). It is a classic magician’s trick where lenders highlight a small monthly bill to make the debt look bite-sized. Yet, stretching those payments over a massive timeframe can lead to paying back twice or even three times the initial principal in interest alone.
Imagine you borrow $5,000 and your bank says you only owe $200 each month. That sounds like a walk in the park, right? However, if that arrangement stretches across 48 months, you have actually shelled out $9,600 to cover that single $5,000 loan. You must always run the math on the full repayment total. It is the only figure that reveals the real weight of your obligation.
Watch out for these three common traps that can catch you off guard:
- Early Payoff Charges: Certain institutions hit you with a penalty if you attempt to settle your debt ahead of schedule. If you are banking on a sudden windfall, such as a tax refund, to wipe the slate clean, verify that your lender doesn’t punish you for being proactive.
- Floating versus Locked Rates: A variable rate might look enticing at the start, but it is a moving target. If national interest rates climb, your monthly obligation will climb right along with them. For anyone looking at long-term borrowing, a fixed rate provides much-needed stability and peace of mind.
- The Sneaky Extras: Keep a sharp eye out for origination fees, costs to apply, or penalties for late payments. These hidden line items can throw a wrench into your financial calculations and change the entire math of your borrowing plan.
Finding the Right Lender in Lubbock
Picking a financial partner is a lot like selecting a car for a long haul; you have to ensure the engine can handle your specific route. If your credit score is stellar and you crave perks, a large national bank might be your primary destination. On the other hand, if you are facing an immediate crisis and need funds by tomorrow, a niche provider like Max Cash might be the lifeline that keeps your house running.
Finding a singular “ideal” lender is a bit of a wild goose chase. Instead, you should seek the institution that aligns perfectly with your present bank balance and your future aspirations. It is easy to get caught up in the allure of a low monthly installment. However, the real sting comes from the aggregate cost of your debt, specifically the interest rates and various service fees.
Before putting pen to paper, demand a clear breakdown of the complete sum you will eventually pay back. You should never take out a loan that exceeds what your paycheck can support without causing immense anxiety. At the end of the day, a smart loan acts as a bridge over a puddle rather than a flood that washes your finances away.