

Uncategorized @vi
Get a 550 credit score personal loan: Fast approvals for bad credit.
Get a 550 credit score personal loan: Fast approvals for bad credit.
Last updated: 2026-10-16
Navigating your finances while stuck with a 550 credit score can feel like trying to run a marathon through a swamp. It is an exhausting struggle, particularly when life decides to throw a wrench in your plans. One minute you are fine, and the next, a sudden mechanical failure in your car or a sudden trip to the dentist leaves you empty-handed.
Medical emergencies or unexpected bills often strike precisely when your savings are at their thinnest. These sudden financial hits can leave you feeling like you are drowning in a sea of red ink. It is a heavy burden to carry when your wallet simply cannot keep up with the demands of daily life.
Most major banks act like gatekeepers, often viewing a 550 rating as an immediate reason to say no. They tend to shut their doors rather than take a chance on anyone outside the elite credit tiers. However, you are far from out of options if you know where to look for help.
A handful of niche lenders actually keep their lights on for people in your situation. These specialists don’t just obsess over your FICO number; they dig a little deeper into your personal history. They might look at how steady your paycheck is or examine your previous banking patterns to determine your reliability.
Scouring the market for a financial lifeline involves more than just checking the interest percentage. You must carefully balance the speed of the payout against the ultimate price of the loan. It is a delicate dance between immediate relief and long-term stability that requires careful thought.
Some borrowers prioritize finding the lowest APR possible to minimize what they owe in the long run. Conversely, others are in a race against the clock, needing funds in their bank account within 24 hours. For those facing a looming eviction or a penalty fee, speed is the only thing that matters.
We have compiled a selection of the most dependable lenders for those currently navigating the fair to poor credit landscape. This guide aims to clarify your choices during these high-pressure moments when quick assistance is vital. We hope these insights help you steer your way out of the storm.
- LendingPoint
- FastLendGo
- Max Cash
- Avant
- Reprise
Our Selection Methodology
Sifting through lenders when your credit is hovering around 550 requires more than just reading catchy advertisements. We look deep beneath the surface-level promises to determine if a company truly provides a path to liquidity for those with less-than-perfect history. It isn’t simply about finding a door that is unlocked; it’s about ensuring the terms behind that door aren’t designed to trap you.
Some companies promise high approval rates like they are handing out candy, yet they hide predatory penalties or sneaky service costs in the fine print. You wouldn’t buy a car without checking the engine, so why should your debt be any different? We believe you deserve a clear view of your financial obligations before you sign on the dotted line.
Our team specifically targeted lenders that cater to the 550 credit bracket. We evaluated them through a three-pronged lens: accessibility, speed of delivery, and overall transparency. We scrutinized how quickly money hits your bank, how honest they are regarding the total loan volume, and the breadth of their available products. Every name on our list was vetted to ensure they offer genuine help for those in a pinch.
We also put their mobile technology to the test. When an emergency strikes, you shouldn’t be tethered to a desktop computer. You need to be able to finish your paperwork on a smartphone while waiting in line or commuting. A clunky, frustrating interface is the last thing you need when time is a luxury you don’t have.
| Company | Funding Range | Credit Minimums | Speed of Cash |
|---|---|---|---|
| LendingPoint | $1,000 – $36,500 | Fair Credit | Fast Funding |
| FastLendGo | $500 – $5,000+ | Bad/Fair Credit | Quick Access |
| Max Cash | $250 – $10,000+ | Bad Credit | In Minutes |
| Avant | See site | 550 and above | Fast Funding |
| Reprise | See site | See site | See site |
1. LendingPoint
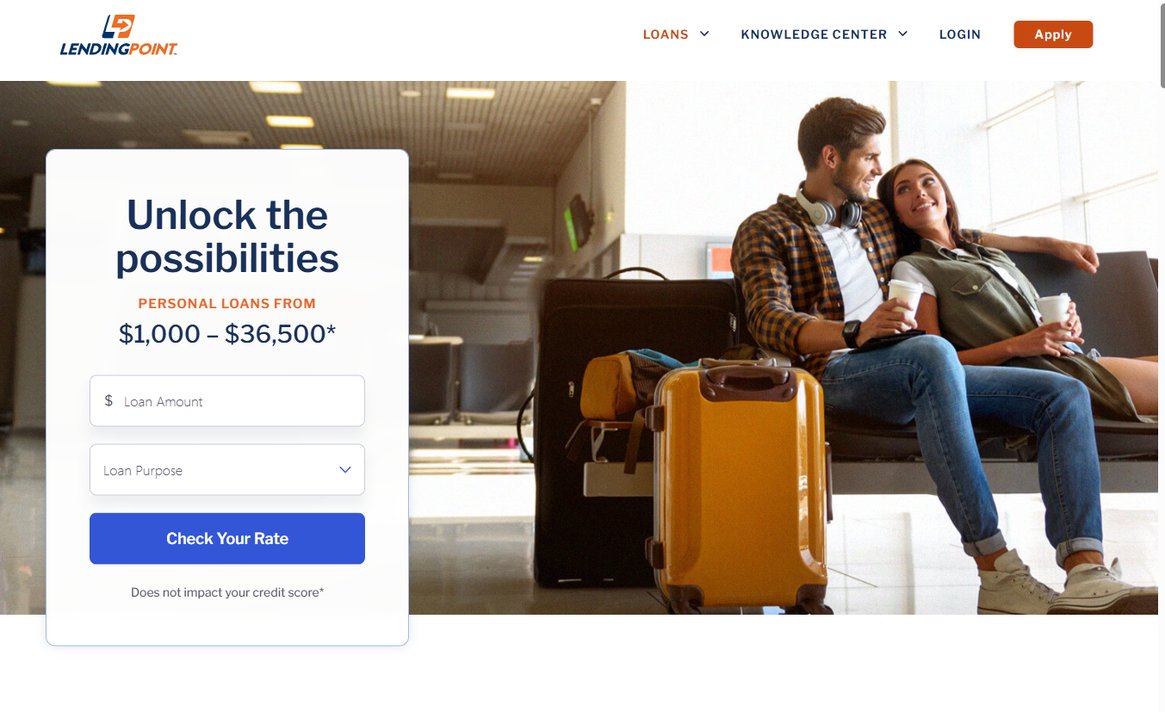
LendingPoint acts as a bridge, helping people transition from financial chaos toward a much-needed sense of stability. Their loan limits are quite flexible, which makes them a versatile option for various needs. You might find yourself needing a small sum to cover an unexpected medical bill, or perhaps a much larger amount to consolidate high-interest debt.
If you are currently drowning in $15,000 of credit card debt, those monthly interest charges can feel like a mountain that keeps growing. A single consolidation loan from LendingPoint can flatten that mountain, merging everything into one manageable, predictable monthly payment. It is a practical way to stop the frantic monthly hunt for various due dates.
This lender is a strong contender for those tackling specific hurdles, such as renovating a home or managing debt. Their digital workflow is designed with your schedule in mind, respecting your sense of urgency. You can get a decision and upload your documents in mere minutes, which is a lifesaver when your budget is razor-thin.
Pros:
- Extensive maximum loan limit reaching $36,500.
- Checking your rates won’t hurt your credit score.
- Wide variety of uses, including travel or weddings.
Cons:
- Their requirements might be tougher than niche bad credit lenders.
2. FastLendGo
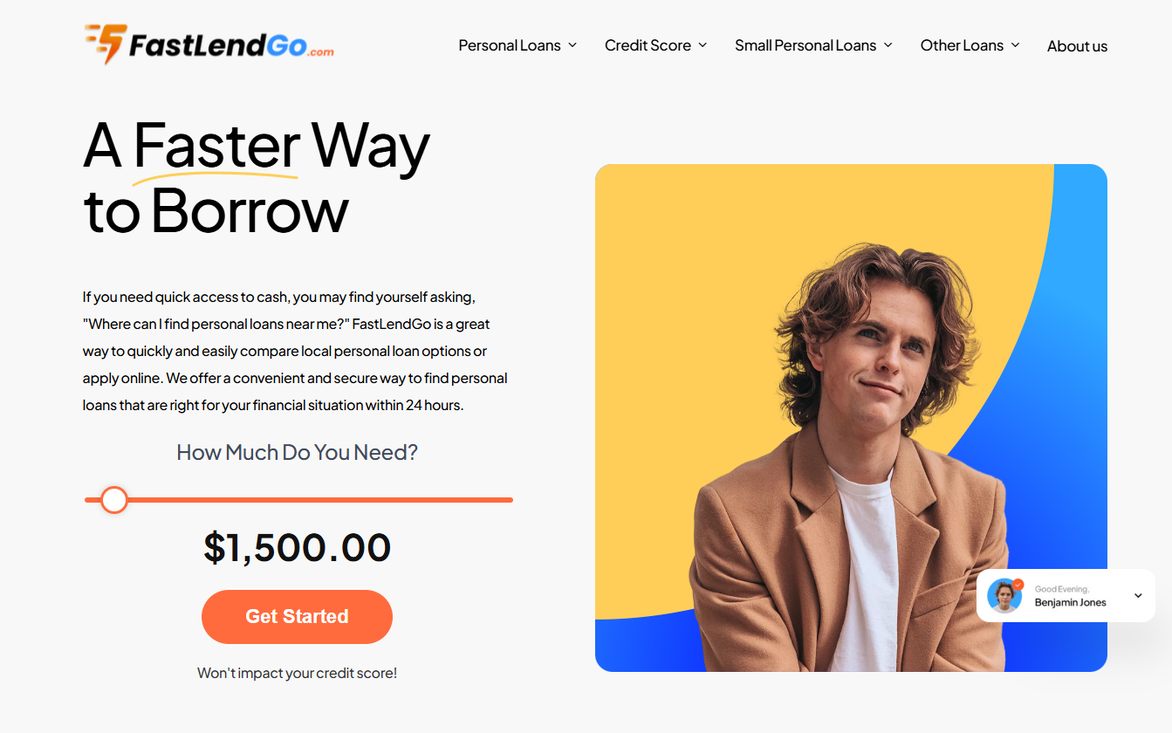
FastLendGo is built for the individual who needs cash immediately. Their focus remains on rapid access for urgent repairs, such as dental work or automotive issues. If your car’s alternator dies and you must fix it by Monday to keep your job, their specialized products are tailored for that exact moment of panic.
They bridge the gap between the high-interest world of payday loans and the slower pace of traditional banking. By offering structured personal loans, they provide a much more stable foundation than a quick cash advance, while remaining far more agile than a standard bank loan.
Whether you are looking for a $500 boost or a larger $5,000 loan, they provide different tiers to match your situation. This variety is vital when you are stuck in that difficult 550 credit score zone. Instead of being forced into a massive, overwhelming loan, you can pick a smaller amount that addresses your specific crisis.
Pros:
- Covers specific needs like motorcycle or roof repairs.
- Offers tiny loan amounts for immediate needs.
- Includes options for first-time borrowers and high earners.
Cons:
- The selection of products might be a bit overwhelming.
3. Max Cash
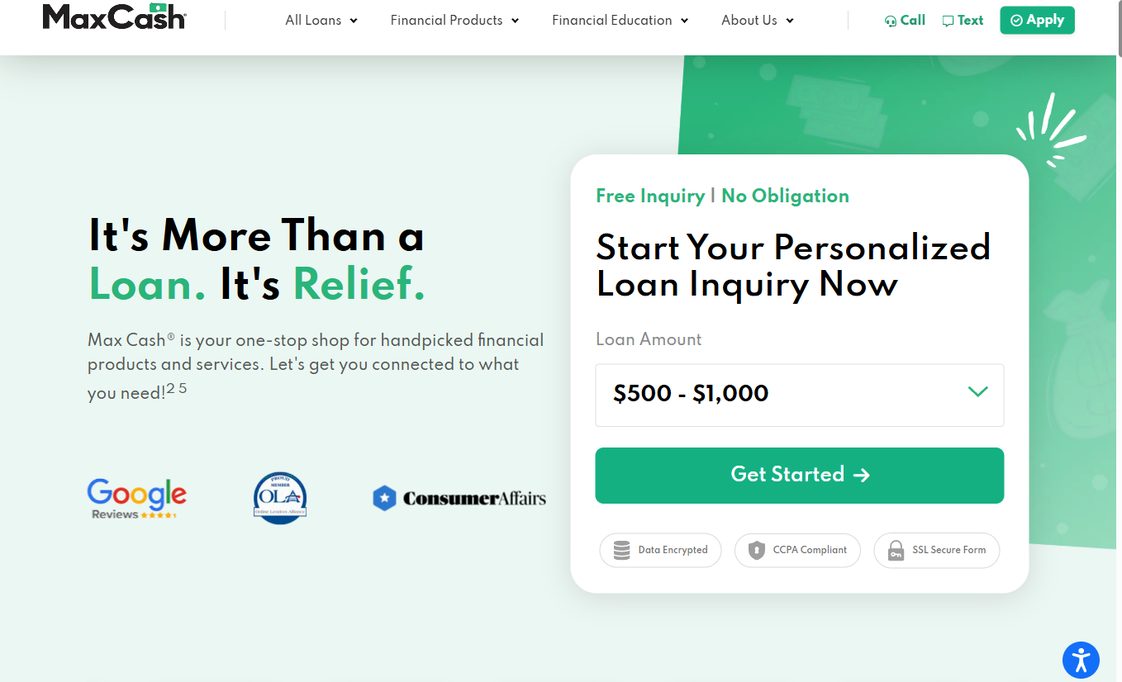
Max Cash functions as a specialized matching service designed to find you financial relief. For those navigating the challenges of a 550 score, they provide a way to connect with personalized lender matches. Their system directs you toward exactly what you require, saving you the headache of browsing dozens of different websites.
Rather than a generic, one-size-fits-all model, they employ an algorithm to hunt for the lender most likely to approve your unique profile. This is all about efficiency, ensuring you aren’t just casting a wide net and hoping for a bite, but rather targeting the right fish.
They excel at providing highly accessible, smaller amounts, with entry points starting at just $250. This is ideal for micro-emergencies where a massive loan would be totally overkill. If you just have a $300 utility bill, taking out $3,000 would be a financial blunder; Max Cash lets you fix the small problem without heavy interest.
Pros:
- Extremely low starting point for loan amounts.
- Quick inquiry process with absolutely no obligation.
- Adapts to a wide spectrum of credit profiles.
Cons:
- The focus on small loans might not suit major debt restructuring.
4. Avant
Avant stands out as a significant player for anyone looking to make meaningful financial progress. They have built a reputation for considering applicants with scores as low as 550. This makes them a vital resource if you have faced rejection from the major, traditional banking institutions.
Unlike some lenders that only look at a single FICO number, Avant takes a holistic view of your financial health. This perspective can be a total game-changer for people who have dealt with recent financial setbacks but still maintain a consistent income.
The lender is designed for long-term stability, focusing on things like home improvements or debt consolidation. If you get your application in before their afternoon cutoff, you might see those funds in your account remarkably fast. Their digital platform is built for the modern user who wants to manage finances via a mobile app.
Pros:
- Targets the 550 credit score demographic specifically.
- Rapid funding options for those who are approved.
- Provides both loans and credit cards for diverse needs.
Cons:
- Approval relies heavily on specific timing and individual criteria.
5. Reprise
Reprise operates in an entirely different arena, concentrating on high-tech tools and AI-driven solutions. They are not a standard personal loan lender like the others mentioned here. Instead, they represent the cutting edge of financial technology and sophisticated data management.
This service is best utilized by businesses or tech-savvy companies seeking advanced data injection and demo creation. It is a highly specialized tool for those needing to present complicated data through an interactive lens, rather than an individual seeking quick cash for an emergency.
For instance, a fintech startup wanting to show investors how a loan application process works could use Reprise to build an interactive experience. It is ultimately about the sophisticated technology running behind the scenes rather than the consumer at the bank counter.
Pros:
- Highly sophisticated AI toolset for creating demos.
- Efficient presentation and data injection capabilities.
- Makes sharing product tours incredibly easy.
Cons:
- Not a typical personal loan provider for individual customers.
Calculating Your Real Debt: Comparing APR and Monthly Installments
When life throws a curveball and money gets tight, your first instinct might be to chase the smallest monthly installment possible. You might find yourself staring at two different loan quotes. One asks for $50 every month, while the other demands $75. Naturally, that fifty-dollar option feels like a lifeline for your immediate budget.
It feels like a win, doesn’t it? Having extra cash on hand today provides a sense of breathing room. However, looking only at your monthly bill is like judging a marathon by only looking at the first step. It is a deceptive way to measure the weight of your debt.
The actual price tag of your loan is hidden within the Annual Percentage Rate (APR). Lenders often play a shell game by stretching your repayment timeline out to seven years. While this keeps your monthly obligation manageable, it creates a mountain of interest that grows taller every single month.
By the time you reach the finish line, you might find you have paid back double or even triple your original principal. This is the hidden tax on borrowed time. It is essential to look past the immediate relief to see the long-term impact on your wealth.
Before signing any paperwork, you must ask yourself a vital question. “How much will I have handed over in total once this debt is fully cleared?” If that total sum is vastly larger than the amount you originally took out, you are paying a heavy premium.
You are essentially buying convenience at a massive cost. While a lower monthly payment keeps your head above water today, it might drown you in interest tomorrow. Always weigh the APR against your long-term goals to ensure you aren’t trading your future stability for a temporary fix.
Navigating the Ripple Effects of Credit Checks
If your score sits around 550, you must grasp how the application journey dances with your credit rating. It is not a one-size-fits-all process, as the impact depends entirely on the nature of the investigation. Essentially, you are dealing with two distinct categories: soft inquiries and hard inquiries.
Think of a soft pull as a casual glance through a shop window. This typically happens when you utilize “check your rate” tools to see if you qualify for better terms. Lenders use this method to peek at your history without actually committing to a formal deal.
The beauty of these soft checks is that they are invisible to everyone else. Other creditors won’t see them on your official report, and your score remains untouched. It is a risk-free way to test the waters before diving in headfirst.
On the flip side, a hard pull is the heavy hitter of the credit world. This happens the moment you officially hand in an application for a credit card or a personal loan. It is a formal request for credit that leaves a permanent footprint on your record.
When a bureau sees these marks, they assume you are hunting for fresh debt, which can signal potential financial instability. Consequently, each formal inquiry might trigger a minor, fleeting drop in your numerical score. If your goal is to rebuild your reputation, treat these inquiries like gold—use them sparingly.
Navigating the Selection Process and Steering Clear of Traps
Selecting a lender feels remarkably similar to testing out a new pair of boots on a rugged hiking trail. If the fit isn’t perfect from the start, every single step ahead will feel like an uphill battle. You shouldn’t just fixate on what comes out of your bank account each month.
The monthly installment is often a siren song that leads borrowers into dangerous waters. A deceptively small monthly obligation might actually be masking a predatory interest rate. This hidden cost acts like a slow leak in a tire, eventually draining your finances until you are completely stranded.
Before signing anything, demand a truth-in-lending disclosure document. This isn’t just a suggestion; it is a legal safeguard designed to protect you. It lays out the total finance charge and the full sum you will ultimately repay in black and white.
Think of this document as a map for a long journey. It strips away the mystery and ensures you know exactly where your money is heading. Without it, you are essentially flying blind through a thunderstorm without any radar to guide you home.
A common blunder that trips up many applicants is the “shotgun” method of applying. When you blast out applications to every lender in sight, you trigger multiple hard inquiries simultaneously. This sudden flurry of activity signals to banks that you are struggling to keep your head above water.
Such a pattern can cause your credit score to plummet even further than it already has. Rather than casting a wide net and hoping something sticks, you should be surgical. Identify one or two providers that align with your current circumstances and focus your energy there.
Lastly, you must scrutinize the fine print with a magnifying glass. Pay close attention to the specific repayment terms and hunt for any mention of prepayment penalties. Some institutions will actually penalize you for trying to settle your debt ahead of schedule.
You don’t want to find yourself caught in a high-interest snare just as you are gaining momentum toward financial freedom. Treat these loans as a stepping stone toward better credit, not a permanent weight around your neck. Use these resources with extreme caution and intelligence.