

Uncategorized @vi
Get Instant Approval for Bad Credit Loans New York Online
Get Instant Approval for Bad Credit Loans New York Online
Latest revisions: 2026-10-17
Navigating your finances while living in NYC is a lot like trying to dodge pedestrians during a rush-hour thunderstorm. When your credit history isn’t looking pristine, searching for a company that won’t slam the door in your face can feel like chasing a ghost.
Life in the five boroughs is expensive, to say the least. Between skyrocketing rent and the sudden sting of a hospital bill or a broken boiler, many locals find themselves needing cash quite urgently. It is a constant balancing act.
We designed these insights for residents dealing with sudden financial bumps who require dependable solutions. You shouldn’t be forced to pick between keeping the lights on and getting tangled in a predatory lending web. Navigating the city’s high-pressure lifestyle requires smart, swift moves.
Finding the sweet spot between quick access to funds and the total cost of borrowing is the real trick to survival. Don’t let the stress of the concrete jungle push you into making a desperate, bad decision.
Evaluating Your Best Options
Choosing a provider involves much more than just glancing at a percentage on a screen. You really have to measure how fast the cash arrives against how much it will actually cost you over time. It is a trade-off of necessity.
A cheap interest rate won’t help you much if the approval process takes a fortnight while your landlord is knocking on your door. On the flip side, getting money instantly might come with a massive APR that leaves you underwater for months.
Our team examines how these lenders pull credit reports and how quickly they can wire money to your personal account. We look for clarity in their contracts to ensure no sneaky surprises are lurking in the fine print.
We test these services based on how they actually work for people living in this high-octane environment. Our mission is to cut through the glossy advertisements to help you locate genuine financial tools that actually work.
- SkyOne
- United Finance
- JetzLoan
- Experian
- GreendayOnline
Our Criteria for Selecting New York Lenders
When we sat down to review these options, our primary goal was checking how easy it is for people with bruised credit to get a foot in the door. We looked closely at whether an inquiry triggers a hard credit pull right out of the gate. This is crucial because a sudden drop in your score can feel like a punch to the gut before you even know if you’ve been approved.
In a high-stakes environment like New York, where every point on your credit report counts, we prioritized companies that offer “soft pull” quotes. This allows you to shop around without any risk to your standing. It is a necessary safety net for anyone trying to navigate a tight financial spot without making their situation even more complicated.
Time truly flies when you are staring down a mountain of unexpected bills. Whether you are facing a sudden car breakdown that threatens your commute or an urgent utility bill, you need cash yesterday. We hunted for lenders that move mountains to get funds into your bank account quickly. We refused to settle for companies that hide behind endless red tape or murky terms.
We also weighed how well these lenders cater to different financial needs. A small $500 loan might cover a quick fix for a household appliance, but sometimes you need a much heavier lifter. A $25,000 loan can act as a lifeline for consolidating those high-interest credit card balances that are currently strangling your monthly budget. We wanted versatility for every scenario.
Transparency was the name of the game during our deep dive into repayment schedules. We had to separate the genuine services from the predatory sharks that lure you in only to trap you in a cycle of debt. We actively avoided any lender that uses confusing fine print to mask the actual cost of borrowing.
Watch out for hidden traps, specifically those excessive origination fees that get added to your principal amount. We also scrutinized how clearly a company explains the total cost of your credit over the entire loan duration. If a lender tries to keep the real math under wraps, they simply do not make the cut in our selection.
| Provider | Funding Range | Processing Time | Credit Criteria |
|---|---|---|---|
| SkyOne | $500 – $50,000 | check website | Personal Loans available |
| United Finance | check website | check website | Installment loans available |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Experian | $2,000 – $50,000 | Same-day funding available | check website |
| GreendayOnline | $100 – $5,000 | As soon as the same day | Bad credit welcome |
Top-Rated Lending Options for Your Needs
1. SkyOne
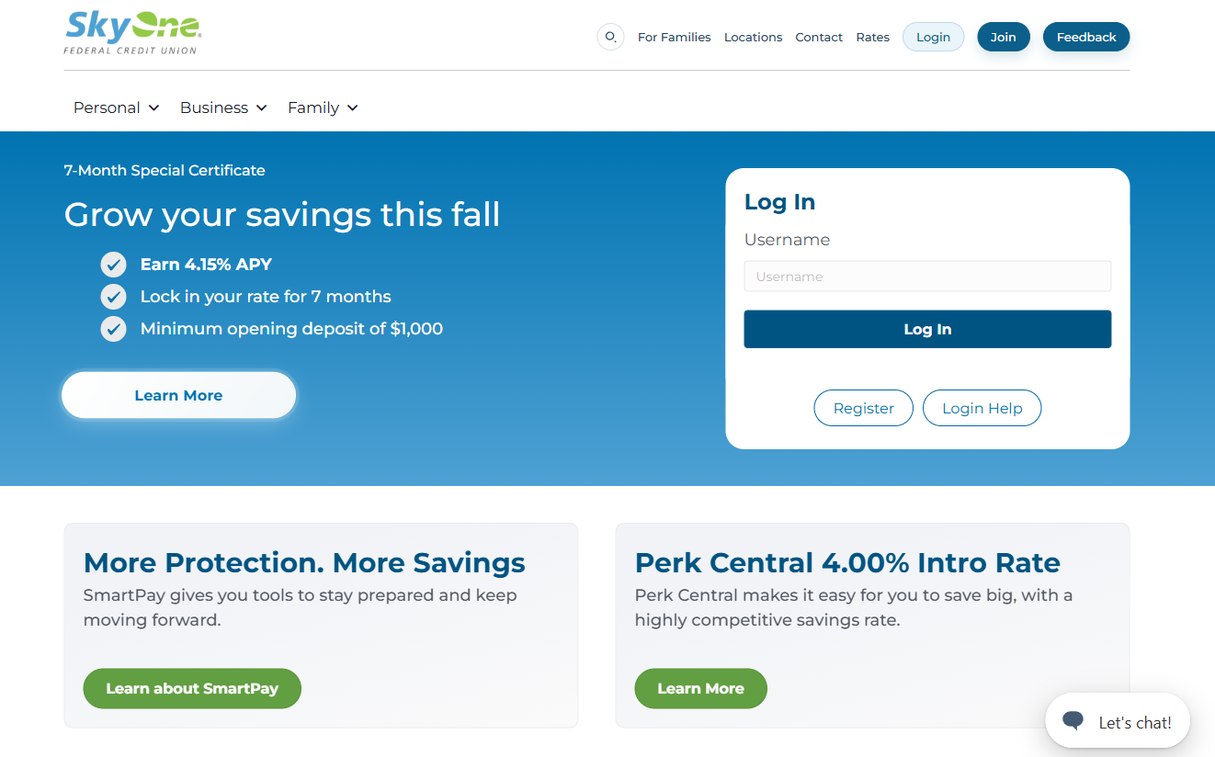
Operating as a federal credit union, SkyOne takes a more human approach to personal finance. While standard banks often rely on cold, automated algorithms to reject applicants, credit unions are owned by their members. This structure often leads to a much more comprehensive review of your unique situation.
They offer various products, including personal loans and lines of credit, which can serve as a vital lifeline. For those struggling to get their head above water, these financial tools can help stabilize a shaky budget. It is a refreshing change from the impersonal nature of big-box banking.
Interest rates for their personal loans can begin at 13.99% APR. This figure is quite competitive, especially if you compare it to the punishing rates found on high-interest credit cards. If you are eyeing a major purchase, such as home improvements or a new car down payment, their limits reach as high as $50,000.
Pros:
- Personal loan APRs start at a competitive 13.99%.
- Borrow up to $50,000 through high maximum limits.
- Choice between loans and lines of credit for versatility.
Cons:
- You may need to meet specific credit union membership criteria.
2. United Finance
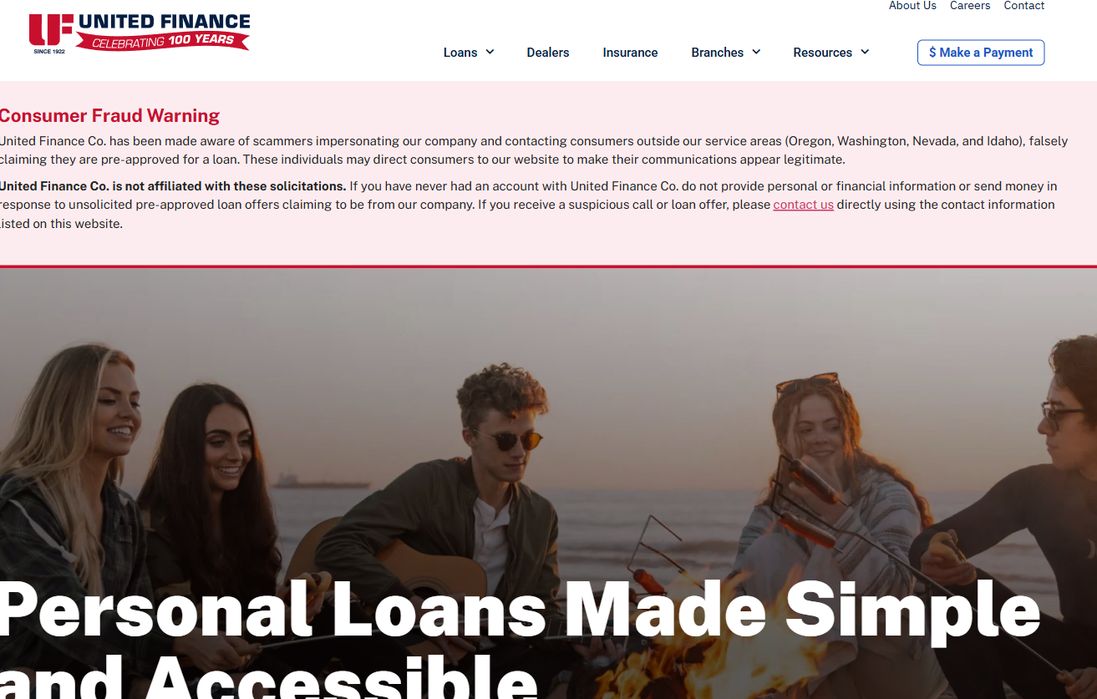
Since 1922, United Finance has been a cornerstone of the lending world. Their century of experience is a significant asset for anyone navigating complex financial waters. They specialize in installment loans, which provide a much more predictable repayment structure than the volatile payday loan market.
With an installment loan, you tackle a fixed amount of principal and interest over a set schedule. This makes budgeting a breeze because you know exactly what is coming out of your pocket each month. It is a far cry from the “revolving” debt trap that keeps people stuck for years.
Because they have survived many economic shifts, they offer a level of institutional stability that newer fintech apps simply cannot match. They are also vocal about protecting consumers from scammers. This is crucial for New Yorkers who frequently deal with predatory phishing attempts via text or email.
Pros:
- A long-standing reputation built since 1922.
- Focuses on stable installment loans instead of risky cycles.
- Prioritizes security and protection against consumer fraud.
Cons:
- Availability is restricted to certain states like Nevada and Oregon.
3. JetzLoan
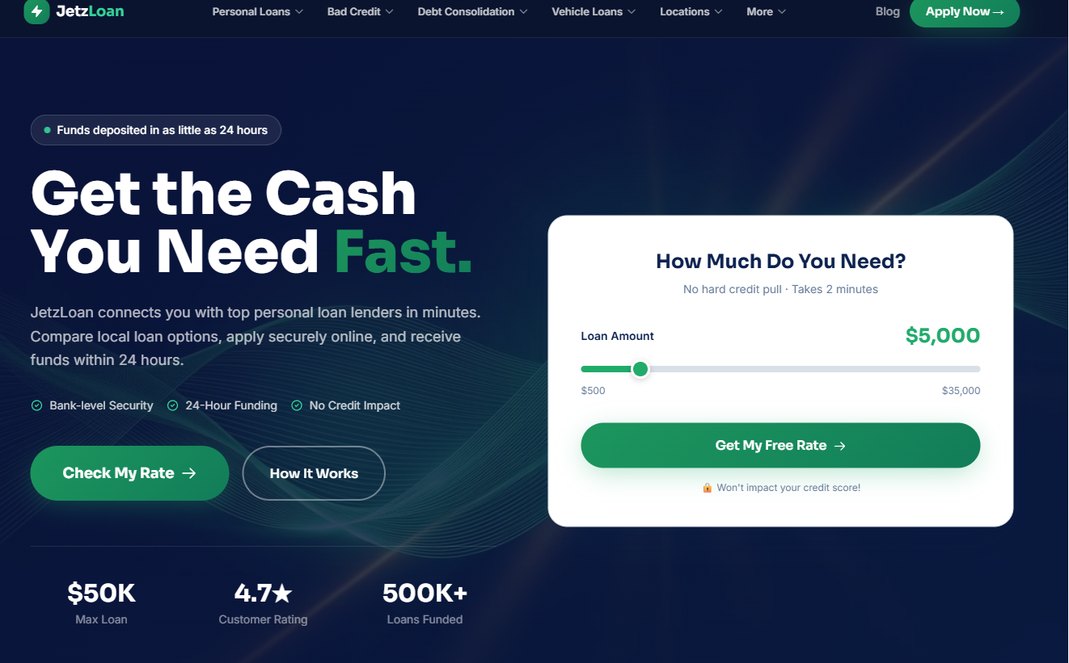
If you find yourself in a tight spot and need liquidity immediately, JetzLoan is built for lightning speed. Their system is designed to link you with premier lenders in mere minutes. The real kicker is their ability to show you rates without a hard credit inquiry.
This pre-qualification stage is a game changer for your credit score. Most people worry that looking for a loan will tank their rating, but with JetzLoan, you can shop around safely. The platform is incredibly intuitive, allowing you to finish the initial form in under two minutes.
Forget the endless piles of paperwork required by traditional banks. This digital-first interface is perfect for someone on the move, perhaps checking options while riding the subway. With money potentially landing in your account within a 24-hour window, it is perfect for urgent situations.
Pros:
- No impact on your score during initial rate comparisons.
- Rapid funding, potentially within a single day.
- Super fast, two-minute application process.
Cons:
- The maximum borrowing amount is capped at $35,000.
4. Experian
Experian is a massive name in the credit monitoring space, and their lending services are no exception. They possess a deep, fundamental understanding of how credit scoring works. They provide personal loans from $2,000 up to $50,000, with repayment windows between 24 and 72 months.
Opting for a longer term can significantly lower your monthly payments, giving your cash flow some much-needed breathing room. Just remember, a longer timeline means you will pay more in interest over the total life of the debt. It is a balancing act of immediate relief versus long-term cost.
They are also uniquely positioned to help you fix your financial reputation. By using tools that report rent or utility payments, you can actively work on boosting your score. This creates a powerful cycle: use a loan to clear a hurdle, then use Experian to ensure your score soars.
Pros:
- Certain loan types qualify for same-day funding.
- Flexible repayment schedules lasting up to 72 months.
- Built-in tools to assist with credit score improvement.
Cons:
- Score increases and loan approvals are never a certainty.
5. GreendayOnline
GreendayOnline is tailored for those who need a quick cash injection to bridge a sudden gap. They provide installment loans ranging from $100 to $5,000. This service is a niche solution for emergencies where speed is the absolute priority above all else.
While this isn’t the tool for wiping out massive long-term debt, it is perfect for surviving the stretch between paychecks. The entirely online process is incredibly convenient for the fast-paced lifestyle of a New Yorker. They are specifically geared toward helping those with poor credit history.
It serves as an essential safety net for people who have faced previous financial setbacks. If you just need a little extra help to get through the month without a mountain of paperwork, this is a straightforward, simple option.
Pros:
- Low entry point with minimums starting at $100.
- Quick approval process with same-day cash options.
- Specifically designed for applicants with bad credit.
Cons:
- Loan limits are quite small compared to other providers.
Navigating Your Loan Comparisons
Sitting down with a stack of paperwork can feel like trying to read a map in a thunderstorm. You might find yourself drowning in a sea of confusing dates and fluctuating percentages that make your head spin. It is easy to get lost in the weeds when every lender promises the moon.
To keep your feet on solid ground, you need a plan of attack. Do not let the marketing gloss blind you to the fine print lurking beneath the surface. Taking a breath and following a methodical process will ensure you don’t end up in a financial bind later on.
Think of this as a checklist for survival in the lending marketplace. By focusing on a few specific variables, you can transform a chaotic mess of offers into a clear path forward. Here is how you can sift through the noise to find the best deal for your wallet.
- Prioritize the APR over the Interest Rate: While the interest rate tells you the base price of borrowing the principal, it doesn’t tell the whole story. The Annual Percentage Rate (APR) is the real truth-teller because it bundles in hidden costs like processing or origination fees. Always use the APR to decide which deal is actually cheaper.
- Establish Your “Maximum Monthly Outflow”: Before you fall in love with a low interest rate, take a hard look at your monthly cash flow. If your budget only allows for an extra $150 in monthly spending, walking away from a $200 payment is vital. Do not let a low rate trick you into an unaffordable commitment.
- Scout for Prepayment Penalties: Some lenders will slap a fee on your head if you try to be responsible and pay the debt off ahead of schedule. If you are expecting a sudden windfall, such as a tax refund or a work bonus, ensure your contract allows for early repayment without any extra costs.
- Confirm the Actual Funding Timeline: If you are facing an urgent crisis, asking if you are “approved” isn’t enough to put food on the table. You must ask, “When will the funds be cleared and available in my bank account?” There is a massive gap between getting a thumbs-up and seeing real cash in your balance.
Navigating the Urban Lending Maze
Walking through the financial canyons of New York City can feel like stepping into a shark tank. Because there are so many options, some unscrupulous providers try to corner you using intimidation. If a company keeps badgering your phone or claims you will face “immediate rejection” unless you sign right this second, run the other way.
Real, reputable lenders act differently. They won’t treat you like a target or use high-pressure sales pitches to force a signature. Instead, they maintain a professional demeanor and grant you the breathing room required to scrutinize every single clause in the contract before committing.
Watch out for the trap known as “loan stacking.” This happens when someone grabs a tiny, expensive loan to cover an existing high-interest debt. It feels like you are putting out a fire, but you are really just pouring gasoline on the embers. The debt doesn’t disappear; it just shifts around while the interest piles up like snow in a blizzard.
If you find yourself caught in a cycle where you need a new loan to satisfy a previous one, the exit ramp is debt counseling. Continuing down this path is like running on a treadmill that keeps speeding up. It is better to halt your spending and seek professional guidance before the situation spirals out of control.
Finally, do not be blinded by a shiny website. In our digital age, a sleek design is merely the bare minimum requirement for any business. A professional interface does not guarantee a legitimate operation or a safe way to borrow money.
Always check that the lender is officially registered to do business in your specific state. You should be able to find a verifiable physical office and authentic feedback from past clients. True stability is found in a company’s historical reputation and their willingness to be completely transparent about their terms.
Making Smart Choices with Credit Options
Before you put pen to paper, pause for a heartbeat. It is incredibly tempting to dive headfirst into the rush of a rapid approval, but you must scrutinize the full price of your debt. Always inquire about hidden origination charges or penalties for paying the loan off early, as these can inflate the actual cost beyond the initial estimate.
Think of it this way: a $1,000 loan that requires $100 in upfront fees just to unlock the funds is much pricier than the marketing makes it seem. Don’t let the shiny numbers distract you from the fine print. Being thorough now prevents a massive headache once the money is spent and the debt remains.
Resist the urge to grab several tiny loans from various lenders to tackle one major bill. This strategy often creates a financial whirlpool that is notoriously hard to climb out of once you are caught in the current. It feels like a temporary fix, but it is often just a band-aid on a much larger wound.
Whenever you can, attempt to merge your various financial obligations into a single, steady monthly installment. This approach keeps your household budget predictable and keeps your anxiety at bay. Juggling five different interest rates and various monthly deadlines is a mental marathon that most people find exhausting and difficult to track accurately.