

Uncategorized @vi
Secure Fast Bad Credit Loans North Carolina: Best Online Rates Now
Secure Fast Bad Credit Loans North Carolina: Best Online Rates Now
Last updated: 2026-10-16
Managing finances in North Carolina can feel like wading through thick mud when your credit history isn’t particularly bright. Many locals encounter sudden setbacks, such as a Raleigh vehicle’s transmission giving out or an unplanned visit to a Charlotte urgent care facility. These sudden expenses demand instant liquidity to prevent your daily life from grinding to a halt.
A single unexpected bill can throw a wrench into your entire monthly budget in just a few hours. You might suddenly find yourself scrambling just to pay for the lights or your monthly rent. It is a heavy burden when your grocery money has to be diverted to cover a utility bill instead.
Selecting a lender requires more than a quick peek at the interest percentages. You must balance the necessity of speed against the ultimate price of the debt. An attractive low-interest loan might look great on a spreadsheet, but if the funds take ten business days to arrive, they won’t save you if the power company is knocking on your door tomorrow.
Conversely, a rapid cash solution might offer the speed you crave, but it might come with an APR that inflates your total repayment significantly. This selection outlines which paths might fit your unique circumstances during these unpredictable times. It assists you in evaluating the tension between instant cash access and your future financial health.
- FastLendGo
- Addition Financial
- PaydayPact
- Credit Human
- LoanStart
Assessing Loan Options Throughout North Carolina
Our team spent hours dissecting how simple it truly is for residents to grab cash when their credit score is trailing behind. We didn’t just look at the numbers on a page. We weighed how quickly the money hits your bank account after you hit submit.
Flexibility was the name of the game for our researchers. We wanted to see if these companies could dance with those holding subprime ratings. It isn’t just about getting a “yes”; it is about how much leeway a lender provides when things get rocky.
We dug deep into the digital interface of each provider. Can you finish an application on a mobile phone while sitting in a doctor’s waiting room? Or are you stuck at a desk with a scanner and a mountain of paperwork? In a pinch, speed is everything.
In the Tar Heel State, the cost of a “quick fix” often comes with a heavy sticker shock. Because lenders take a bigger gamble on someone with poor credit, they usually charge higher APRs to offset that danger. It is a tough pill to swallow, but it is the reality of the market.
Our list specifically highlights companies that don’t slam the door on you like a traditional bank might. If you were turned down by a massive institution on Monday, these lenders might be your best shot by Friday. We look for those who offer a clear roadmap to relief.
Honesty is the foundation of this entire study. We asked ourselves: will the lender reveal the full cost of the debt immediately? Or is the total repayment amount a hidden surprise waiting to jump out of the fine print once the contract is signed?
When you are living paycheck to paycheck, surprises are the enemy. You need to know exactly what your wallet will feel like three months from now. Transparency isn’t just a preference; for a person on a tight budget, it is a survival tool.
| Provider | Available Funds | Credit Standing | Payout Velocity | Agreement Details |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000 | Bad Credit / Fair Credit | Same day or next business day | see site |
| Addition Financial | see site | see site | see site | see site |
| PaydayPact | see site | Guaranteed approval online | see site | see site |
| Credit Human | As little as $500 | No credit review | see site | Up to 72 months |
| LoanStart | Up to $40,000 | see site | see site | see site |
Top-Rated Financial Solutions for North Carolina Residents
FastLendGo
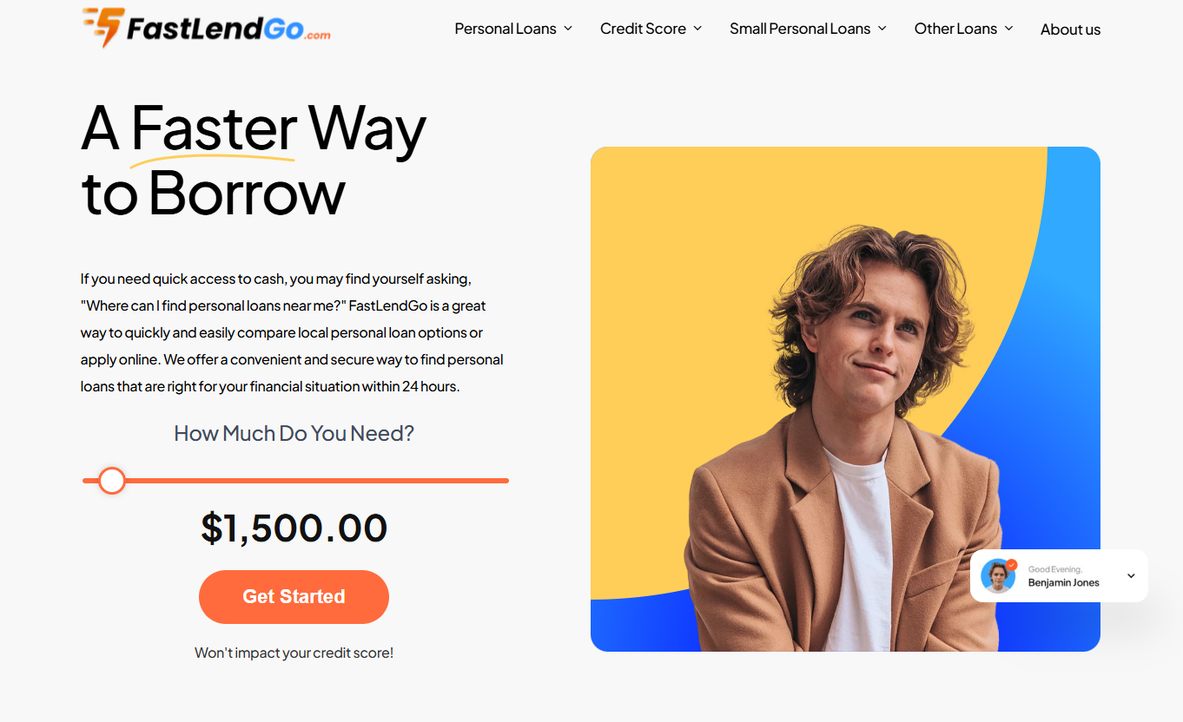
When life throws a curveball, such as a sudden car breakdown or a mounting medical bill, you need cash fast. FastLendGo excels in these high-pressure moments, prioritizing speed over bureaucratic red tape. Their digital platform is a breath of fresh air for busy people who want to solve emergencies in a heartbeat rather than waiting through endless paperwork. (fastlendgo.com)
This service is quite versatile, meeting various financial needs depending on your specific situation. You might find yourself reaching for a $500 micro-loan to cover groceries, or perhaps you need a $2,000 personal loan to handle a leaking roof. They welcome many different credit backgrounds, including those dealing with recent medical debt or fair credit users aiming for a better future.
Whether you are struggling to make ends meet or just need a temporary bridge, their system is built for efficiency. By focusing on a streamlined user experience, they ensure that getting funded is a painless process. It is an ideal pick for those who value their time above all else during a crisis.
Pros:
- Loan amounts range from $500 up to $5,000.
- Rapid disbursement, with funds potentially arriving the same day.
- No minimum credit score is needed to qualify.
Cons:
- The loan amounts are restricted to smaller ranges.
Addition Financial
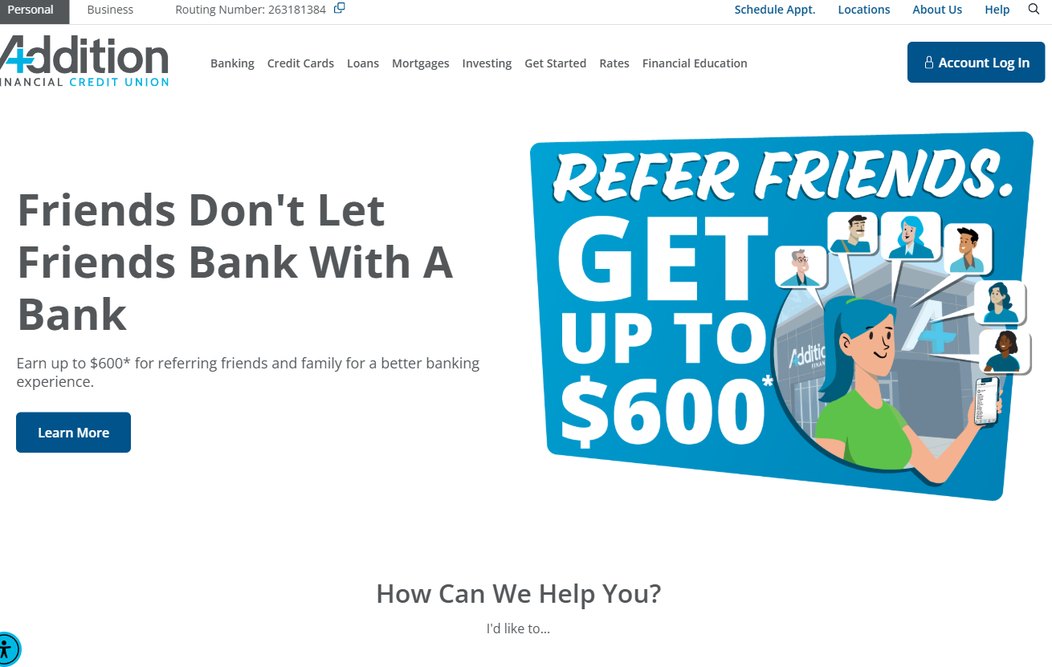
If you are looking for more than just a quick fix, Addition Financial offers a much broader umbrella of services. They operate like a traditional bank, providing everything from standard checking accounts to mortgages and credit cards. It is a perfect match for someone wanting to build a lasting relationship with a financial partner.
Rather than just patching a hole, they help you build a foundation through various savings options and competitive interest rates. If your goal is to step away from the exhausting cycle of high-interest debt and move toward stable, long-term banking, this institution is a logical next step. It is about playing the long game with your money.
They provide a sense of security that specialized quick-cash lenders often lack. By offering a full suite of products, they become a one-stop shop for your entire financial life. It is a solid choice for those seeking stability and a pathway to greater wealth over time.
Pros:
- A wide variety of available banking products.
- Opportunities to earn rewards through referrals.
- Provides comprehensive financial services.
Cons:
- The application process may demand more paperwork than other lenders.
PaydayPact
For those who have been turned away by traditional banks, PaydayPact serves as a highly accessible digital lifeline. Their online portal is built to be both incredibly secure and incredibly easy to navigate. You can apply from anywhere—whether you are on a bus in Durham or sitting on your couch at home.
This level of accessibility is a godsend for people who might not have a laptop or a printer handy. The primary appeal is the promise of an online guaranteed approval. When you are staring down a late rent payment, having that immediate “yes” or “no” can lift a massive weight off your shoulders.
Financial chaos is stressful enough without the added anxiety of wondering if your loan will be approved. This service targets that specific psychological burden by offering a streamlined, decisive process. It is designed specifically for the modern, mobile-first user who needs answers right now.
Pros:
- Excellent accessibility via mobile devices.
- An application process that is fully secure online.
- A core focus on providing guaranteed approval.
Cons:
- This type of lending model often carries high interest rates.
Credit Human
Credit Human provides a structured, predictable way to manage your borrowing needs with fixed rates. They offer a reliable safety net for those who need as little as $500 but want the peace of mind that comes with a set repayment schedule. You won’t have to wake up to a surprise increase in your monthly bill.
One of their most refreshing features is the ability to borrow without a standard credit check. This is a game-changer for North Carolinians who are tired of being defined by a single three-digit score. They look at your whole financial picture, recognizing that a temporary setback doesn’t define your character or your reliability.
By focusing on broader stability rather than just a snapshot of your credit, they open doors for many. This makes them a standout choice for anyone looking to rebuild their financial footing without the usual stress. It is a more human approach to lending in a digital age.
Pros:
- Repayment terms that are flexible up to 72 months.
- Certain products do not require a formal credit review.
- Fixed rates ensure your payments remain predictable.
Cons:
- Longer repayment periods can result in higher total interest.
LoanStart
Think of LoanStart as a smart matching service that introduces you to a massive network of affiliate lenders. Instead of putting all your eggs in one basket, you get access to a vast web of partners. This is vital because a loan that fits a student might be a poor fit for a small business owner.
If you are looking for a heavy hitter to tackle large debts, this is it. They offer the potential to access up to $40,000, which is perfect for anyone looking to consolidate high-interest credit card debt. Instead of juggling multiple payments, you can fold them into one manageable installment loan.
This consolidation strategy can be a massive win for your monthly budget. By rolling those expensive balances into a single loan, you could save hundreds in interest and finally breathe easy. It is about taking control of your financial destiny through smart, large-scale planning.
Pros:
- Access to substantial amounts up to $40,000.
- The service is free and won’t impact your credit score.
- Connects you to a wide array of different partners.
Cons:
- You must follow the specific terms of the affiliate lender.
Weighing Your Options: Fast Cash vs. Structured Repayment Plans
For those living in North Carolina, grasping the nuances between different borrowing methods is essential for staying afloat. Many lenders offer two primary paths: high-interest, short-term options or long-term installment agreements. Selecting the wrong vehicle for your financial needs can quickly feel like running in quicksand, making it incredibly hard to escape the weight of mounting interest.
Think of these choices like choosing between a sprint and a marathon. One is designed for a sudden burst of speed to solve a momentary problem, while the other is a steady, long-distance trek. If you misjudge your pace, you might find yourself gasping for air long after the initial goal has passed.
Understanding these distinctions helps you keep your head above water. You don’t want to find yourself stuck in a revolving door of debt simply because you picked the wrong tool for the job. Let’s look at the breakdown of how these two main categories actually stack up against one another.
| Characteristic | Quick Cash Options | Installment Plans |
|---|---|---|
| Standard Term Length | A few months or even just days | Between 12 and 72 months |
| Cost of Borrowing | Extremely High (Frequently exceeding 300%) | Moderate to High (10% to 36%) |
| Ideal Scenarios | Urgent crises (like a $200 utility bill) | Big expenses (like a $3,000 car engine) or debt consolidation |
| How You Pay Back | Single lump sum or several tiny payments | Set monthly installments |
If a sudden, minor bill pops up that your upcoming paycheck can easily cover, a quick short-term loan might serve as a lightning-fast fix. It acts like a temporary bandage for a small scratch that needs immediate attention before it gets worse.
However, if the total amount you require is greater than what you earn in your next two pay periods, you should look toward installment loans. Attempting to cover huge gaps with short-term credit is a recipe for disaster. Choosing a structured plan is a much wiser way to steer clear of a dangerous “debt trap.”
Navigating Your Repayment Plan
Getting your hands on quick cash is merely the starting line; the real marathon begins once you face the monthly bills. In the Tar Heel State, it is quite common for people to fix a temporary emergency only to find themselves drowning in a fresh mountain of debt. It’s a slippery slope that many people stumble down without even realizing it.
To keep your head above water, you need a solid game plan before the interest starts to snowball. Relying on luck is a recipe for disaster when your financial health is on the line. Instead, consider these three tactical maneuvers to stay in the driver’s seat of your budget.
- Enable Automatic Transfers: Don’t leave your credit score up to chance or a busy schedule. Arrange for your bank to move money to your lender immediately following your payday. By automating this process, you essentially build a shield around your credit rating, ensuring no late fees or missed deadlines sneak up on you.
- Target High-Interest Debt: If you are juggling several different debts, try utilizing the “avalanche method” to clear the path. This means you cover the minimum requirements for every account, but you throw every spare cent at the loan carrying the highest interest rate. It is a mathematical powerhouse that slashes the total interest you’ll eventually pay.
- Communicate with Creditors: If a medical bill or a utility spike is forcing your hand, don’t reach for a high-interest loan immediately. Pick up the phone and talk to your service providers first. Most companies offer hardship assistance or structured payment schedules that are far more affordable than the steep costs of quick-cash lending.
Navigating the Hazards of New Debt
When financial emergencies strike, the temptation to sign documents without a second glance is immense. You should hunt for the “total cost of credit” figure, which serves as a crystal ball for your final balance. This specific metric reveals the entire amount due once your repayment obligations have been fully met.
Consider a scenario where you borrow $1,000 but face steep interest charges. You might find yourself handing back a total of $1,500 by the end of a six-month period. That $500 extra isn’t just extra cash; it is the premium you pay for immediate liquidity.
Don’t let a quick fix become a long-term headache. If you are considering using a new loan to settle an existing debt, make sure the interest rate is drastically lower. Otherwise, you might just be trading one heavy anchor for another.
Taking a high-interest payday loan to wipe out a credit card balance is like pouring gasoline on a small fire. You are essentially shifting your financial burden from one costly vessel into an even more expensive one. It is a dangerous game of musical chairs with your money.
If you feel like you are constantly juggling short-term loans just to stay afloat, you might be caught in a debt spiral. These cycles can be incredibly difficult to break once they gain momentum. Often, the real solution lies in fixing your monthly budget rather than seeking more credit.
Lastly, always vet a lender’s credentials before you hand over any private data. While the internet has made borrowing incredibly convenient, it has also provided a playground for digital wolves. They often hide behind a mask of urgency to trick the unwary.
Scammers love to use high-pressure tactics, shouting phrases like “You have been pre-approved! Act now or lose the offer!” to spook you. Their goal is to rush you into revealing your Social Security number or your banking credentials. Don’t fall for the bait.
Protect your identity and your hard-earned savings by sticking to official, secure web addresses. Before you type a single digit of your personal information, check the URL for the “https://” prefix. A padlock icon in the address bar is your first line of defense against identity thieves.