

Uncategorized @vi
Top-Rated Lenders for a Personal Loan After Bankruptcy: 2026 Rankings
Top-Rated Lenders for a Personal Loan After Bankruptcy: 2026 Rankings
Last updated: 2026-10-16
Reclaiming your financial life after a bankruptcy discharge can feel like navigating through a dense, blinding mist. Life has a funny way of throwing curveballs when you least expect them. Maybe your vehicle needs an urgent fix to ensure you stay on the job.
Perhaps a sudden medical expense arrived just as you were finally breathing easier. Or maybe a shift in your employment status left a temporary hole in your monthly budget. The real objective is locating a creditor that recognizes your future potential rather than dwelling on past errors.
The landscape of personal borrowing has undergone a massive transformation. In the old days, a bankruptcy was often a permanent roadblock. Today, however, fintech innovators and local credit unions look at your current patterns instead of just the shadows of your history.
Modern lenders prioritize your financial trajectory over the old scars on your credit score. They are interested in the direction your life is heading today. It isn’t about where you stumbled, but how steadily you are moving forward right now.
Selecting an appropriate lender requires looking far beyond a simple interest rate. You must balance how quickly you need the funds against the minimum qualifications required. It is a delicate dance between obtaining cash instantly and ensuring long-term stability.
Some companies specialize in rapid-response emergency funds to bridge immediate gaps. Others prefer providing structured installment options designed to assist in credit rebuilding. You have to weigh the speed of the transaction against the overall flexibility of the terms.
The concept of accessibility is a double-edged sword that varies by individual needs. A company that grants approvals with ease might demand higher interest rates for that speed. This is the price you pay for avoiding a long wait.
Conversely, institutions with more rigorous standards might provide the lower rates necessary for managing debt. You must decide whether your current situation demands a quick band-aid or a comprehensive, long-term strategic plan.
- FastLendGo
- SoFi
- Prosper
- Avant
- Allegiance Credit Union
- VivaLoan
- World Finance
Selecting the Right Loan Providers After Bankruptcy
Our evaluation centers primarily on approval ease and the velocity of fund transfers. Life’s sudden crises rarely pause to wait for your credit report to look flawless. When an unexpected bill arrives, you need a partner that prioritizes accessibility over rigid perfection.
Time is of the essence in many of these scenarios. If a seventy-two-hour delay in receiving cash could lead to a utility shut-off, you cannot afford to chase slow-moving institutions. We hunted for companies that streamline the entire process for those rebuilding their financial footing.
We also scrutinized the range of borrowing options provided by each firm. Some lenders offer only small micro-loans, which fall short when you are trying to patch a leaking roof or manage larger debts. You need a range that fits your specific life event.
Mainstream banks often act like gatekeepers, demanding heavy collateral or high scores that are out of reach for many. We sought out lenders that permit “soft” inquiries. This allows you to compare different rates without taking a hit to your precious credit standing.
| Provider | Available Funding | Transfer Velocity | Eligibility Criteria |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Rapidly | Bad/Fair/Good/Great |
| SoFi | see site | see site | see site |
| Prosper | $2,000 – $50,000 | Quickly | see site |
| Avant | see site | see site | see site |
| Allegiance Credit Union | see site | see site | see site |
| VivaLoan | $100 – $15,000 | As soon as tomorrow | All credit types welcome |
| World Finance | see site | see site | see site |
Top-Rated Lenders for Boosting Your Credit Score
1. FastLendGo
Life throws curveballs, and FastLendGo is there to help you catch them. Whether you are staring down a tiny $500 fix or a more significant $5,000 endeavor, their menu of options is incredibly versatile. This makes them a lifesaver when you are balancing several fires at once, like fixing a leaky roof while simultaneously settling tax debts.
Speed is the name of the game here. If you find yourself in a pinch with a sudden dental emergency or a car that has suddenly decided to quit, you won’t want to wait weeks for a response. While big-name banks often bury you under a mountain of paperwork and endless office visits, FastLendGo operates with a digital-first mindset to keep things moving.
It is a dependable choice for anyone needing a quick financial bridge when time is of the essence. They don’t make you jump through hoops just to get a status update on your application.
Pros:- Flexible loan ranges spanning from $500 to over $5,000.
- Tailored financing for dental, auto, or roofing needs.
- Open to various credit profiles, from poor to excellent.
- Interest rates may not be the most competitive for those with top-tier credit.
2. SoFi
Think of SoFi less like a single lender and more like a massive financial ecosystem. While many people first encounter them through banking or investments, they offer a sophisticated suite of tools to help you master your money. Their high-yield savings accounts are particularly useful for building a safety net while your credit score gradually climbs back up.
By using their automated saving tools, you can start constructing a financial buffer. This little cushion can be the difference between staying afloat and falling back into the trap of high-interest debt. It is a “one-stop shop” for anyone wanting to manage everything from a basic checking account to a full-scale mortgage.
They tend to be more selective with their lending than the micro-loan providers, focusing on those who have already climbed out of their toughest financial valleys. If you are aiming for long-term wealth and stability, this is a very polished option.
Pros:- Comprehensive services including banking, insurance, and investing.
- Attractive APY for your savings.
- Smooth, modern digital user experience.
- Best terms are generally reserved for those with higher credit scores.
3. Prosper
Prosper opens the door to the world of peer-to-peer (P2P) lending. They deal in much larger sums, providing amounts from $2,000 all the way up to $50,000. This makes them a powerhouse for major life expenses, such as paying for college tuition or remodeling your kitchen, rather than just small repairs.
Because they utilize a network of individual investors instead of a traditional bank’s vault, their approval criteria can feel quite different. This unique structure provides a refreshing alternative to the standard institutional lending model.
Their digital platform is designed for efficiency and safety. You can check your potential interest rates in roughly sixty seconds via a soft credit pull. This is a huge relief if you want to shop around without the fear of taking a hit to your credit score.
For anyone looking to bypass the big banks, Prosper is a streamlined alternative. It serves as a robust option for heavy-duty financing when a traditional institution might have slammed the door on you.
Pros:- Large funding limits reaching up to $50,000.
- Fast rate checking that won’t damage your credit.
- Highly efficient and secure online application.
- Approval rates can fluctuate based on investor interest in the P2P model.
4. Avant
Avant is focused on helping you turn the page on your financial history. They specialize in products like installment loans and credit cards, which are perfect for demonstrating that you can maintain a steady pattern of on-time payments. They act more like a partner in your journey, offering tools specifically designed to help you tackle debt consolidation.
If you are tired of juggling several high-interest payments and want to roll them into one single, manageable monthly bill, Avant has the tools for you. They also provide emergency loans for those unexpected moments when life gets messy.
Their model is specifically tuned for the “middle-ground” borrower. These are individuals who might not possess a perfect credit score but can prove they have a steady income and a responsible approach to their recent finances.
Pros:- Expertise in consolidation and emergency lending.
- Adaptive solutions for different life stages.
- Supportive tools and customer-focused design.
- The specific requirements for eligibility can be tricky to understand.
5. Allegiance Credit Union
Since 1963, Allegiance Credit Union has been a staple of the community. They operate on the principle that every person has a unique story, including those who are currently rebuilding after a bankruptcy or financial setback. This is a far cry from the cold, impersonal feeling of a massive national bank where you are just a number.
At a credit union, your local connection and your personal relationship with a loan officer actually matter. They offer a variety of products intended to help you save money, borrow wisely, and pave the way for a more stable future.
You will often find much more personalized guidance when applying for a loan here. This human touch is invaluable when you need to explain that your past bankruptcy is a closed chapter and that your current financial path is trending upward.
Pros:- Deep community ties and a long-standing history.
- Focus on the well-being of their members.
- A wide variety of borrowing and saving options.
- Membership may be restricted by your specific geographic area.
6. VivaLoan
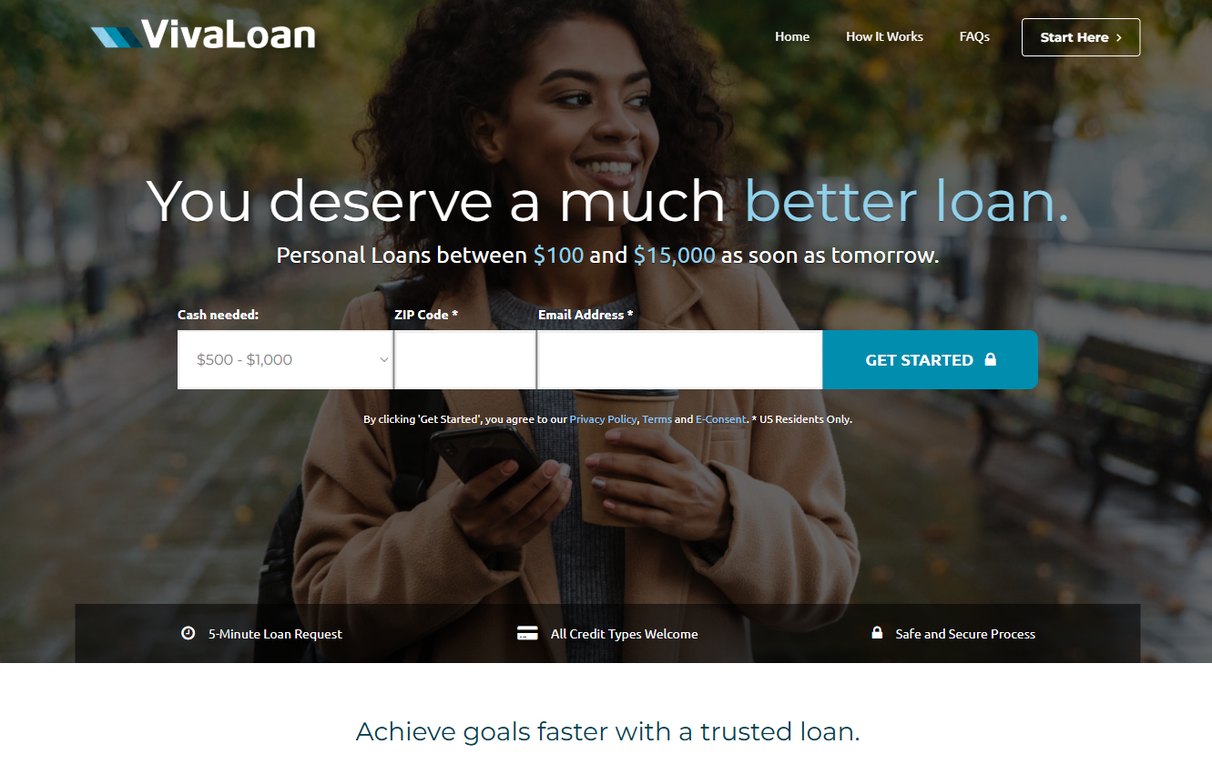
When you need money yesterday, VivaLoan is built for speed. They offer a massive range of loan amounts, starting as low as $100 and going up to $15,000. This variety is a lifesaver if you are still in the fragile early stages of financial recovery and just need to cover small, essential costs.
One of their most standout features is how incredibly fast the funding is. In many cases, you could see that cash in your account as soon as the next business day. With an application that takes only five minutes and an open-door policy for all credit types, they serve as a vital emergency lifeline.
While the speed is undeniably impressive, it is vital to use these funds with a clear plan. You want to ensure you are using the money to move forward rather than getting caught in a cycle of high-interest debt.
Pros:- Rapid funding, often arriving by the next business day.
- Very accessible minimums, starting at $100.
- Open to borrowers with any credit history.
- The speed and ease of access often come with a higher cost of borrowing.
7. World Finance
World Finance is a specialized player that operates a bit differently than your average lender. They provide a diverse array of services, including private and retail banking. Their niche often involves more structured financial environments, catering to people who don’t quite fit into a standard consumer lending mold.
This makes them an ideal match for individuals with non-traditional income sources or those who require very specific, complex loan structures. They keep a close eye on both local and global economic trends to better serve their clientele.
If you are looking for a financial partner that goes beyond the basics of a simple personal loan, they offer a depth of expertise that is hard to find elsewhere. Their services are particularly useful for those managing a sophisticated recovery that involves multiple types of assets.
Pros:- Extensive range of financial services and market insights.
- Deep expertise across various banking sectors.
- Professional approach to global and local market trends.
- Their services can be more intricate than those of a standard consumer lender.
Ways to Boost Your Chances of Getting Approved
Navigating the loan landscape following a bankruptcy discharge isn’t a walk in the park, but it is certainly doable. To catch a lender’s eye, you need to present “stability indicators” that prove you are a safe bet. Think of it like a first date; you want to look your most reliable self from the very start.
Even if your credit score is still limping along, you can’t let that discourage you. The secret sauce lies in your paperwork. Instead of scrambling when an officer asks for proof, have a neat folder ready with your latest pay stubs, bank statements, and tax returns. Showing an uninterrupted stream of earnings acts as a beacon of trust for any bank.
Lenders aren’t just looking at numbers; they are looking for a story of consistency. When you present a seamless history of income, you’re essentially telling them that your financial ship is no longer sinking. This preparation can be the difference between a quick rejection and a firm handshake.
Exploring the Benefits of Collateral-Based Borrowing
If you find that “unsecured” loan applications are hitting a brick wall, don’t throw in the towel just yet. It might be time to pivot toward a “secured” loan. These types of loans are essentially tethered to an asset you own, such as a savings account or even a car title.
Because you are putting something on the line as collateral, the lender’s fear of loss is greatly diminished. This lowered risk profile is a game-changer. It often opens doors that were previously slammed shut, frequently resulting in higher approval rates and much more favorable interest rates than what you would find elsewhere.
Think of this as a stepping stone rather than a final destination. As you diligently make your payments, your credit score will likely receive a much-needed shot in the arm. You are essentially buying your way back into the good graces of the financial world through demonstrated responsibility.
Ultimately, this method is a bridge to the bigger, “unsecured” loans you will eventually want to access. It’s a clever way to demonstrate your reliability while you are still finding your footing after a financial storm. By taking this smaller, safer step, you are building the foundation for a much more robust financial future.
Mistakes to Sidestep While Hunting for Credit
Scouring the market for financing can feel like walking through a minefield. Many people fall into the trap of grabbing the very first deal that crosses their path. It might look tempting on the surface, but speed is often the enemy of a good deal.
You should never judge a loan solely by the size of the monthly installments. A small, manageable payment often acts as a wolf in sheep’s clothing. It could be masking a sky-high interest rate or a grueling repayment timeline that doubles your total debt burden.
To truly understand what a lender is asking, you need the Annual Percentage Rate (APR). This number is your North Star, revealing the actual cost of your credit. Without it, you are essentially flying blind in a storm.
It is also vital to scrub your credit history for inaccuracies before hitting the “apply” button. Even once your bankruptcy is legally discharged, ghost debts can still haunt your files. I once knew a man who was denied credit simply because a settled debt was still marked as “active.”
Sometimes, an old obligation that was wiped out during your filing remains stubbornly listed as “unpaid.” These clerical errors can act like anchors, dragging down your credit score right when you need it most. Cleaning up your paperwork is your first line of defense.
Lastly, keep a sharp eye on the fine print regarding prepayment penalties. Some institutions will slap a fee on you if you try to settle the balance ahead of schedule. If your goal is to escape the cycle of debt, being penalized for paying early is a bitter pill to swallow.
Approach this whole process with the patience of a seasoned gardener. You aren’t just looking for a quick fix; you are planting seeds for future stability. Remember, building a healthy financial life is a long marathon, not a frantic sprint to the finish line.