

Uncategorized @vi
Top-Rated Lenders for a Personal Loan with Co Signer Right Now
Top-Rated Lenders for a Personal Loan with Co Signer Right Now
Last updated: 2026-10-17
Navigating the world of lending with a low credit score can feel like wandering through a dense mist without a compass. It is a frustrating maze where every turn seems to lead to a dead end. You might find yourself asking a family member or a trusted buddy for a hand.
By inviting them to act as a co-signer, you are essentially leaning on their financial reputation to pull you through. This small act of kindness often serves as the vital bridge needed to secure approval. It can mean the difference between a flat refusal and receiving funds for a sudden hospital bill or an emergency auto fix.
Before you sign on the dotted line, remember that the monthly installment is only one piece of the puzzle. You must evaluate the entire landscape of the debt. Consider how quickly the funds hit your account and the cumulative amount you will eventually pay back over the lifetime of the agreement.
A small monthly bill might seem like a dream until you realize you are locked into a 72-month commitment. Those extended timelines can cause interest costs to balloon out of control. Furthermore, lenders that boast about instant payouts might be masking steep origination fees. These extra costs can make the debt much pricier than what a standard bank would offer.
- FastLendGo
- OneMain Financial
- Upgrade
- Together Loans
- U.S. Bank
- MoneyLion
- MedLoan Finance
Our Selection Process for Top Providers
We poured countless hours into dissecting the current landscape of lending options, specifically targeting products designed for those utilizing a co-signer. Our team wanted to pull back the curtain on how these institutions manage dual-party submissions. It was vital to determine if the obligations for the secondary party were crystal clear or merely hidden behind a wall of confusing jargon.
Our deep dive involved distinguishing between true joint applications and setups where the second person functions as a guarantor. This nuance is everything because it dictates the level of personal liability being assumed. We bypassed any companies that made the experience feel like a mountain of red tape, choosing instead to highlight those offering a seamless path forward.
Honesty remained the North Star of our research. We searched for providers that offered lightning-fast decisions, transparent interest costs, and a diverse range of borrowing limits. We also scrutinized the “friction” levels inherent in their digital workflows. We measured this by counting the necessary file uploads, the ease of e-signatures, and the clarity regarding the Annual Percentage Rate (APR).
| Provider | Borrowing Limits | Terms & Interest | Payout Speed | Credit Profile |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | check website | check website | Poor to Excellent |
| OneMain Financial | $1,500 – $30,000 | APR starts at 11.99% | Within 1 hour | Friendly to Low Credit |
| Upgrade | Up to $50,000 | Options for fixed rates | Rapid disbursement | Focus on Credit Health |
| Together Loans | Up to $10,000 | Term of 24 – 60 months | 1 day for approval | Bad Credit/Trust Based |
| U.S. Bank | check website | check website | check website | Conventional Banking |
| MoneyLion | Up to $100,000 | check website | Quickly available | Credit Building Aimed |
| MedLoan Finance | $500 – $100,000 | Interest-free for 12-18 Months | check website | Healthcare Focused |
Leading Co-signer Loan Providers for 2026
1. FastLendGo
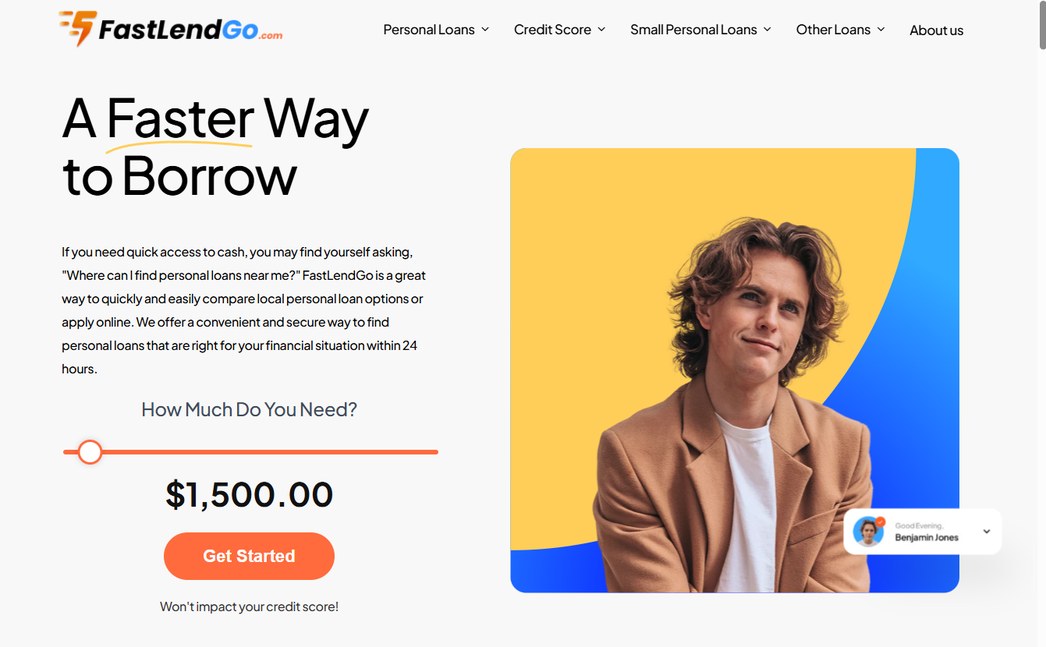
FastLendGo serves as a lifeline for individuals craving a quick infusion of cash without facing an endless mountain of paperwork. They cater to a broad spectrum of borrowers, ranging from those seeking a mere $500 for an urgent fix to those pursuing substantial funds for life-altering transitions.
Their guidelines lack the rigid, often intimidating structure found in a traditional mortgage department. This makes them an ideal match for gig economy workers or anyone dealing with an inconsistent monthly income. If you need a way to bridge the gap, fastlendgo.com might be your best bet.
For those navigating a “thin” credit history, this lender can be a total game-changer. Standard automated scoring models often fail to recognize the reliability of someone with limited credit usage. Instead, they provide tailored solutions for high earners and individuals with less-than-perfect scores, making borrowing accessible to nearly everyone.
Utilizing a co-signer here is a brilliant tactic to demonstrate the fiscal stability that your personal credit history might not yet reflect to a computer. It bridges the gap between where you are and where you want to be.
Pros:
- Minimum amounts begin at $500, perfect for those sudden, small emergencies.
- They specialize in covering costs like car repairs or dental work, preventing the need for multiple separate loans.
- A variety of flexible arrangements are available for numerous credit profiles.
Cons:
- Their specific focus means they may not be the ideal vehicle for general debt consolidation needs.
2. OneMain Financial
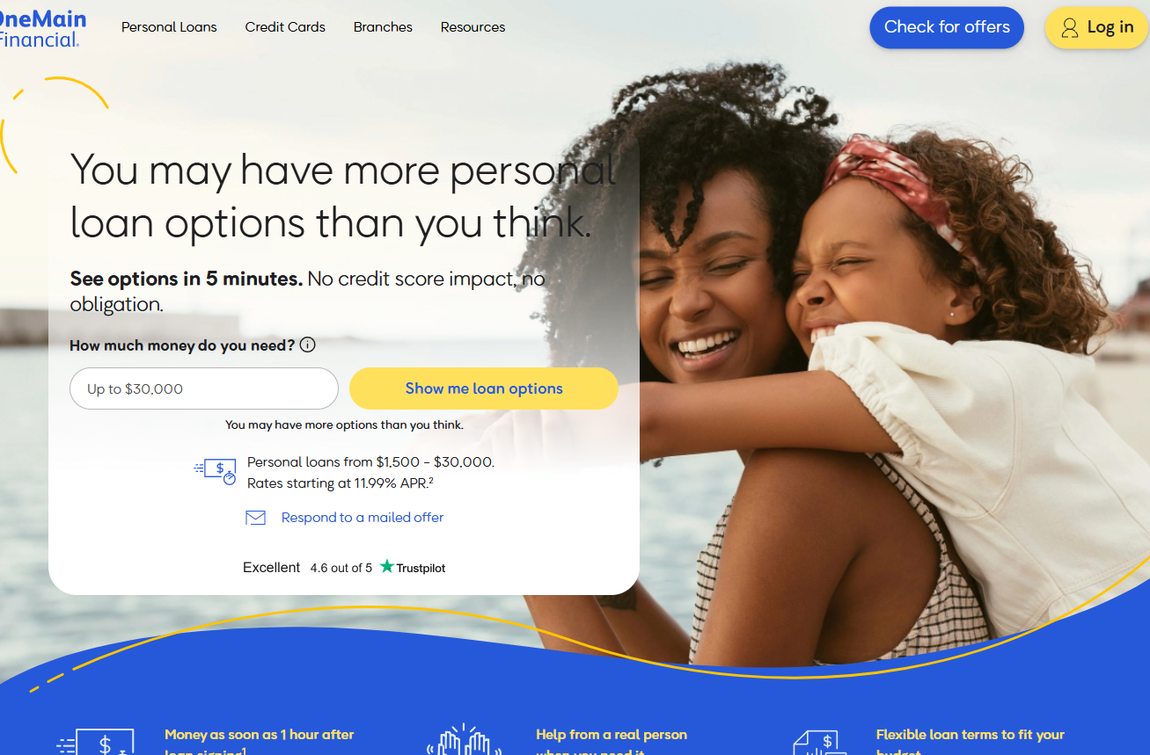
OneMain Financial is the premier choice for anyone who prefers the warmth of human interaction over a sterile smartphone app. With a physical presence spanning over 1,300 branches, they offer a level of accessibility that most digital-only competitors simply cannot replicate.
If explaining your complex financial situation to an algorithm makes you uneasy, sitting down with a professional in a real office can provide a massive sense of security. There is something to be said for looking a person in the eye when discussing your money.
Speed is a major part of their DNA. In certain scenarios, your funds could be sitting in your account just sixty minutes after you’ve signed the final documents. Their joint loan structures are also remarkably straightforward, which is a blessing for families or couples looking to share the burden of repayment.
This makes the process of bringing a co-signer on board incredibly seamless. It removes much of the confusion and anxiety often associated with shared financial responsibilities.
Pros:
- Funding can arrive lightning-fast, sometimes within a single hour.
- An expansive branch network ensures in-person assistance is always nearby.
- Joint loan setups for amounts between $1,500 and $30,000 are exceptionally user-friendly.
Cons:
- Lower credit scores may result in much higher interest rates that accumulate significantly over time.
3. Upgrade
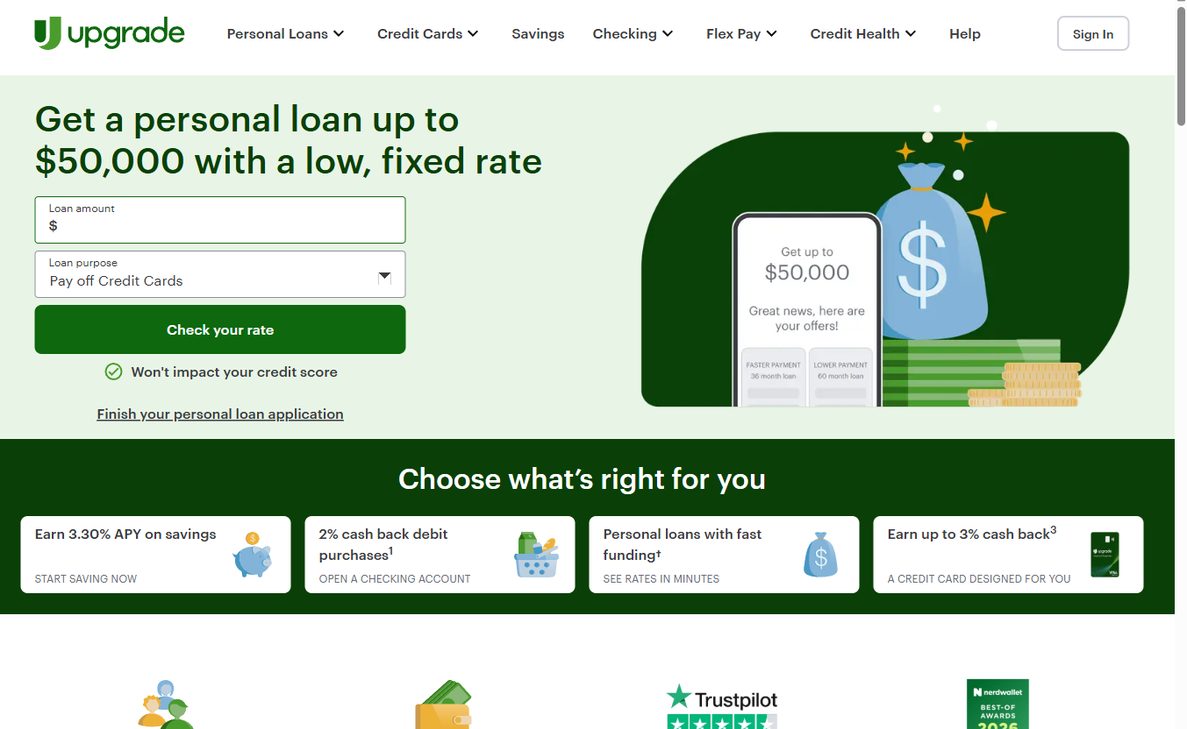
Upgrade adopts a contemporary mindset, looking at your long-term financial wellness rather than just the immediate transaction. They aim to be a complete ecosystem for your wallet, offering everything from savings accounts to credit cards. Their digital platform is intuitive, allowing you to simulate various repayment scenarios before ever committing.
If your goal involves paying off existing debt or financing a large purchase, the application process feels remarkably smooth. One standout feature is the ability to perform a “soft pull” credit check. This is a godsend for those who want to shop around without damaging their credit score.
You can view your estimated APR and monthly payment amounts without any risk to your standing. This transparency makes it much easier to compare options and find the perfect fit for your budget.
Pros:
- You can shop for rates without any impact on your credit score.
- The funds are versatile, applicable to anything from debt to home improvements.
- Certain products even offer the perk of cash back rewards.
Cons:
- The sheer breadth of their product line might feel overwhelming if you are searching for a single, simple solution.
4. Together Loans
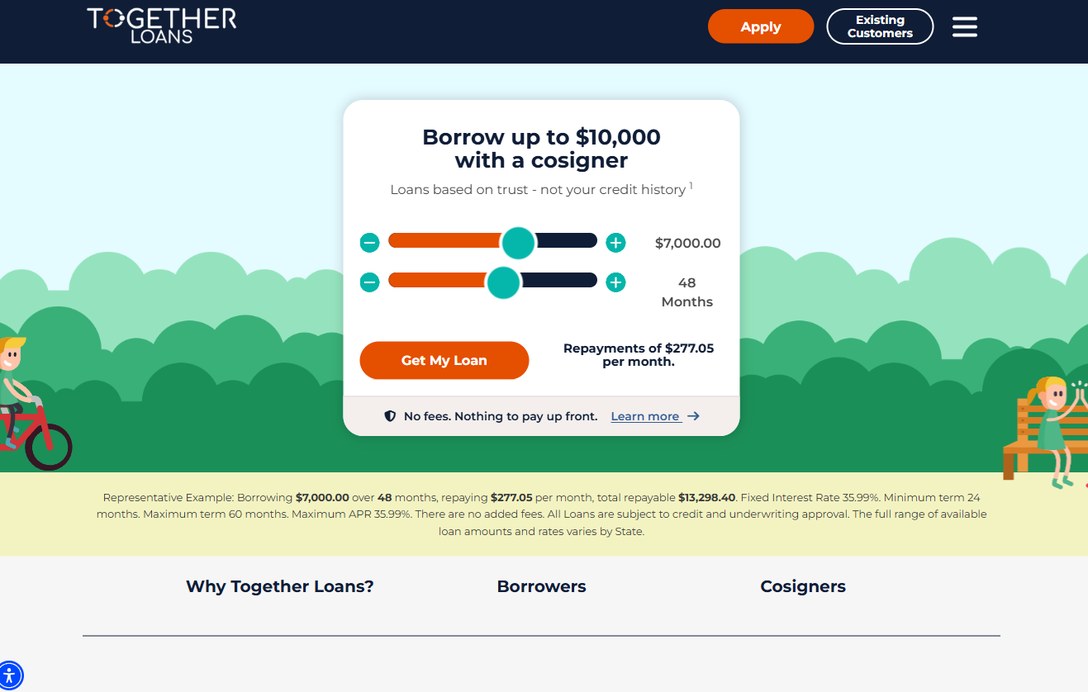
Together Loans breaks the mold by placing a high value on personal trust rather than relying solely on digital metrics. This is a massive advantage for individuals who possess a reliable co-signer but have a less-than-perfect credit history. We all know that life can throw unexpected curveballs.
A single medical emergency or a temporary stint of unemployment can wreak havoc on your score, yet these lenders strive to see the human being behind the numbers. They look at the context of your situation, not just the data points on a screen.
They focus on loans up to $10,000 and move at a blistering pace, frequently issuing approvals within a 24-hour window. If you are facing an urgent bill that cannot wait, this is a very dependable option. Bringing a co-signer into the mix here can unlock much better terms than you could secure solo.
Pros:
- They value personal circumstances and trust over rigid, automated algorithms.
- Their 24-hour approval turnaround is ideal for high-pressure, urgent needs.
- With no upfront fees, the total amount requested is the amount you actually receive.
Cons:
- Be sure to read the fine print, as interest rates can occasionally climb on the higher side.
5. U.S. Bank
For those who find comfort in the presence of a massive, established institution, U.S. Bank is a rock-solid choice. If you are already a customer, you may find the experience particularly seamless. Existing relationships often mean the verification stage moves much faster because your cash flow is already known.
While they might lack the lightning speed of a new fintech startup, they carry the weight and security of a giant infrastructure. Their services range from basic checking accounts to complex wealth management. When you are planning a major milestone like a wedding, that sense of institutional stability is invaluable.
Pros:
- They provide a high level of stability and robust consumer protection.
- Almost every financial service you might need is available under one roof.
- Managing your loans is incredibly simple if you are already using their banking ecosystem.
Cons:
- Their eligibility requirements for personal loans tend to be more stringent than those of niche lenders.
6. MoneyLion
MoneyLion is tailor-made for the smartphone generation. Their mobile app functions less like a banking tool and more like a personal financial assistant, helping you navigate daily spending while simultaneously working to bolster your credit score. It is a modern way to stay on top of your money.
They provide significant funding, with loans reaching up to $100,000, which can facilitate massive life shifts like funding an education. Since they prioritize credit building, they are a fantastic partner for those aiming to eventually move away from the need for a co-signer altogether.
The ultimate goal is to gain the financial strength to stand entirely on your own two feet. Their app makes the journey toward that independence feel much less daunting.
Pros:
- Extremely high loan limits are available for large-scale projects.
- The app is packed with useful tools designed to educate you on credit.
- Navigating the mobile interface is a breeze.
Cons:
- Be aware that certain rapid cash features might carry additional fees.
7. MedLoan Finance
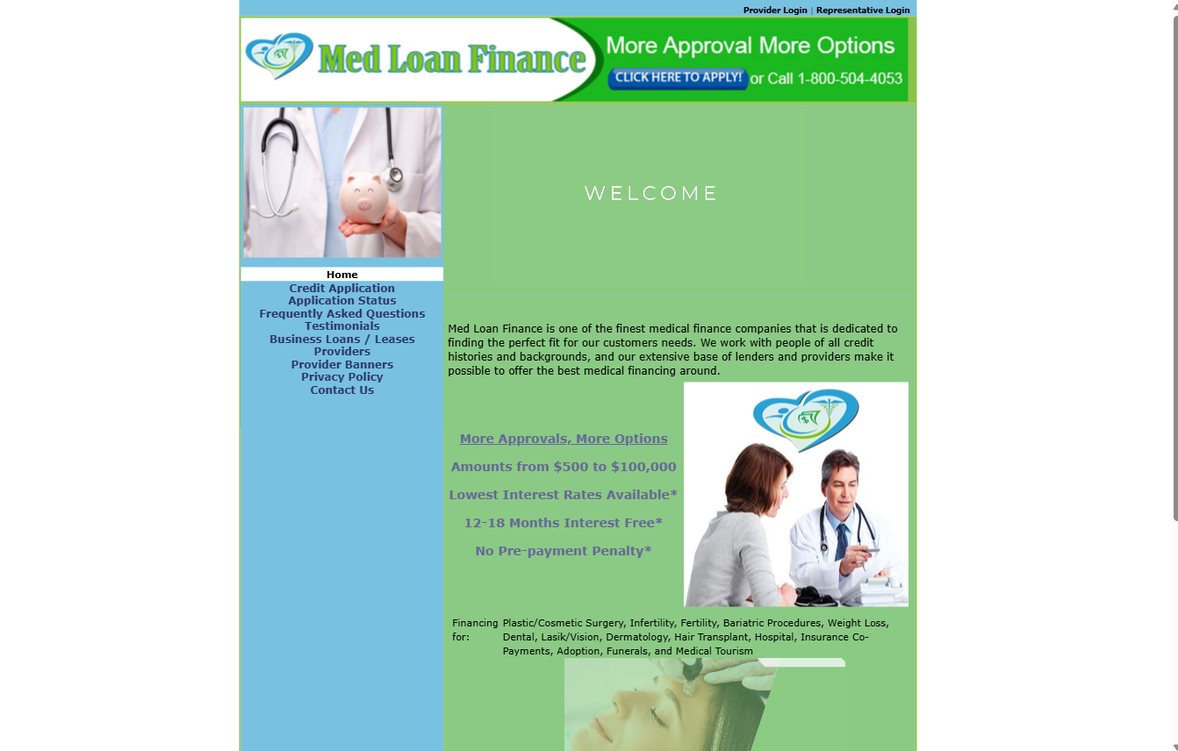
MedLoan Finance exists for one specific mission: tackling medical debt. Whether you are facing a dental procedure, LASIK surgery, or a major operation, they provide funding specifically tailored to the medical landscape. Unlike general lenders, they truly understand the unique timing of healthcare costs.
They offer a variety of loan amounts and even provide certain interest-free windows for specific timeframes. If you have a surgery on the horizon, utilizing a specialist can be far more cost-effective than taking out a generic, high-interest personal loan.
Pros:
- They are true specialists for elective medical and dental procedures.
- Interest-free options for 12-18 months can result in massive savings.
- They are equipped to handle large medical expenses totaling up to $100,000.
Cons:
- The funds are restricted; you cannot use this capital for any non-medical expense.
The Weight of the Co-signer’s Responsibility
Stepping into the role of a co-signer is no small feat; it is a massive commitment that carries significant legal weight. When a loved one puts their name on that contract, they are doing much more than offering a character reference. They are essentially stepping into your shoes regarding the financial obligation.
Should you fall behind on your installments, the lender won’t just knock on your door. They have every legal right to demand the total balance from your co-signer. This includes any accrued interest and those pesky late penalties that tend to snowball quickly. It is a high-stakes gamble for them.
If the debt remains unpaid, the fallout can be quite brutal for the person who helped you out. They could face sudden lawsuits or even have their wages garnished by a court order. Beyond the immediate stress, their credit score could take a devastating hit that takes years to repair.
Even in a perfect scenario where you stay current on every single payment, their credit profile still feels the heat. This sizable loan will appear directly on their personal credit report. It essentially acts as a shadow hanging over their own financial future and stability.
When they eventually decide to buy a new home or a vehicle, banks will scrutinize their ability to repay. Lenders often view this co-signed debt as a looming liability that could jeopardize their own ability to meet monthly obligations. Placing this kind of burden on someone close to you is a heavy cross to bear.
Getting Ready for Your Co-signer Request
Securing a loan approval isn’t about luck; it is about having your ducks in a row. You shouldn’t just walk into an office with your driver’s license and hope for the best. Instead, you need a bulletproof strategy for managing your future debt payments.
Think of this as a rehearsal for a major performance. You want everything to go smoothly without any sudden surprises. We recommend completing the following tasks before you even touch that application form:
- Draft a Repayment Schedule: Create a detailed timeline for your monthly installments. It is wise to build a financial cushion to account for those unpredictable months when your wallet might feel a little lighter.
- Verify the Co-signer’s Credit Profile: Most financial institutions look for a credit score sitting between 670 and 700 for your partner. If their rating is subpar, you might be spinning your wheels.
- Organize Your Financial Records: You will inevitably need to provide W-2 forms, recent pay stubs, and residency verification. Tucking these into a dedicated folder prevents unnecessary delays during the review process.
- Review the Terms Collectively: Never treat the legal fine print like junk mail. Sit down side-by-side with your co-signer to thoroughly examine the specific consequences of a single missed payment.
Managing the Co-signer Dynamic
Sitting down for a heart-to-heart is the first step before requesting a signature. You must be brutally candid about the legal obligations involved. It isn’t just a favor; it is a heavy weight they are helping you carry. If life throws you a curveball and you miss payments, their financial reputation is on the line right alongside yours.
Tension over debt has burned bridges in many households. Make sure they realize that their credit rating is directly tied to your repayment habits. It is better to face a difficult truth now than to let resentment fester later when the bills come due.
Some people treat a co-signer like a mere checkbox on an application. That is a dangerous misconception. Banks view these individuals as primary guarantors, meaning they are just as liable for the debt. If their credit profile is barely superior to yours, the lender might reject the application entirely or demand much higher interest rates.
If the rate doesn’t drop, you’ve essentially gone through all that social trouble for nothing. A co-signer should serve as a tool to lower your costs. If they don’t actually improve your terms, you are simply adding a layer of risk to your life without getting any real financial benefit.
Resist the urge to grab a larger loan than your budget allows just because you have extra leverage. Interest can snowball into a mountain of debt if you aren’t careful. It is easy to get carried away when a higher limit is suddenly available.
Remember, the goal is to secure a better rate, not to increase your spending power. Use the extra creditworthiness to make the loan more affordable, rather than using it to fund a lifestyle that your income cannot truly support in the long run.