

Uncategorized @vi
Find the Best Flooring Financing Deals for Your Next Home Remodel
Find the Best Flooring Financing Deals for Your Next Home Remodel
Last updated: 2026-10-16
Taking on a home makeover often feels like a heavy weight on your shoulders. You might notice your old linoleum curling at the edges or your hardwood losing its luster. Suddenly, you realize that replacing those floors is a giant mountain to climb.
It is easy to get caught off guard by the final bill for new laminate or tile. Between expensive porcelain and high-end engineered wood, the prices climb fast. Once you add in subfloor work and underlayment, the total price tag can certainly give anyone a bit of sticker shock.
Selecting a payment strategy is just as vital as picking out your favorite color palette. You might just need a quick infusion of cash for a minor patch. Perhaps you are planning a full-scale overhaul of every single room in your house.
The landscape of lending in 2026 provides many different routes to reach your goal. Choosing wisely is the secret ingredient here. Your choice today determines if this project feels like a victory or a heavy financial burden.
- FastLendGo
- HFS Financial
- Acorn Finance
- Wisetack
- Affirm
- Floor Daddy
Comparing Leading Financing Providers for Your Remodel
Choosing a creditor involves much more than simply hunting for the lowest percentage on a digital dashboard. You must weigh how quickly funds land in your pocket against the sheer mental toll of the paperwork. A low rate can be a deceptive siren if the repayment period stretches out far longer than expected.
Consider a $10,000 debt at a 10% interest rate for 3 years, which totals roughly $1,750 in interest. Contrast that with a 7-year term for that same amount, which can drive interest costs up toward $4,000. Balancing the immediate relief of a small monthly bill against the total price of debt is a delicate dance.
Our analysis prioritized three main pillars: speed of funding, ease of use, and the potential impact on your credit report. We looked for providers that serve everyone, from those with gold-standard credit to folks just trying to keep their heads above water. We favored companies offering blunt, clear disclosures over those burying sneaky costs in the fine print.
| Provider | Funding Range | Credit Profile | Main Benefit |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Good to Bad Credit | Rapid cash delivery |
| HFS Financial | see site | No equity required | Low-fixed rates |
| Acorn Finance | see site | Good and Bad Credit | $0 dealer fees |
| Wisetack | see site | Soft credit check | Up to 24-month 0% APR |
| Affirm | see site | No credit check options | Flexible payment plans |
| Floor Daddy | see site | see site | 48 Months 0% Financing |
1. FastLendGo
Think of FastLendGo as a financial safety net for sudden home repair needs. It is a lifesaver if you need to scan various local personal loan options quickly without a mountain of bureaucracy. If a pipe bursts or a stair step breaks, this is your go-to when speed matters more than hunting for the absolute cheapest rate. (fastlendgo.com)
This platform accommodates almost any financial situation. Whether you need a $500 patch-up job or a $5,000 overhaul, the system is built to match high-earners and those struggling with credit alike. Their matching logic helps bridge the gap between your current score and what private lenders are looking for.
The Upsides:
- Loan amounts scale from $500 up to $5,000 and more.
- Accepts a wide variety of credit scores, including fair or poor.
- Provides a quick way to compare various personal loans online.
The Downsides:
- Top-tier credit users might find better rates elsewhere.
2. HFS Financial
HFS Financial is a prime choice if you want to avoid the complexities of equity-based borrowing. It is a fantastic option for homeowners who want pretty floors without using their property as collateral. Since traditional Home Equity Lines of Credit (HELOCs) put your house on the line if you default, this alternative keeps your home’s title separate from the loan.
The real magic here is how fast you can get a “yes.” They aim for lightning-fast approvals, moving you from the “thinking about it” stage to the “installing it” stage before a bank would have even finished your paperwork. This is a blessing when your contractor is ready to swing a hammer but you’re waiting on funds.
The Upsides:
- You do not need any home equity to qualify.
- Fixed rates offer long-term peace of mind.
- The approval process is geared toward speed.
The Downsides:
- Fixed rates may lack the flexibility of variable rates in shifting markets.
3. Acorn Finance
Acorn Finance acts as a shield against those pesky “extra costs” often hidden in contractor quotes. They excel at pairing customers with lenders so that dealer fees don’t drain your renovation budget. Rather than letting a contractor tack on a 10-20% surcharge for using their preferred lender, Acorn facilitates direct consumer-to-lender connections.
A major perk is checking personalized rates using only a soft credit inquiry. This is a huge relief for anyone terrified of seeing their credit score take a dip before they even know if they can afford the project. You can map out your budget before even calling a professional for a formal estimate.
The Upsides:
- Consumers are spared from paying dealer fees.
- Soft checks allow for rate shopping without hurting your credit.
- They maintain an excellent reputation for customer service.
The Downsides:
- Because they work with many lenders, interest rates can fluctuate significantly.
4. Wisetack
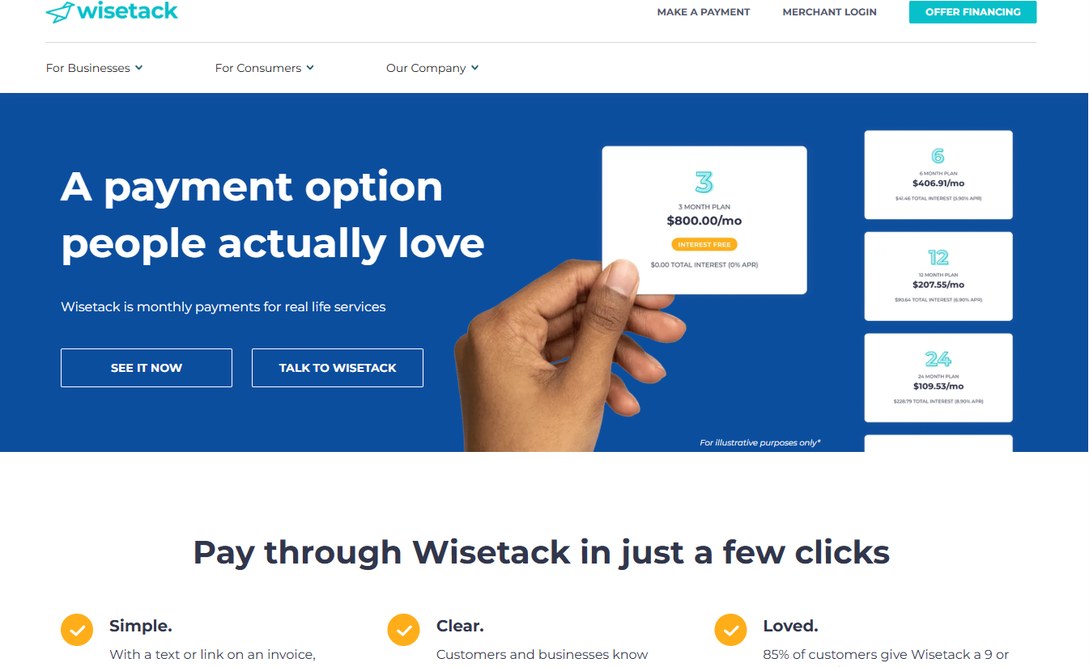
Wisetack is a darling of the service industry because it weaves itself perfectly into the existing merchant-client relationship. It is less of a standalone bank and more of a seamless transaction tool. For the homeowner, this means less digging through bank apps and more directness in your payment workflow.
If you want to settle your flooring bill via a quick text or an invoice link, this is the tool for the job. The 24-month 0% APR option is a massive help for those wanting to spread out costs without the sting of interest. This works beautifully for medium-sized tasks, like refinishing a single large room.
The Upsides:
- Approvals are incredibly swift, often taking just 60 seconds.
- Offers 0% APR windows for up to 24 months.
- Boasts high marks for user satisfaction.
The Downsides:
- Availability and specific terms rely on your contractor’s setup.
5. Affirm
Affirm has become a giant in the “Buy Now, Pay Later” landscape. It is incredibly convenient for smaller jobs or purchasing supplies from major retail partners. If you’re mid-DIY project and suddenly realize you need $2,000 more in luxury vinyl, Affirm is often the path of least resistance.
The versatility here is hard to beat. You can opt for interest-free windows for short durations or choose longer, low-impact monthly payments. The process is remarkably transparent; you see your total cost upfront, so there are no nasty surprises or shifting interest rates halfway through your payment schedule.
The Upsides:
- Total transparency regarding interest with no hidden fees.
- Flexible options including interest-free periods for certain buys.
- User-friendly experience through web or mobile app.
The Downsides:
- Not every local flooring installer is set up to accept Affirm.
6. Floor Daddy
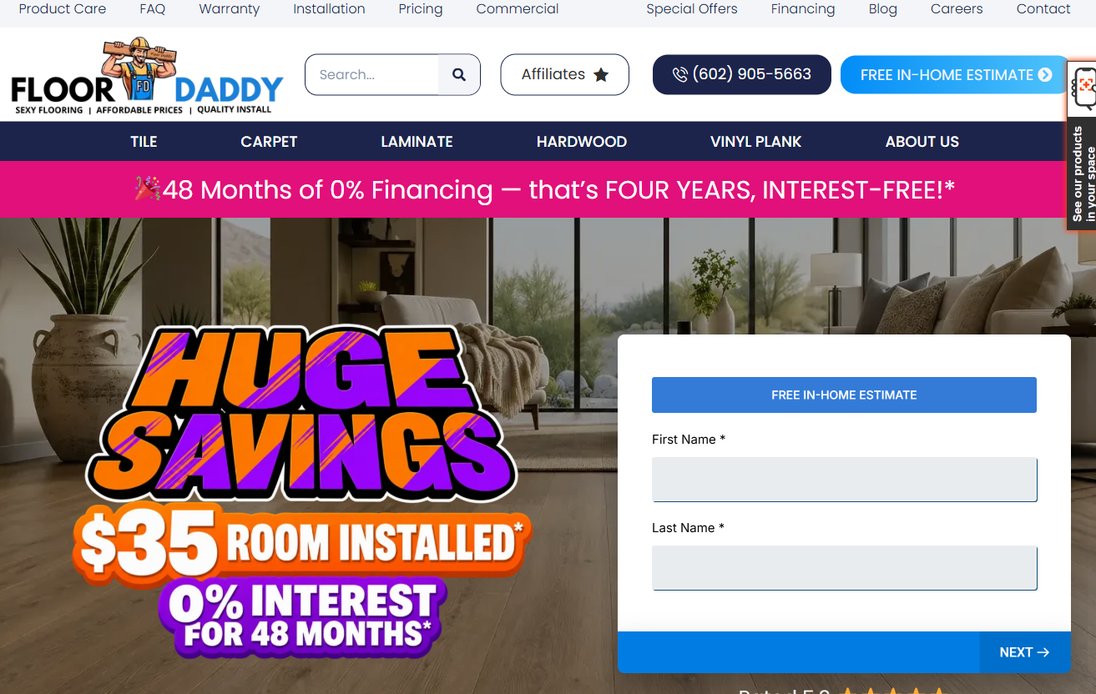
Floor Daddy is a specialized local player that focuses on the physical labor as much as the financing. It is a perfect “all-in-one” solution for those who want their payment plan and their installation crew to be one and the same. This avoids the nightmare of having floor materials sitting in your driveway while you’re broke for the labor.
They offer a rare 48-month 0% financing option that is a real game-changer. Spreading a cost over four years without interest makes massive renovations feel much more manageable. For a $10,000 project, a $208 monthly payment is a far more digestible bite than a massive lump sum or a high-interest card bill.
The Upsides:
- Extensive 48-month interest-free financing available.
- Covers professional prep and specialized dustless removal.
- Maintains a stellar 5.0-star rating.
The Downsides:
- The financing is likely exclusive to their specific installation services.
Evaluating Your Borrowing Options
Before signing any paperwork, you must grasp the fundamental distinctions between the different lending models available to you. Selecting an ill-fitting loan structure is like wearing shoes that are two sizes too small; it might work for a moment, but it will eventually cause significant pain.
Poor decisions in this area often lead to sudden tax headaches or a never-ending spiral of interest payments. You really want to avoid walking into a debt trap that follows you for years. Take a moment to breathe and weigh your options carefully before pulling the trigger.
The chart below serves as a roadmap to help you navigate these choices. Use it to figure out which financial path aligns with the actual scope of your upcoming flooring renovation. Whether you are just replacing a rug or tearing up every inch of hardwood, there is a specific tool for the job.
| Lending Model | Ideal Use Case | Primary Danger | Time to Access |
|---|---|---|---|
| Personal Loan | Total freedom to pay DIY supplies or various contractors | Steep interest if credit scores are low | 1–3 Business Days |
| 0% APR Financing | Mid-sized projects using high-end materials | Failure to pay in full before the promo period ends | Instant (at checkout) |
| Home Equity Loan | Major, whole-home renovations | Your property acts as collateral for the debt | Weeks to Months |
| Buy Now, Pay Later | Material purchases and small repairs | Simple to overspend on small items | Immediate |
As you weigh these choices, keep your “exit strategy” in the back of your mind. If your plan involves moving to a new house in two years, avoid the trap of long-term home equity loans. Such debt attaches a lien to your title, creating a messy hurdle when you try to close a sale.
However, if you intend to stay put for the next decade, a fixed-rate personal loan is a much smoother ride. It offers a predictable, stable method for boosting your home’s worth. You won’t have to worry about the roller coaster of variable interest rates keeping you up at night.
Decoding Your Loan Options
Don’t get blinded by a small monthly installment. While a tiny number on a monthly statement looks tempting, a five-year term can drain your wallet much faster than a quick twelve-month plan. You need to look at the bigger picture.
Always demand the “Total Cost of Borrowing” before signing the dotted line. This specific figure tells you the real price of your debt. When you are pitting two lenders against each other, this is the only metric that actually counts.
It is a classic trap to think that “no credit check” means zero impact on your profile. Many companies offer a way to view rates without a hard inquiry, which is a lifesaver. Use these soft-pull tools to scout the market without any risk to your score.
Be careful with your timing during the application process. A solitary hard inquiry might shave 5 points off your score, which isn’t the end of the world. However, if you apply everywhere at once, lenders might see “credit hunger” and hike your interest rates through the roof.
Wait until your renovation blueprint is set in stone before you finalize your borrowing amount. Once the crew arrives and the old carpet is ripped out, the game changes. It is a nightmare trying to increase a loan once the installation is mid-way through.
Unexpected hiccups are a part of the job, like finding rotted subfloors or wonky joists once the floor is up. To stay afloat, I always suggest adding a 15-20% “contingency buffer” to your total request. Building in this safety net prevents a massive financial headache later.