

Uncategorized @vi
Top 6 Options for Plastic Surgery Loans for Bad Credit
Top 6 Options for Plastic Surgery Loans for Bad Credit
Last updated: 2026-10-16
Stepping into a consultation room ought to feel like a fresh start for your confidence. It shouldn’t feel like you are falling into a deep financial pit. Too many patients find themselves staring at a life-changing procedure while their credit score remains stuck in the gutter.
When your aesthetic aspirations clash with a tight bank account, the weight can feel unbearable. It is a heavy mantle to wear when your desired physical changes feel light-years away from your current economic reality.
The stress of taking on debt frequently drowns out the joy of an upcoming makeover. This mental strain often creates a feedback loop of worry that keeps people from getting necessary care. It is quite difficult to concentrate on your post-op recovery when you are losing sleep over how to settle the bill.
Securing funds for cosmetic enhancements involves looking much deeper than the glossy advertisements. You require a financing partner that truly grasps the sensitive nature of medical borrowing. This is particularly vital if your financial history is a bit of a rollercoaster.
Big national banks usually follow a strict playbook that leaves little room for error. They often turn away anyone with a high debt-to-income ratio or even one missed payment on their record. Their rigid requirements can make a dream surgery feel like an impossible mountain to climb.
We have put together a selection of the premier choices available throughout 2026. These options are specifically curated for individuals navigating the complicated maze of reconstruction and medical financing.
- JetzLoan
- Cherry
- CareCredit
- United Credit
- Acorn Finance
- MedLoan Finance
Our Criteria for Selecting Medical Loan Providers
When we began our search, we kept a sharp eye out for options that welcome patients with bruised credit scores. Finding a lender is a walk in the park if your history is spotless. However, hunting down companies that won’t turn you away at the gate is a much tougher nut to crack.
Our team hunted for lenders known for high acceptance rates and clear-cut contracts. We wanted to avoid those nasty “gotcha” moments that pop up in the fine print. It is vital to know exactly what you are signing before you commit to a procedure.
A classic trap in the world of medical lending involves a sudden jump in interest rates once a teaser deal expires. You might also run into sneaky origination fees that weren’t mentioned during your initial talk. It’s a headache no one needs, especially after you’ve already dropped a non-refundable deposit.
Finding out you are ineligible after your surgery is scheduled is a recipe for disaster. We looked for providers that prioritize transparency so you aren’t left out in the cold. We wanted to ensure that your financial journey is as straightforward as your surgeon’s plan.
Getting your funds quickly was another non-negotiable pillar of our evaluation process. We favored services that deliver rapid decisions, making the transition from your consultation to the surgical suite seamless. We didn’t want patients waiting weeks while their medical plans sat in limbo.
We also dug deep into how each lender handles credit inquiries. Our goal was to find “soft pull” options that allow you to browse different rates without hurting your score. This lets you shop around with peace of mind, knowing your credit stays protected while you compare deals.
| Provider | Loan Limits | Approval Timeframe | Credit Inquiry Effect |
|---|---|---|---|
| JetzLoan | $500 – $35,000 | Under 24 hours | Soft pull only |
| Cherry | Check website | Right after approval | No hard inquiry |
| CareCredit | Check website | Decisions are instant | Prequalify without impact |
| United Credit | Check website | Check website | Check website |
| Acorn Finance | Check website | Check website | No impact on score |
| MedLoan Finance | $500 – $100,000 | Check website | Check website |
Navigating Interest Rates and Loan Structures
Before you sign any paperwork, you need to grasp how the math actually works for your wallet. Most medical financing options split into two distinct camps: installment-based loans or revolving credit lines. Think of revolving credit, which is how CareCredit operates, as a digital revolving door for your funds.
You start with a set spending limit that resets as you settle your balance. This flexibility is a lifesaver if you are undergoing a series of dermatological sessions or lengthy orthodontic adjustments. However, it is a double-edged sword that requires a steady hand. If you stumble with your payments, the interest can snowball out of control.
On the other hand, installment loans, which you might find through MedLoan Finance or JetzLoan, act differently. They hand you a single lump sum to cover your costs immediately. You then chip away at that debt through set, predictable monthly installments over a specific period.
For a singular, major transformation like a tummy tuck or a rhinoplasty, this predictability is worth its weight in gold. You won’t be surprised by fluctuating amounts every month. It brings a sense of order to what is already a stressful financial moment.
When you are shopping around, don’t let a tiny monthly payment trick you into a bad deal. Always hunt for the Annual Percentage Rate (APR) to see the true cost of borrowing. A small monthly bill might look tempting at first glance, but if that debt is stretched across 60 months, you could end up paying twice what the surgery originally cost due to interest.
Leading Options for Medical Funding
1. JetzLoan
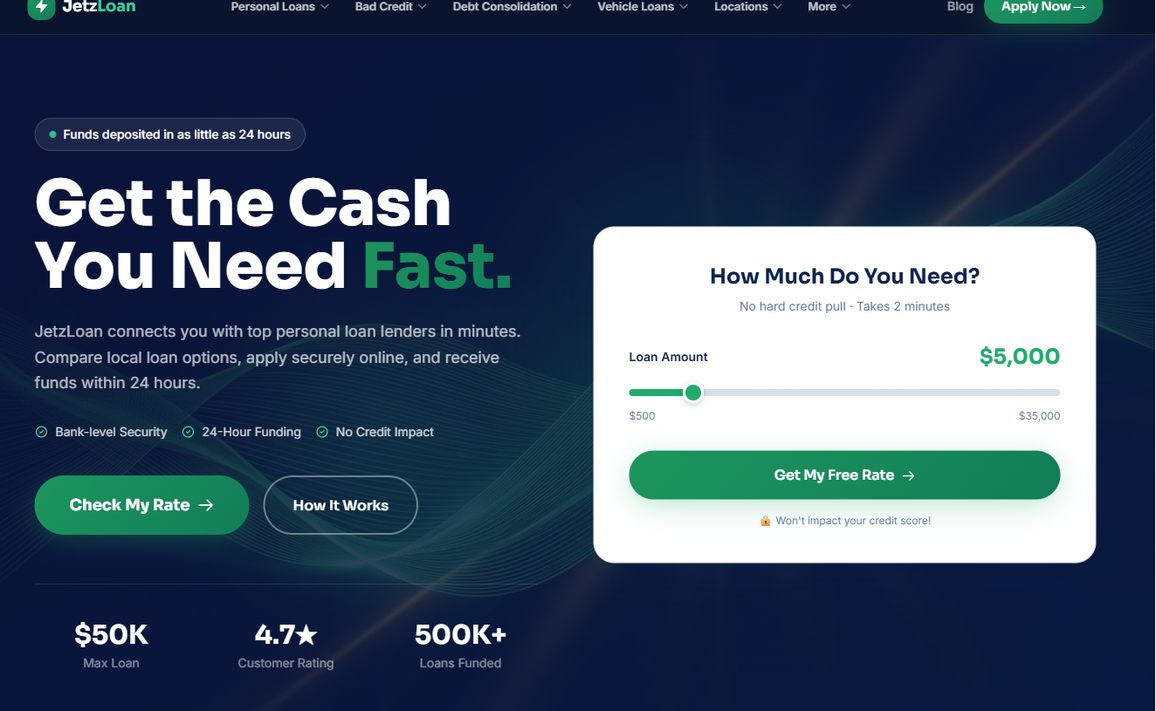
When time is of the essence, JetzLoan serves as a rapid financial conduit for your healthcare expenses. They prioritize velocity, aiming to deposit funds into your bank account within a 24-hour window. This makes them a lifesaver for sudden dental emergencies or unplanned surgical needs that require immediate attention. (jetzloan.com)
Navigating their interface is a breeze, allowing you to peek at your potential terms in about two minutes. Since they utilize a “soft pull” mechanism, you can window-shop for rates without worrying about a dip in your credit score. It is a low-risk way to see what you qualify for before diving into a formal request.
For those hunting for substantial sums up to $35,000, this service bypasses the red tape that usually plagues traditional banking. It is a streamlined solution for when you simply cannot afford to wait on a slow-moving institution.
- Pros: Rapidly deployed funds, checking rates won’t hurt your score, limits reach $35,000.
- Cons: The ceiling for borrowing might be lower than niche medical-only lenders.
2. Cherry
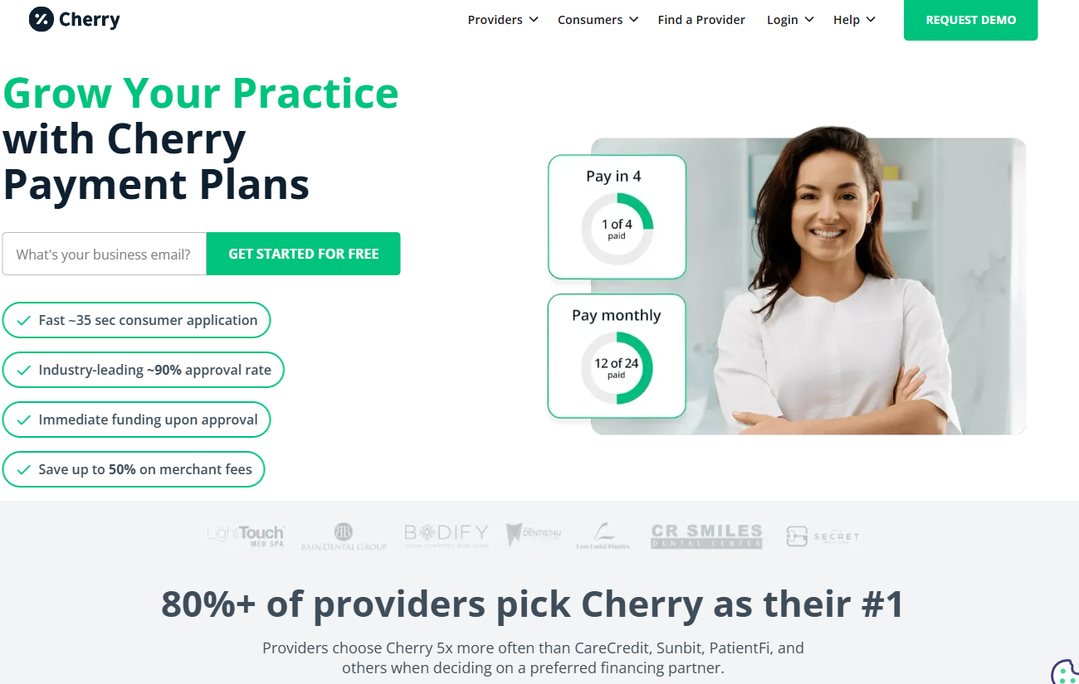
Cherry has carved out a massive niche in the healthcare landscape, earning the trust of tens of thousands of medical professionals. It is frequently the top pick for patients who crave a hassle-free transaction. Their application is incredibly swift, often concluding in just 35 seconds, which is a godsend for someone rushing between various appointments.
If you are looking for high success rates, this is a strong contender. The sheer ease of their system can lift a heavy weight off your shoulders during stressful medical journeys. Doctors often prefer this method because it integrates smoothly into the office checkout process, making the whole financial side of things feel effortless.
Think of it as a digital wallet specifically engineered for the clinical world. It strips away the awkwardness of discussing large sums of money in a doctor’s office, allowing your focus to remain entirely on healing.
- Pros: Rapidly approved, high success rates, incredibly quick application.
- Cons: Availability depends on whether your specific doctor participates in their network.
3. CareCredit
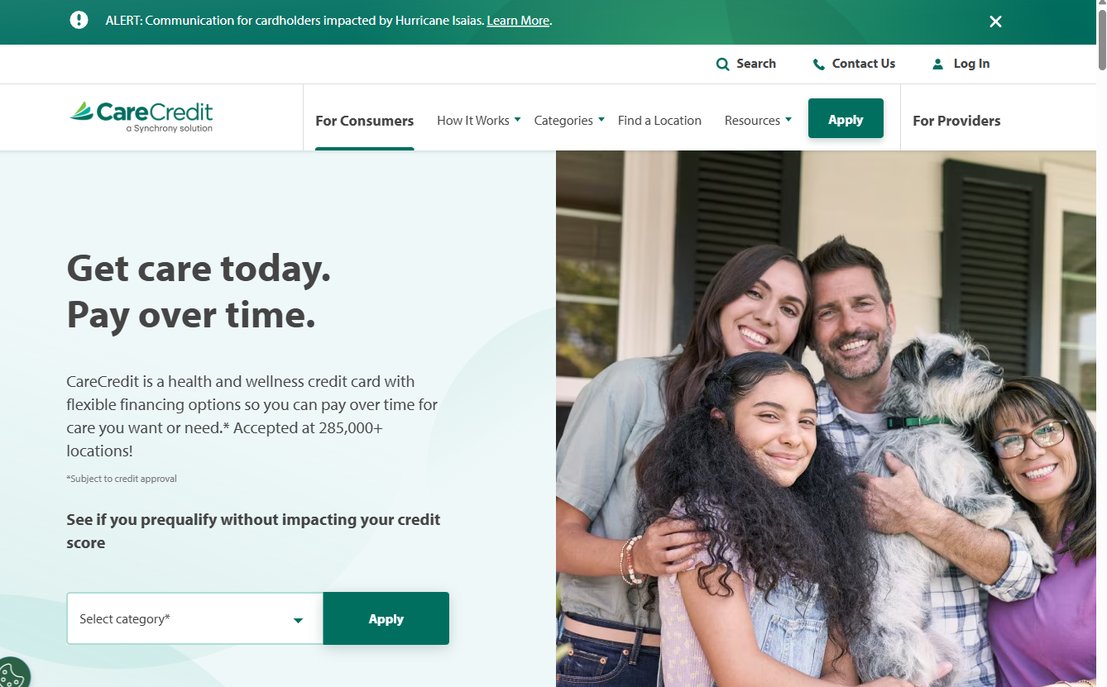
A giant in the wellness world, CareCredit is widely accepted at hundreds of thousands of different locations. It operates essentially as a specialized credit card for health-related purchases. This versatility means you can use it for much more than just aesthetic upgrades; it covers everything from vision and physical therapy to even veterinary care.
The real magic of this card lies in its flexibility regarding repayment. It allows you to spread out costs, which helps protect your monthly cash flow while you are convalescing. Many users take advantage of promotional periods—ranging from 6, 12, or 24 months—to pay zero interest.
However, it is vital to treat those “no-interest” windows with caution. If you fail to clear the balance before the deadline, interest is often applied retroactively to the full purchase price. This can lead to a sudden, staggering debt that lands like a bombshell on your finances.
- Pros: Massive merchant network, versatile uses, instant credit decisions.
4. United Credit
Rather than just hunting for quick wins, United Credit strives to cultivate lasting connections with its clients. They act as a gateway to a vast marketplace of various lenders, which provides a safety net for people with diverse financial histories. Whether your credit is stellar or quite poor, they aim to find a match.
They move away from the rigid, “one-size-fits-all” model by looking at the person behind the paperwork. Their expansive lender network means they can often unlock doors that a single traditional bank might slam shut. This is a huge win for freelancers or anyone with irregular, non-traditional income streams.
If you want a lending experience that feels a bit more human and less like a machine, this is a great direction. They focus on finding a path forward by considering your whole life, not just a single numerical score.
5. Acorn Finance
Acorn Finance takes a slightly different route by targeting significant medical or home improvement projects. They act as an aggregator, bringing various specialized lenders to a single dashboard to help you compare rates. The best part? You can shop around without the sting of a credit score hit.
Users frequently rave about the convenience of their SMS and email-based application methods. Even if your credit history is a bit bumpy, they work to pair you with a provider who can accommodate your unique circumstances.
This makes them a premier choice for complicated, multi-stage medical journeys. If your procedure involves several different specialists or complex reconstructive work, they can keep all your financing centralized and manageable.
6. MedLoan Finance
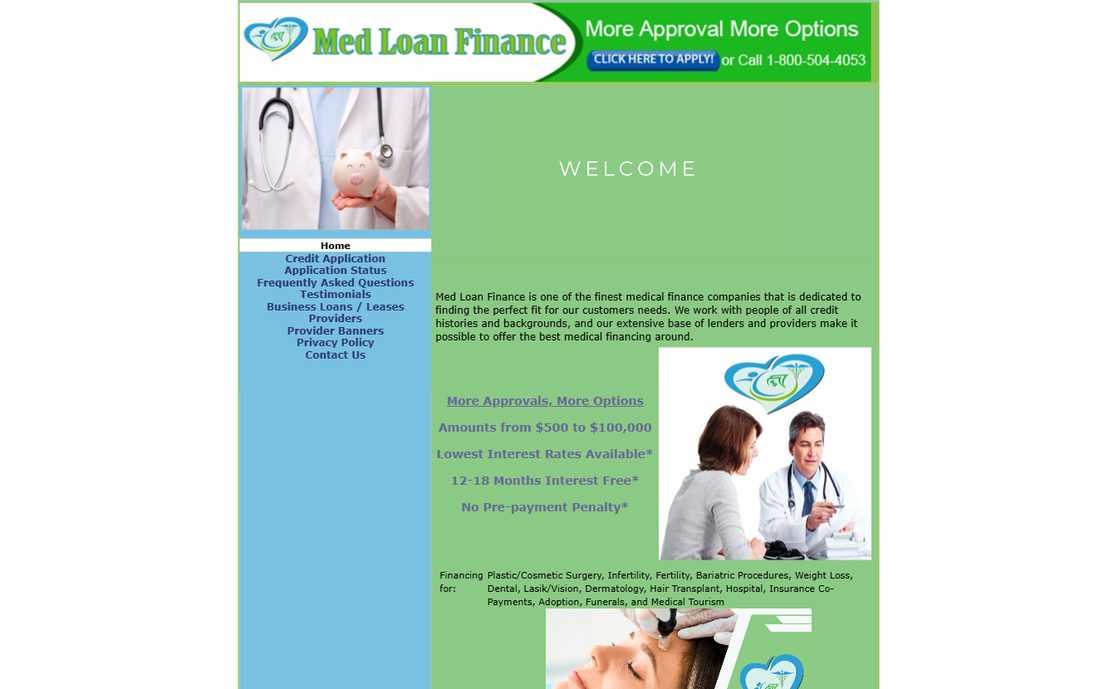
MedLoan Finance is a specialist in the medical arena, with a deep focus on dental, bariatric, and aesthetic surgeries. They utilize specialized medical underwriting, which allows them to assist individuals regardless of their past credit hurdles. They aim to provide what many consider the top-tier medical financing available.
With borrowing limits reaching as high as $100,000, they are a heavyweight option for major reconstructive transformations. They truly understand that medical recovery isn’t instant, offering terms that can include interest-free windows for 12 to 18 months.
This can be an absolute lifesaver during the recovery phase, especially if you need to take time away from work. It provides a vital financial cushion exactly when you might be feeling most vulnerable.
Mapping Out Your Funding Strategy
Picking a creditor involves more than just chasing the smallest interest percentage. You really need to hunt for a collaborator that aligns perfectly with your particular medical goals. It is a bit like tailoring a suit; the fit must be precise for the occasion at hand.
If you are looking at a minor touch-up and need cash quickly, a rapid-disbursement service like JetzLoan might be your golden ticket. These options are built for speed when you want to get things moving without a long wait.
On the flip side, major reconstructive operations demand much heavier lifting. For these larger life changes, the substantial credit ceilings provided by MedLoan Finance might be the only way to cover the whole bill, including the surgeon, facility costs, anesthesia, and your recovery care.
Shielding Your Financial Reputation
Don’t go throwing applications around like confetti. Making numerous hard credit pulls within a tight timeframe is a recipe for disaster. This behavior sends out a signal of desperation to potential lenders, which can cause your credit score to take a nosedive.
Every single time a company conducts a “hard pull” to reach a definitive verdict, they leave a permanent mark on your history. Think of these marks as digital footprints that tell a story about your financial behavior.
To play it smart, always start with “pre-qualification” tools or options labeled as having “no impact” on your score. This allows you to weigh your actual choices without paying a single cent in penalties or risks.
Building this mental map of potential debt before you sign anything is vital. As the old saying goes, you should always understand the true cost of borrowing before you actually spend the cash. It keeps you in the driver’s seat of your own destiny.
Dodging Hidden Interest Traps
When a lender advertises “interest-free” windows, proceed with extreme caution. While promotional periods are tempting, they often come with a catch that can bite you later. Missing a single due date can trigger a massive financial headache for your budget.
If you fail to clear the balance by the agreed deadline, you might face retroactive interest charges. This isn’t merely a minor nuisance; depending on your total principal, it could end up costing you thousands of dollars in unexpected debt. It can turn a dream into a nightmare overnight.
To stay safe, keep a meticulous calendar and consider setting up autopay to prevent any accidental slips. You ought to approach your medical financing with the same level of discipline and seriousness that someone would use for a mortgage.