

Uncategorized @vi
Top Rated Sources for Bad Credit Loans Louisiana Fast Approval
Top Rated Sources for Bad Credit Loans Louisiana Fast Approval
Last updated: 2026-10-16
Managing your money in the Pelican State often feels like navigating a dense bayou mist without any help from your headlights. A lot of folks around here possess credit ratings that fail to capture their true character or their genuine capacity to settle a debt.
When an unforeseen medical cost or a broken vehicle suddenly appears on your counter, you crave straightforward solutions. You shouldn’t have to wade through a swamp of uncertainty when you are just trying to keep your head above water.
Whether you are navigating the lively avenues of New Orleans or resting in a peaceful inland parish, financial stress is a common burden for industrious residents. Identifying a financier that recognizes the nuances of a poor credit score is your first step toward recovery.
This selection examines various avenues, ranging from community-based credit unions to modern online platforms. Every path serves a unique purpose for those seeking a way out of a tight spot.
Some individuals require a rapid burst of cash to survive until the next payday. Others are searching for a structured, long-term strategy to combine several mounting debts into one manageable payment.
Selecting the ideal provider involves more than just glancing at the starting interest percentage. You must scrutinize the specific repayment timelines, the fine print, and the overall contractual requirements before signing anything.
- FastLendGo
- Coastline Credit Union
- LightStream
- United Finance
- Addition Fi
- GadCapital
What Lenders Look for in Louisiana Residents
Finding the right money source is about more than just sprinting toward the quickest “yes.” Across the Pelican State, financial institutions weigh several variables, including the stability of your paycheck and your specific debt-to-income ratio. While your credit score plays a massive role in the equation, it certainly isn’t the only piece of the puzzle.
Some companies actually place a higher premium on your employment history than on a number on a screen. They want to see if you have a reliable way to settle your debts over time. It is like looking at a person’s character rather than just their bank balance.
For example, you might be asked to provide bank records covering your most recent three months. This helps them confirm that your income flows in a predictable rhythm. Such proof of steady cash flow can actually outweigh a sudden drop in your FICO score triggered by a solitary, unexpected medical expense.
When life throws a curveball, time becomes your most precious commodity. Imagine your car’s transmission gives out on a Friday afternoon, leaving you stranded. If you need that vehicle running by Monday to keep your job, waiting fourteen days for an answer feels like an eternity.
Our team evaluated these specific lenders by looking at their accessibility for individuals with bruised credit profiles. We also analyzed their maximum lending limits and how quickly they transition from a submitted application to actual cash in your pocket. Speed is often the difference between relief and a crisis.
As you weigh your options, always scrutinize the “Total Cost of Borrowing.” Do not just look at the interest rate. You must factor in any administrative costs or origination fees that might sneak into the deal during the final closing stages.
| Provider | Available Funding | Interest Percentage | Speed of Payout | Eligibility Standards |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | see site | see site | Bad/Fair Credit |
| Coastline Credit Union | see site | see site | see site | see site |
| LightStream | see site | 9.99% – 24.94% APR | Next day | Excellent Credit |
| United Finance | Up to $20,000 | see site | see site | see site |
| Addition Fi | see site | see site | see site | see site |
| GadCapital | $100 – $5,000+ | see site | Instant | No Credit Check |
Top Financial Choices for Louisiana Residents
1. FastLendGo
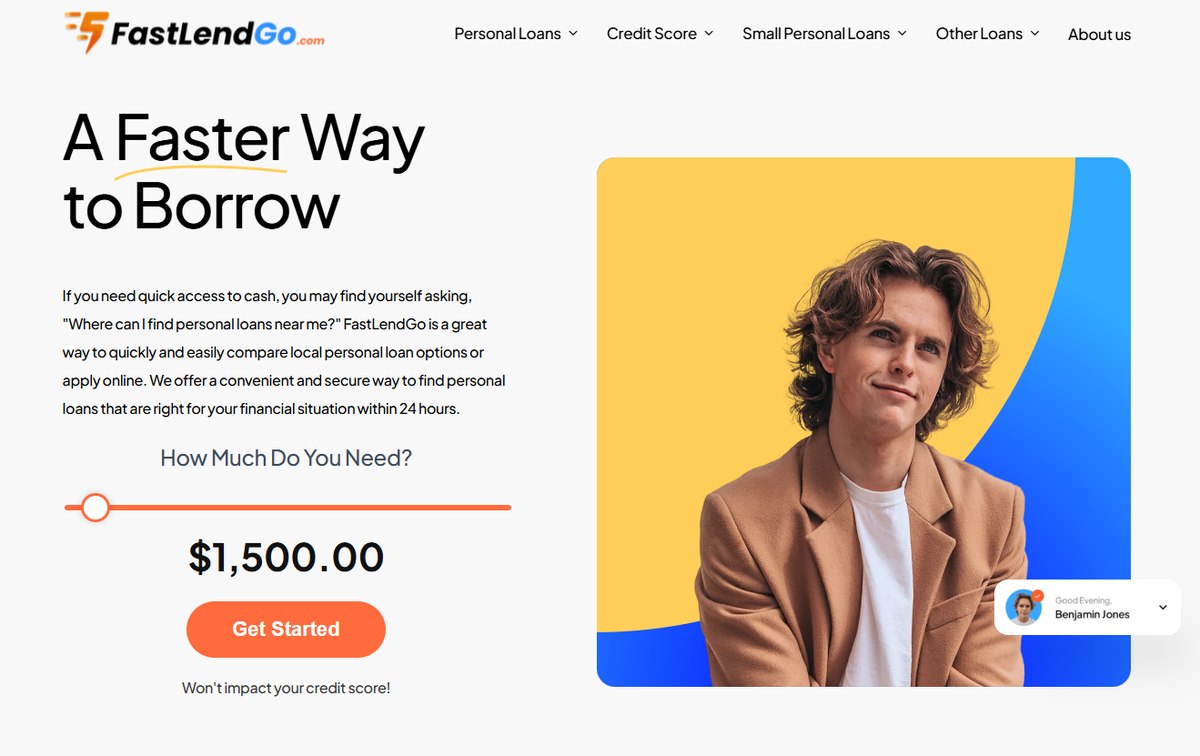
If you have ever felt like a ghost in the eyes of major national banking institutions, FastLendGo might be your lifeline. They focus their expertise on personal financing options tailored specifically for individuals navigating the choppy waters of a bruised credit history. Their digital platform is designed to strip away the complexity of comparing various rates.
Forget about burning gas driving from one parish to another just to find a specialist who will talk to you. You can weigh your financial alternatives right from the comfort of your own sofa using fastlendgo.com. It is a modern solution for a modern age, cutting through the red tape that often plagues traditional lenders.
Whether a sudden dental crisis strikes or your roof starts leaking during a storm, they have specialized solutions ready. Their lending range is quite flexible, covering everything from a quick $500 fix to larger requests of $5,000. It is built for speed, making it an excellent bridge when you are caught between a sudden emergency and your next payday.
Pros:- Focuses on fair and bad credit scenarios.
- Provides targeted loans for medical or vehicle repairs.
- Features a simple online comparison system.
- Does not provide the local, small-town feel of a credit union.
2. Coastline Credit Union
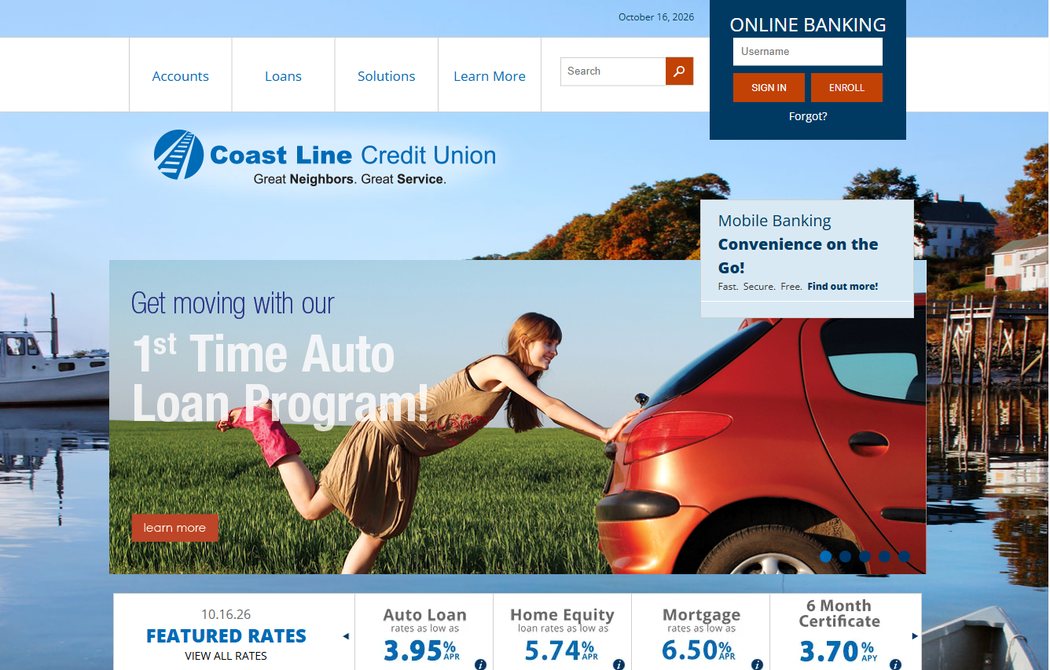
Think of credit unions as the unsung heroes of the financial world. Coastline Credit Union provides a banking experience that feels much more traditional and deeply rooted in the community. If you are a Louisianian who wants a lender that acts like a neighbor rather than a cold, massive corporation, this is a fantastic choice.
Because these are member-owned cooperatives, their primary motivation is serving you, not squeezing every penny of profit for distant shareholders. This structure frequently results in more adaptable terms for the people who use them. It is a refreshing change of pace from the “one-size-fits-all” approach found elsewhere.
You can access a wide array of services, ranging from standard loans to convenient online banking tools. While their entry requirements might be a bit tighter than a quick payday lender, the relationship you cultivate can be gold for your long-term fiscal health. Staying loyal can make getting a mortgage or an auto loan down the road much smoother.
Pros:- Operates under a member-first philosophy.
- Offers seamless mobile and online banking.
- Long-term membership can lead to better interest rates.
- You must meet specific eligibility criteria for membership.
3. LightStream
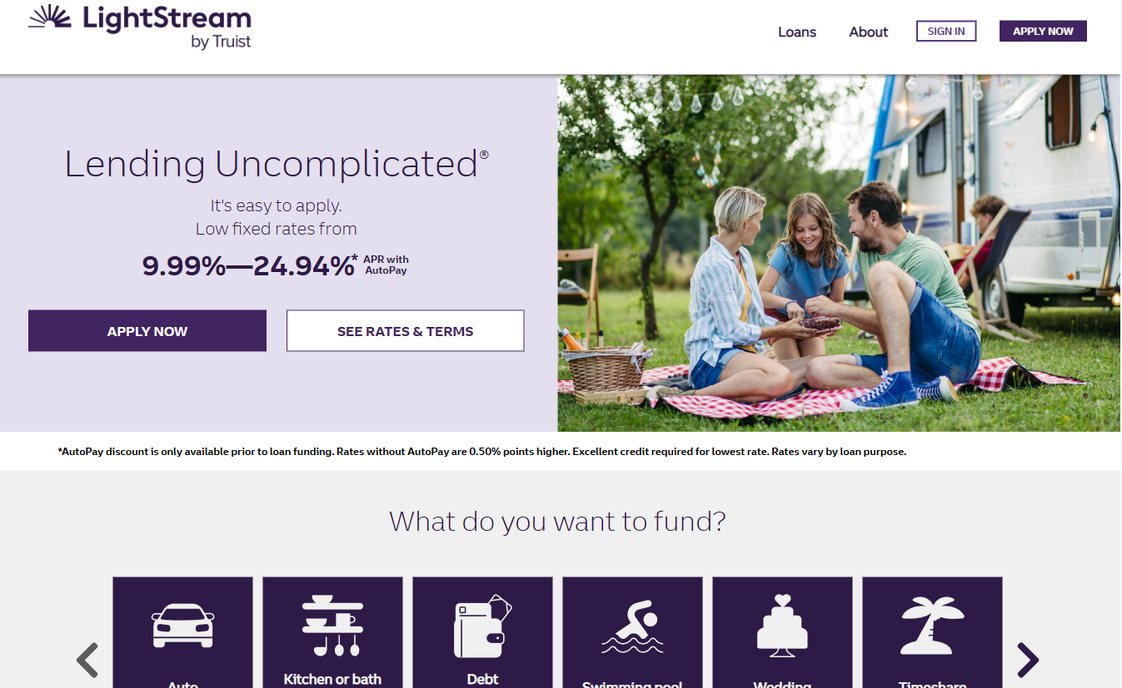
For those who have played by the rules and built a stellar credit profile, LightStream is a premium option. They aren’t exactly the cavalry for someone currently sinking in a deep hole of bad credit. However, for those standing on solid financial ground, they are truly difficult to beat.
The application process is incredibly streamlined, showing a deep respect for your precious time. This is the perfect vehicle for major life milestones where saving a few percentage points on interest can equate to thousands of dollars over time. It is about making your money work harder for you when it matters most.
The versatility of their platform is a major selling point, whether you are funding a wedding or a home renovation. Speed is their calling card; many customers report seeing funds in their bank accounts as soon as the next day. If you want to consolidate high-interest credit card debt into one manageable payment, their structure is built for that exact mission.
Pros:- Rapid funding, potentially by the very next day.
- Competitive fixed rates with discounts for AutoPay.
- Highly adaptable for many different loan uses.
- Only offers the best rates to those with excellent credit.
- Not an ideal solution for users with poor credit.
4. United Finance
United Finance is a seasoned veteran, having anchored itself in the lending industry since 1922. They bring a level of old-school stability that is increasingly rare in today’s fast-moving fintech landscape. They offer a variety of personal and auto loans designed to fit comfortably within a realistic household budget.
Their long history in the market proves they can weather any economic storm, from the Great Depression to the digital age. This longevity gives them a perspective that many new, app-based lenders simply do not possess. You can feel the weight of their experience in every transaction.
They strive to make the personal loan process straightforward and accessible. By providing a dedicated team of friendly experts, they offer a human touch that is vital when digital forms feel overwhelming. This is a huge plus for borrowers with complex income, such as self-employed individuals, who might be rejected by a cold, automated algorithm.
Pros:- Deep-rooted stability and decades of expertise.
- Personal loans available in amounts up to $20,000.
- Provides options for auto loans and refinancing.
- A more traditional approach may result in slower processing.
5. Addition Fi
Addition Financial operates with a clear mission: helping their members grow their wealth and master daily banking. They are much more than just a place to borrow money; they act as a comprehensive financial partner. From your everyday checking account to long-term investment options, they aim to be your one-stop shop.
Having your entire financial life under one roof makes it incredibly easy to monitor your spending and savings habits. They offer competitive rates and foster a strong sense of community. For anyone looking to move away from the impersonal nature of massive national banks, Addition Fi provides the necessary toolkit.
Their ecosystem is designed to support you through every season of life. Whether you are securing your very first car loan or starting to plan for your eventual retirement, they are there to guide the way. It is about building a foundation for a prosperous future through personalized service.
Pros:- Extensive array of investment and banking services.
- Community-focused through various referral programs.
- Offers competitive rates across their product line.
- Full access to benefits requires becoming a member.
6. GadCapital
When the situation becomes dire and the clock is ticking loudly in your ear, GadCapital is the “break glass” option. They specialize in installment and payday loans specifically for those struggling with bad credit. They are built for immediate action, especially when traditional banks have slammed the door on you.
This is a niche service intended for high-urgency moments where waiting three days for an approval is simply not an option. The platform handles very small, rapid loans, with amounts starting from just $100. If you are staring at a utility shut-off notice or an unexpected medical co-pay, they are built for that pressure.
While they provide a quick fix without a long, drawn-out credit check, there is a catch. You must be incredibly disciplined with your repayment schedule. If you lose track, the high interest rates can create a compounding effect that is very difficult to escape. It is a tool to be used with extreme caution.
Pros:- Certain loan types do not require credit checks.
- Provides near-instant access to emergency funds.
- Flexible funding amounts from $100 up to $5,000+.
- Payday-style products can carry very high costs.
- Carries a significant risk of a debt cycle.
Calculating Your Actual Debt Obligations
It is remarkably easy to get blinded by a low monthly installment. A person might see a $500 loan with a $50 monthly obligation and think it is a breeze. It feels like a small, manageable piece of the pie. However, looking only at the immediate cost is like navigating a ship without a compass.
If that specific $500 loan is stretched over twelve months, the total cost reaches $600. Suddenly, you realize you have handed over an extra 20% just to access the original capital. Always demand to see the “Total Repayment Amount” before you ink your signature on any paperwork. This specific number reveals the full weight of the debt you will eventually carry.
Don’t let the fine print trip you up when you are in a hurry. Knowing the final sum ensures you aren’t surprised by how much cash has actually trickled out of your bank account by the time you are debt-free. It is the only way to see the true face of the loan.
Distinguishing Between Interest Rates and APR
You must grasp the vital distinction between the nominal interest rate and the APR (Annual Percentage Rate). Many people mistake the two, which can lead to expensive surprises later. The interest rate is only one part of the equation when you are looking at the big picture.
The APR is a much more honest reflection of your expenses because it incorporates interest plus various administrative costs. This includes things like processing fees or origination charges that lenders tuck away. Without looking at the APR, you might be walking straight into a financial trap.
When you are weighing two different lenders, the APR is your best friend. You might find a company offering a lower stated interest rate, but their upfront fees might be massive. In almost every scenario, the lender presenting the lower APR offers the more economical path for your wallet. Always compare them side-by-side to find the real winner.
How to Get Ready for Your Application
Stepping into the loan process without a plan is like sailing into a storm without a compass. You want to walk through that door with confidence and a solid foundation.
To boost your odds of success and snag the most favorable interest rates, consider following these three vital preparation stages:
- Organize Your Paperwork: Collect your latest income statements, W-2 tax forms, and recent service bills. Because lenders need undeniable evidence of where you live and how you earn your paycheck, having these files handy is a game-changer. Digitalizing them beforehand can turn a waiting period of several days into a lightning-fast approval process that takes mere minutes.
- Scrutinize Your Credit Report: You can utilize no-cost tools like AnnualCreditReport.com to peer into your financial history. If you spot a discrepancy—perhaps a cleared debt that still shows as outstanding—file a dispute right away. It is a tiny detail that carries massive weight; one single mistake might be the only thing standing between a 620 score and a 650 score.
- Evaluate Your DTI Percentage: Sum up every recurring monthly cost, such as your mortgage or rent, vehicle installments, and minimum credit card payments, then divide that total by your gross monthly earnings. Generally speaking, most lenders hunt for a DTI that sits under 36-43%. Grasping this figure helps you determine your actual borrowing capacity and prevents you from biting off more than you can chew.
Mastering the Borrowing Journey
Before you put pen to paper, pause and scrutinize the small print. It is incredibly easy to let the rush of a fast approval cloud your judgment. However, the real weight of the debt lies in the total cost of borrowing. Don’t just fixate on monthly installments; you must examine the APR to see the actual price tag of the money you are taking on.
Missing a due date can feel like a minor hiccup, but it often behaves like a thorn in your side. Even when a lender is willing to overlook a poor credit history, a single slip-up can haunt your financial profile for a long time. You need to ensure that every installment fits snugly within your current lifestyle without sacrificing essentials like housing or food.
Think of your monthly budget as a safety net. Keeping a small cushion of extra cash is your strongest shield against the unexpected. Without that breathing room, a sudden car repair can turn a manageable loan into a total disaster. It is better to play it safe than to live on the razor’s edge of insolvency.
Beware the allure of the “magic pill” solution. While short-term options, such as payday loans from GadCapital, can act as a life jacket during a sudden storm, they can quickly transform into an anchor of debt. If used carelessly, these quick fixes will leave you drowning in interest. Treat them as a last resort for genuine emergencies only.
Instead of relying on temporary patches, aim for more permanent structures. Building a solid track record with credit unions or traditional personal loans from reputable institutions is a much wiser path. Consistently paying on time is the ladder that helps you climb out of a credit pit. It is the most reliable way to secure lasting financial independence.